Spearheaded by SEBI Research Analyst Nikhil Gangwar. The firm offers expert stock recommendations on Smallcase.
SEBI RA - INH000012801
BSE Enlistment No - 5833
More on Gaja: on the concall, ~13 cr of performance income was Fund II carry and ~17 cr sponsor gains on Funds III and IV. The steadier lever is fee-paying capital, ~3,200 cr today, with Fund V (2,500 cr) and a 1,500 cr secondaries fund coming. No close dates given. Not advice.
Gaja Alternative Q1: PAT up 36% to 27.2 cr, but the card shows sales down 49% and negative EBITDA as screener counts only fees as sales. Fees grew 7%. Profit came from 29.7 cr of carry and gains on its own fund stakes, which is lumpy. Good quarter, not a run rate. Just my take.
Biggest gainers on NSE/BSE for Sep 22, and the actual trigger behind each one.
Optiemus locked at 20% on the Nothing JV, Transrail moved on a conductor capacity expansion, and defence plus capital goods names did a lot of the heavy lifting. Where no same-day trigger could be confirmed, the table says so.
#NSE #StocksToWatch
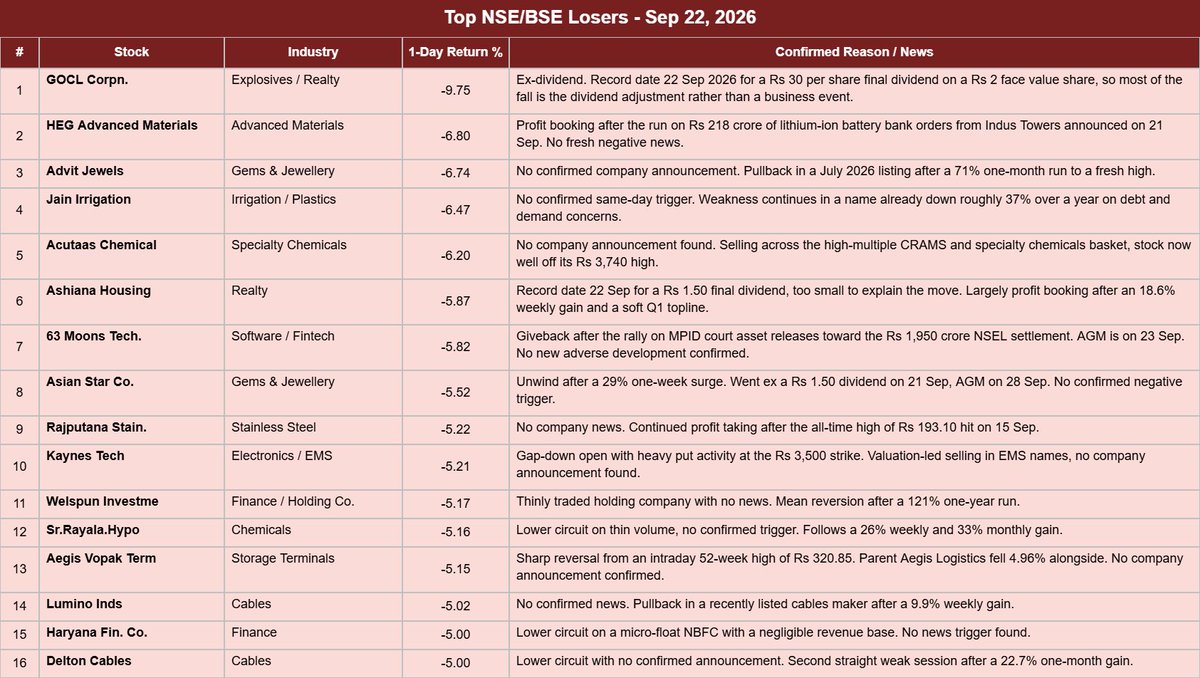
Who's down today on NSE/BSE and why:
Two names did most of the damage at the top. GOCL went ex a Rs 30 dividend, and HEG gave back Monday's order-driven pop. Everything below that is profit booking, plus a handful of small caps parked on the lower circuit with nothing to explain it.
#NSE #StocksToWatch
More on Lumino Industries: the whole quarter came from EPC. EPC revenue up about 70% to 150 cr while manufacturing crawled 6% to 371 cr. Order book is 3,059 cr, 2,013 cr of it EPC, but it is down 2.9% YoY. Ranihati adds just 10,000 MT in H2 FY27. Just my take.
Lumino Industries Q1: revenue up only 19% to 521 cr but EBITDA up 34% and PAT up 32% to 40 cr. Margin went 12.1% to 13.6%, so this is a mix and cost story more than a volume one. First print since the Sept 3 listing. Order book is what I am watching. Not advice.
Puravankara has secured a 13.44 acre land parcel in Greater Noida with 4.57 million sq ft of saleable potential and an estimated GDV of Rs 5,200 Cr.
This is the company's first entry into Delhi-NCR. The parcel has been allotted to its wholly owned subsidiary Prudential Housing and Infrastructure Development Limited.
Scale check. The Rs 5,200 Cr GDV is about 1.3 times TTM consolidated sales of Rs 4,064 Cr and roughly equal to the market cap of Rs 5,170 Cr. GDV is an estimated development value over the project life, not an order book and not booked revenue.
Including this parcel, the company puts FY27 business development across Delhi-NCR, Mumbai and Bengaluru at about 10.74 million sq ft of saleable area and Rs 14,100 Cr of estimated GDV. The 4.57 million sq ft added sits against a land bank of about 40 million sq ft as of 30 June 2026.
This is a land allotment, not an order win. The filing discloses no land cost, no consideration, no launch date and no completion schedule.
Context. Puravankara has so far built mainly in southern and western India, with 97 completed projects of about 59 million sq ft across nine cities. TTM net profit is Rs 151 Cr and borrowings stand at Rs 5,595 Cr. The filing also references a Rs 2,600 Cr redevelopment win in Goregaon West, Mumbai.
What I am watching: the acquisition cost of the parcel and how it is funded against Rs 5,595 Cr of existing debt, and how quickly the 4.57 million sq ft moves to launch.
Source: exchange filing
Pace Digitek's material subsidiary Lineage Power has received a letter of award of Rs 488.46 Cr, inclusive of taxes, from NTPC GE Power Services.
The scope is supply, delivery, testing and commissioning of battery energy storage containers with BMS and EMS, along with a comprehensive maintenance contract for 12 years.
Size: Rs 488.46 Cr equals 17.3% of TTM consolidated sales of Rs 2,830 Cr and 13.3% of the market cap of Rs 3,686 Cr.
Timeline: the filing states the order is to be completed by December 31, 2026, so the supply portion lands inside the current financial year rather than spreading across several years.
What it changes: this is an order win booked at a material subsidiary, not a purchase commitment by the parent. It layers a storage systems contract on top of the existing telecom and energy infrastructure base.
Context: TTM net profit is Rs 315 Cr, fixed assets are Rs 209 Cr and CWIP is Rs 38.3 Cr, so this is supply led execution rather than a capex cycle.
What I am watching: how much of the Rs 488.46 Cr is recognised by the December 2026 deadline, and whether the 12 year maintenance contract is disclosed as a separate recurring line.
Source: exchange filing
More on Vipul Organics: the FY26 annual report says the new Sayakha plant lifts rated pigment capacity from about 2,000 to 10,000 TPA, starting near 1,800. Tarapur folds into it and it was funded with equity, not debt. Almost none of that is in Q1 yet. just my take
Vipul Organics Q1: revenue up 38% to 52 cr and PAT doubled to 2.5 cr, but that 100% sits on a tiny 1.3 cr base. EBITDA up 32%, so it trails sales slightly. Capex cycle is done and cost work is showing. 62x for a 52 cr quarter looks full. just my take
More on Rubicon Research: the concall says they gave up relatively lower margin business and cut reliance on contract manufacturing, taking gross margin to 67.7%. FY27 EBITDA margin guidance raised to about 23%. A one-off insurance claim sits in that PAT. not advice
Rubicon Research Q1: revenue up 52% to 534 cr, EBITDA up 63% and margin 22.4 to 24.2%. PAT nearly doubled to 85 cr, flattered by lower interest post IPO. Specialty products did the heavy lifting. At 99x earnings a lot is already priced in. not advice
Knowledge Marine has received a work order from Mumbai Port Authority valued at Rs 279.33 Cr including taxes.
The scope is chartering of one 60 Ton bollard pull capacity battery operated electric green tug along with manning, operations, maintenance and complete technical management for 15 years.
Against TTM sales of Rs 323 Cr the full contract is about 86 percent of one year of revenue. Annualised over the 15 year tenure it works out to roughly Rs 18.6 Cr a year, near 6 percent of TTM sales, and about 3.8 percent of the Rs 7,319 Cr market cap.
Timeline. The order runs 15 years. The filing gives no start date and no year wise revenue split.
What it changes. Un-executed order book was Rs 1,395 Cr at March 2026 on Screener data. This award adds roughly 20 percent to that base, and it is charter plus operations and maintenance revenue rather than a one time build.
Context. Fixed assets were Rs 211 Cr with CWIP of Rs 99.2 Cr at March 2026 and TTM net profit is Rs 131 Cr. The award is from a domestic entity and the company states it does not fall within related party transactions.
What I am watching. How the Rs 279.33 Cr is phased into revenue across the 15 years, and whether the tug is capitalised on the company balance sheet.
Source: exchange filing
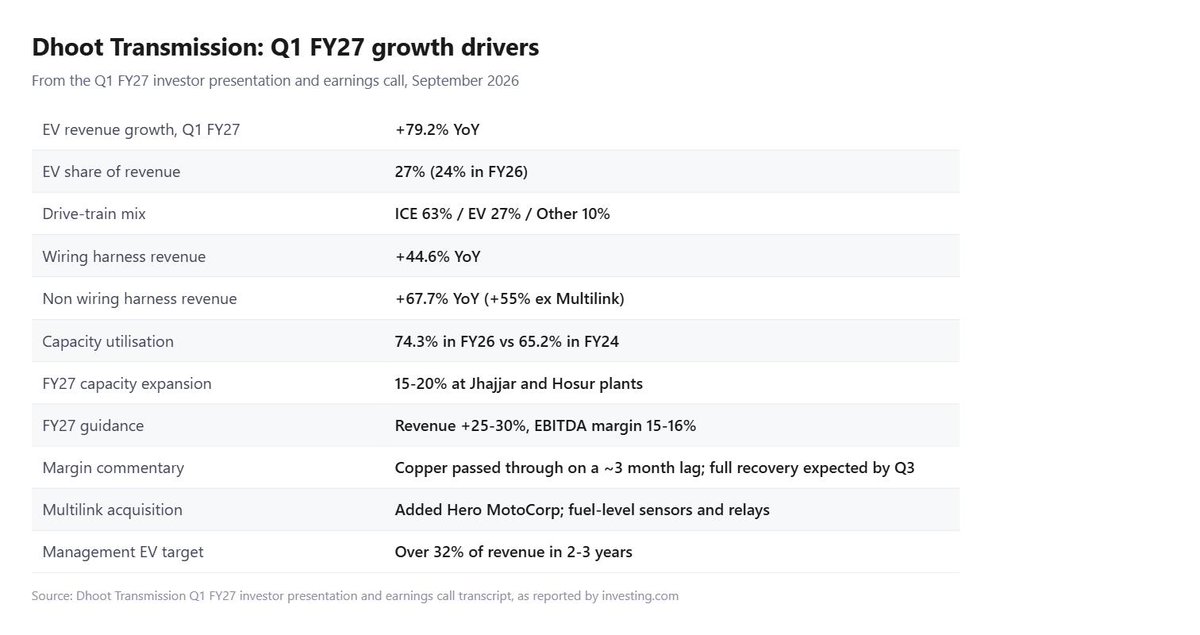
More on Dhoot Transmission: the Q1 deck puts EV at 27% of revenue, up 79% YoY, ICE still 63%. Management says the margin dip is copper, mostly passed through but on a three month lag, so full recovery only by Q3. Utilisation 74%, adding 15-20% at Jhajjar and Hosur. just my take
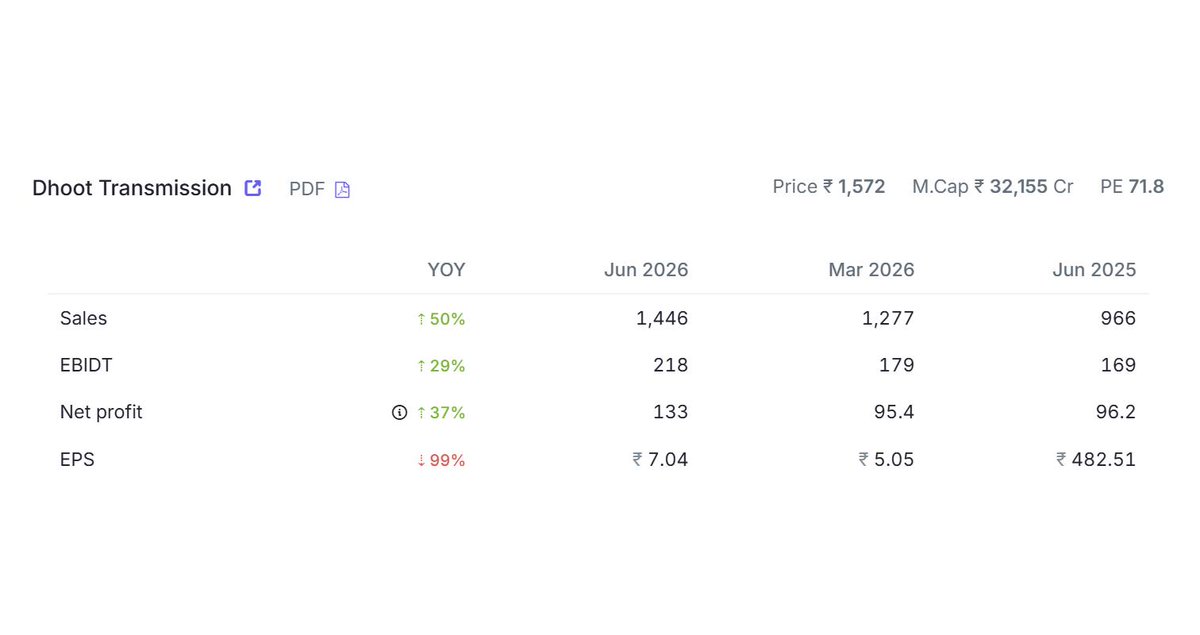
Dhoot Transmission Q1: revenue up 50% to 1,446 cr but EBITDA only up 29%, so margin slipped to 15.1% from 17.5%. PAT up 38% to 133 cr. EV wiring is doing the heavy lifting here. Volume growth is real, pricing power isn't. Management still guides 25-30% for FY27. not advice
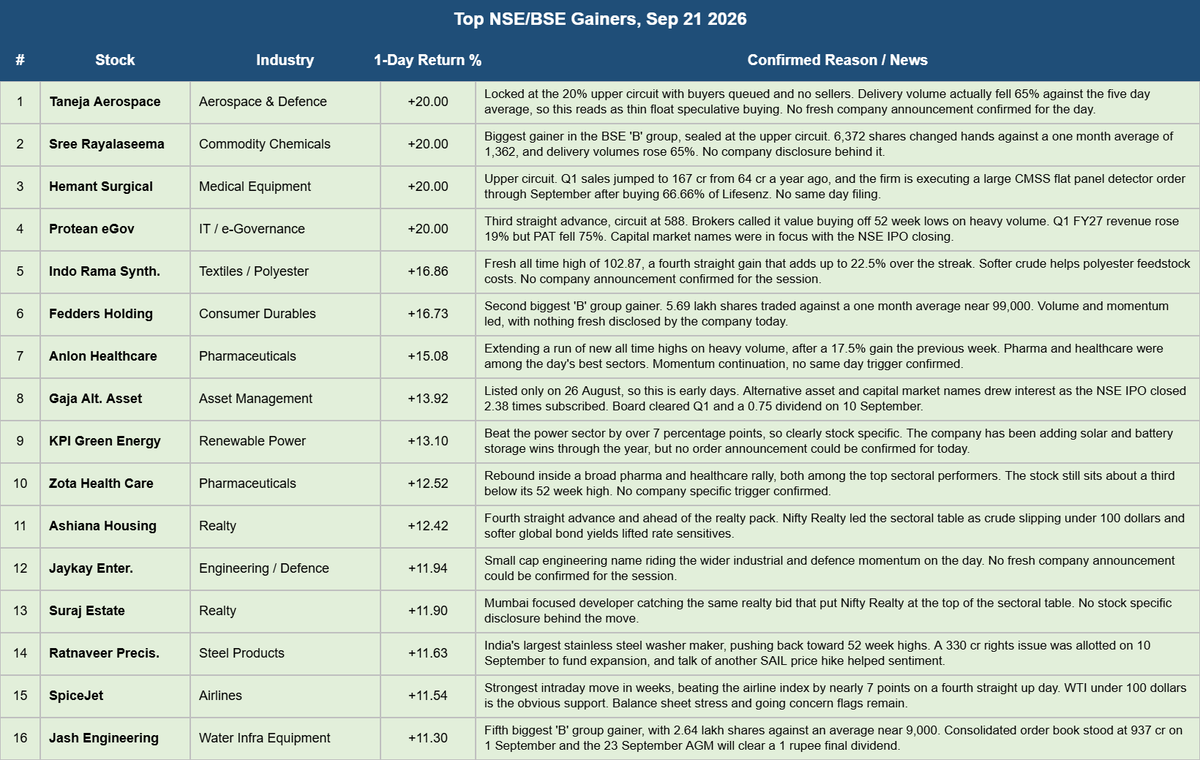
Biggest movers on the Street today, and the actual reason behind each one. Four names shut at 20% circuits, realty led the sectoral table, and a few small caps just ran on volume with nothing to show for it. #NSE#StocksToWatch
Who's down today on NSE/BSE and why. Most of this list is profit booking rather than bad news, several of the top fallers had run up hard into last week. Oracle Financial Services is the one with a real catalyst, hit by parent-level data centre debt worries.
#NSE#StockMarket
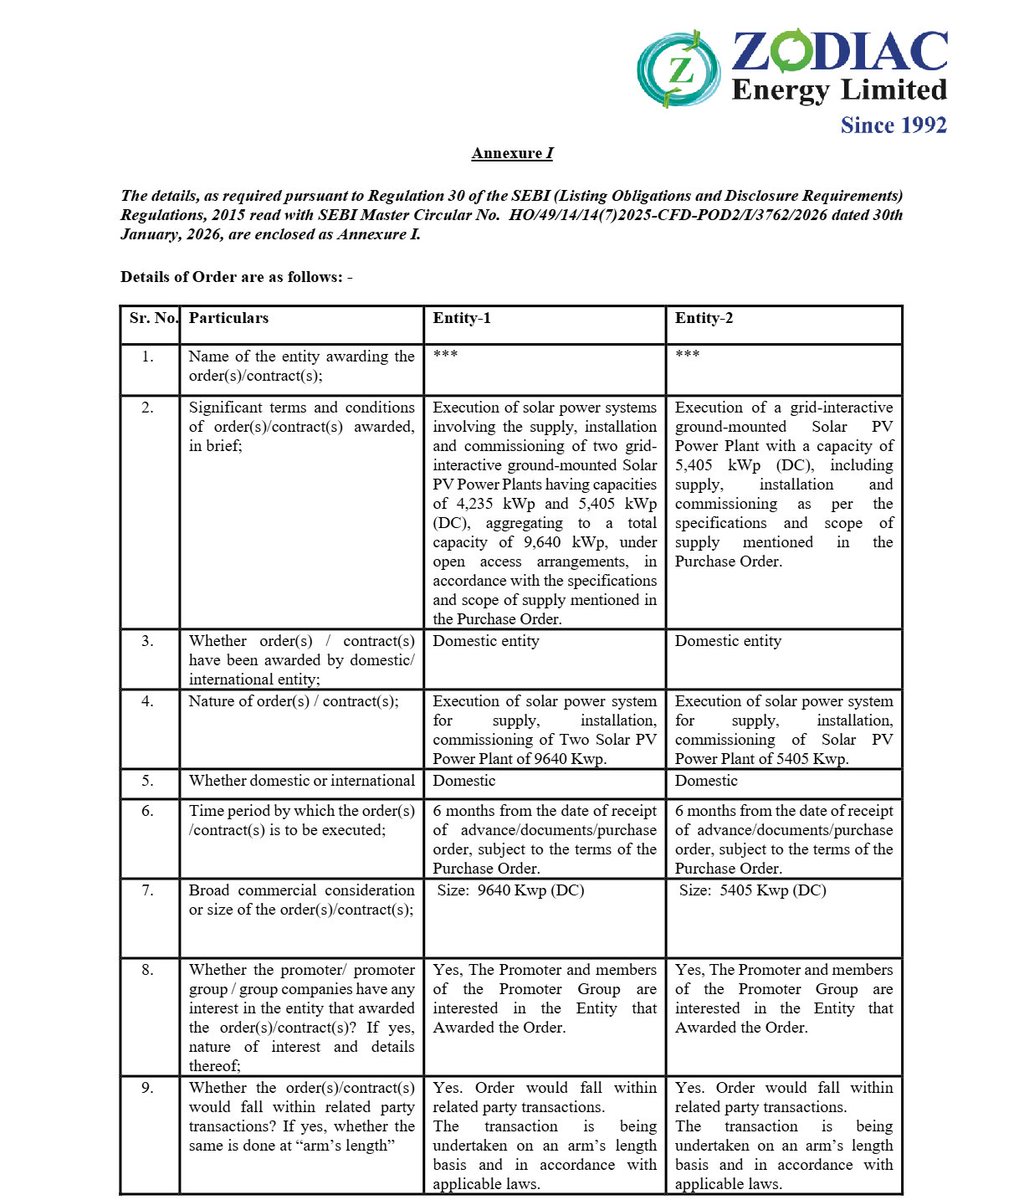
Zodiac Energy has received purchase orders for 24.76 MWp of ground-mounted solar plants from four entities.
All four buyers are entities in which the promoter and promoter group are interested. The company has classified the orders as related party transactions on an arm's length basis.
The split: 9.64 MWp (two plants of 4.235 and 5.405 MWp), 5.405 MWp, 5.405 MWp and 4.31 MWp. Scope is supply, installation and commissioning of grid-interactive plants.
Execution period is 6 months from receipt of advance, documents or purchase order.
No order value is disclosed. The buyers' names are masked in the filing. All four are registered in Gujarat.
For scale: TTM sales are Rs 587 Cr, net profit Rs 25 Cr, market cap about Rs 337 Cr.
What I am watching: the order value when it appears in related party disclosures, and the margin on this work against third-party EPC.
Source: exchange filing
More on Lalithaa: the Q1 deck shows 10,407 cr of gold inventory with only 54.6% naturally hedged by customer advances and creditors, leaving 4,727 cr exposed. That is why a gold spike lifts revenue but squeezes margin. 47 of 65 stores sit in tier 2 and 3. not advice
Lalithaa Jewellery Q1: revenue up 26% to 6,040 cr but EBITDA fell 14% and PAT dropped 21% to 208 cr. Margin went from 9% to 6.2%. Gold price inflation flattered the topline and costs ate the rest. Volume is the number to watch here, not revenue. just my take