Dont fight terminal value risk citing cheap valuations , that is the only part where being a value investor is going to back fire , market always knows more , be humble to accept it rather than frustrated why a 12 PE stock is not going up ..
Industry structure , terminal value all are important , not just deep value , sets the wrong expectations ..
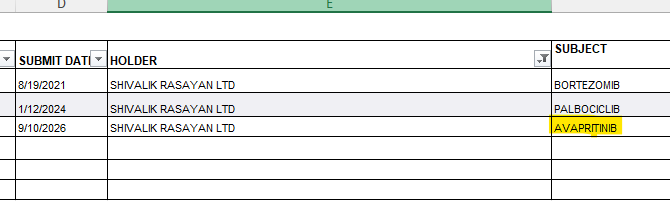
Shivalik Rasayan has filed a new DMF in this quarter , and again to my surprise this is for a subject called Avapritnib
Now again , this is very ambitious of them to file this , as this has not been filed by many others , The innovator is Blueprint Medicines, now Sanofi. Sanofi agreed to acquire Blueprint in a deal worth up to $9.5B, and Ayvakit has been consolidated only from mid-July 2025. It treats PDGFRA exon 18 GIST and systemic mastocytosis. Sales are growing fast: €190 million in Q2 2026, or $221.3 million pro forma, up 26.4%, The 5-year NCE exclusivity from the January 2020 approval has already lapsed, so ANDAs can be filed now.
A paragraph IV challenge triggers a 30-month stay if the innovator sues. The first successful filer can get 180 days of exclusivity.
If all patents hold, the base case for generic entry is about 2034 here , so again , this is not something that will translate into anything meaningful in the next 3 years ,but to say the least this is a interesting for a company of this size to be filing ..
AYVAKIT (avapritinib) is an oral prescription kinase inhibitor developed by Blueprint Medicines. It blocks abnormal receptor tyrosine kinase proteins like PDGFRA and KIT to treat rare cancers and blood disorders
not something that is going to create value immedietly , but it tells us something about what the management is trying to build out over the next decade
The first avapritinib DMFs only appeared in June 2026, even though ANDAs have been fileable since the NCE-1 window opened in January 2024. Any ANDA customers are probably early in development. I’d read this as a long-dated option on roughly 2030–34 entry, not near-term revenue.
Just an update on shivalik's recent filings .., as a part of our series on filings updates by Indian Pharma
no reco ..
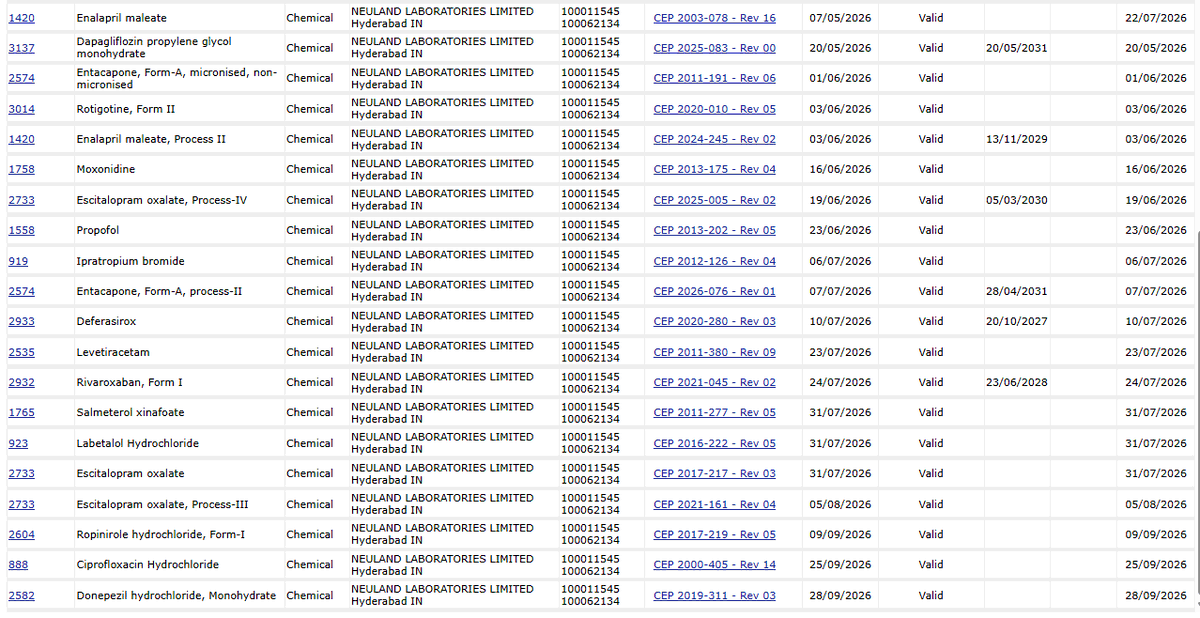
Neuland Labs is agressively filing CEP'S with the European regulator in the last 6 months , let me contextualise the word agressive :
From 2017-2025 = 13 CEP Filings
2026 Total : 23 CEP filings
last 6 months : 8 CEP filings
Now this tells us a lot abou the work happening and also the incremental specialties that neuland is going to be focusing on as well in the years to come, I was also surprised with the rate of filings just in the last 6 months , and recent plant visit and pre poning of peptides comissioning and demand drivers seem to be indicating the right things
Again this is not a quarterly story , but they are positioning themselves for the longer term in the right direction
Also not to get too excited and jump the gun it is important to understand that many are also repeat filings but let me tell you the ones worth focusing on more , now getting into some specifics :
The three filings I would prioritise are Dapagliflozin, Entacapone and Escitalopram Process-IV. They offer the best starting points for investigating market access, process differentiation and potential incremental customer opportunities. Rotigotine is worth a more specialised follow-up, but its commercial attractiveness depends on the formulation and patent landscape.
The strongest confirmed signal is dapagliflozin: Neuland has publicly announced the CEP and highlighted its relative scarcity among Indian suppliers. For the other filings, I would not yet claim an innovator tie-up or material revenue contribution.
Dapagliflozin was developed by Bristol Myers Squibb and AstraZeneca subsequently acquired the relevant rights. AstraZeneca markets it as Forxiga/Farxiga. The European CEP gives Neuland an additional regulatory credential for supplying the API to customers developing or manufacturing suitable products.
Entacapone , The main research question is why Neuland has a 2026 certificate identifier for a specific process/form when an older Entacapone Form-A CEP already exists. A second process can be economically valuable if it improves yield, impurity control, manufacturing costs or supply reliability.
Again this is a starting point for some pharma geeks , but the idea is that there is agression , a lot of it , and it is being validated by filings
If you all like such notes on pharma , little technical and more specific , do let me know in the comments , so I do this for all Indian CDMO'S and API as well
no reco at all
MTF panic + Fear in smallcaps is draining the market breadth and taking the recent winners to the cleaners , time to put head down read the businesses and map out next 12 quarters visibility and put the work in now more than ever
Fear amongst people+MTF positions= Hyper volatility in small and mid cap names
Try being a business analyst in such situations. Many businesses with strong results have been punished due to the above ⬆️
MTF selling has caused lot of pain in the recent winners , some of them in the Pharma space are showing good value, diffrentiate the lenght of the trend
Short term opportunities need to be capitalised
MTF selling has caused lot of pain in the recent winners , some of them in the Pharma space are showing good value, diffrentiate the lenght of the trend
Short term opportunities need to be capitalised
IT sector from peak pessimism tracker to now suddenly turned, that is the power of peak pessimism , it rewards with margin of safety
Sector doing well from peak pessimism
“The IT sector is going through a phase of carnage. The pain is real, but I believe some big winners will emerge from this disruption.”
“Companies with deep domain expertise and sector-specific knowledge are better positioned to implement AI effectively.”
“They understand the nuances of their industries and can use AI to deliver solutions that generic IT services companies may struggle to replicate.”
“Over time, a meaningful portion of the market capitalisation destroyed in traditional IT services could migrate to these domain-specific companies that are better positioned to capture the value created by AI.”
- Ameya Deosthali (@EquityValueIn)
Always keep a track of the ideas you rejected or currently opted out of for a reason , most of them always find a way back, somehow this happens more often than not , the only thing important is not to read it with a bias or baggage , so I make sure I acknowledge my bias before reading it so I can consciously avoid it and look at it just the way i would look at a fresh company
We don't win by having views , we win when we are rational
In today’s times Intelligence and Data is available very easily and cheap , courage is not , because it can’t be outsourced
Build character and courage , just having more illusion of data is not going to get the outcome ..
AI tool won’t help you when you have to buy at lower circuit or weak markets , but your courage will ..
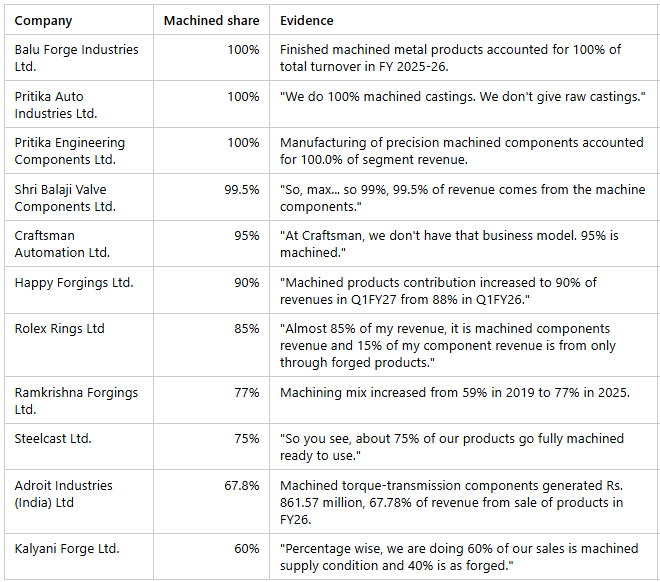
Forgings , machined share of Indian Listed players , that is the real value add and it shows in the per kg profits
Very interesting and well explained video by @suru27 and pic credit @Tijori1
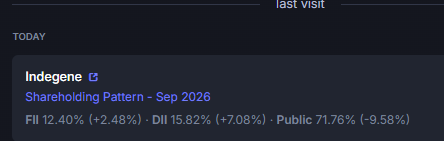
Indegene , slowly seeing the ownership allign , good for us !
Wallet share+ Tectonic+ Return of domain specific winning is the theme , spoke about it in the recent podcast as well
no reco , biased from lower levels