My best geopolitical analysts continue to be very skeptical of a near-term successful negotiation. Entrenched positions by Iran who views Trump as weakened post-election. Ongoing headline driven volatility not great for stocks, but current oil prices = FCF boon for companies.
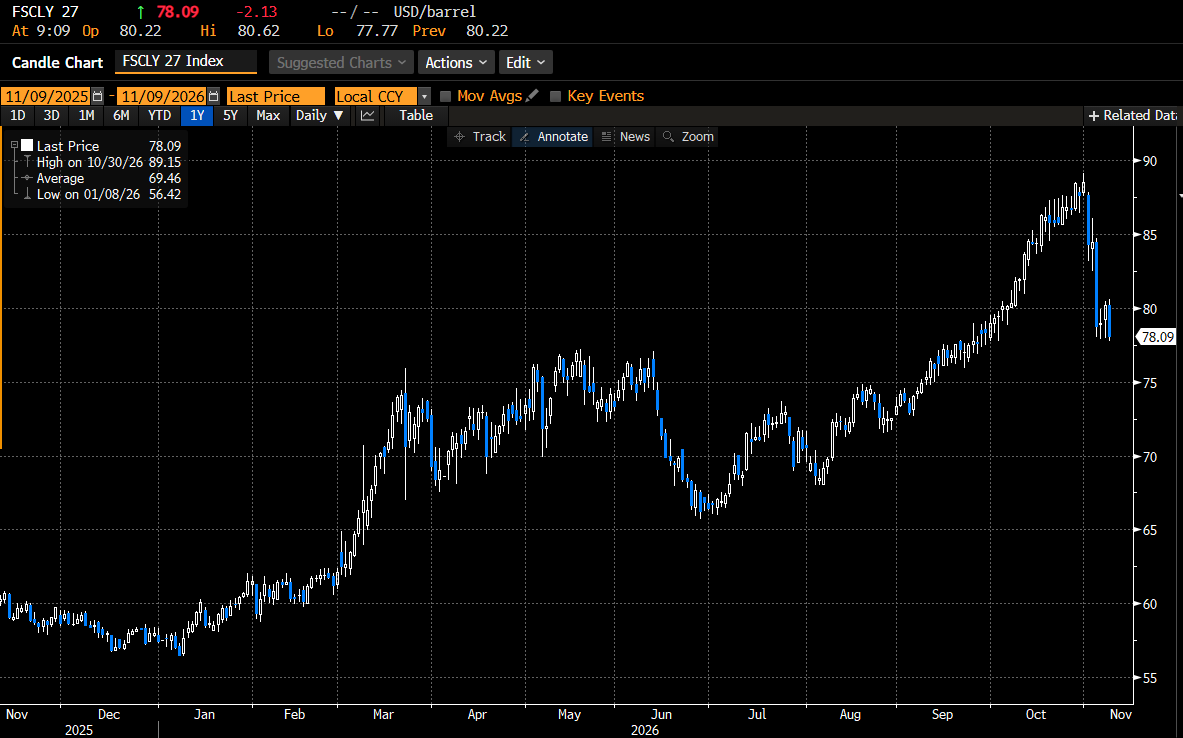
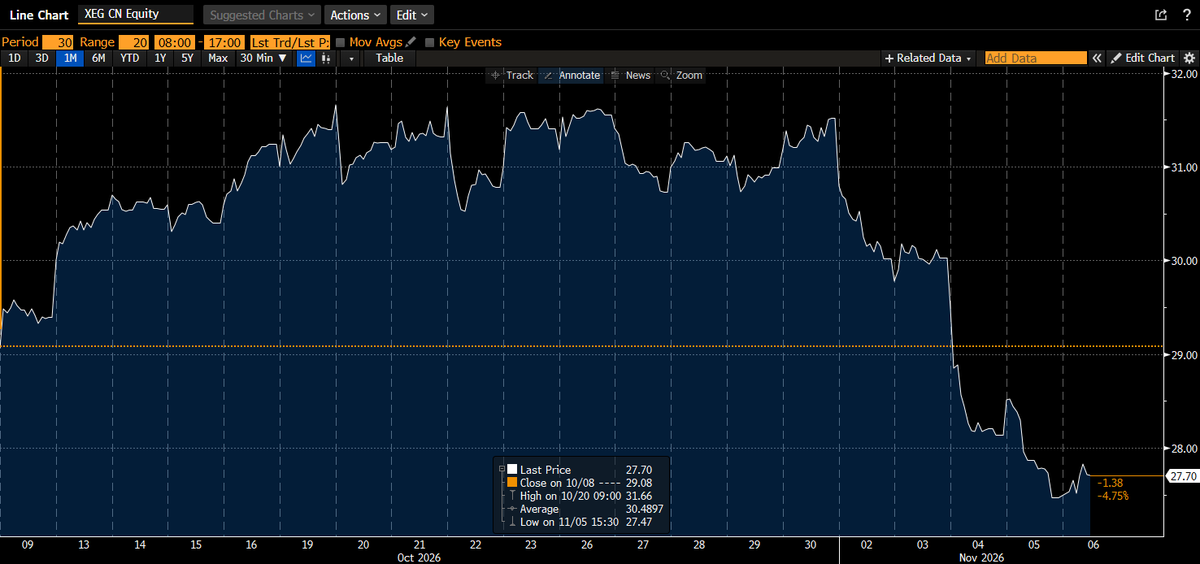
There is a reason why we didn't chase the oil price over the past few months. Now with stocks down 20%+ and the 2027 strip down >$10, we see compelling value in several names with FCF yields >12% at $70WTI.
3rd Law➡️2027 WTI strip now at $89/bbl, I think it prudent for oil companies to begin hedging. We should fully expect a non-OPEC supply response to high prices in areas like the Permian, Canada, and Argentina, while demand in some parts of the world is suppressed by high cracks.
Uncertainty = opportunity. What have we been buying the past few days after the 20%+ correction?
🛢️a company with European gas exposure that we think will free cashflow ~50% of their market cap over the next 2 years at strip
🛢️an oilsand producer with 35+ years of stay-flat inventory at 5.2x EV/CF and a 12% FCF yield at $70WTI
🛢️a Permian royalty co. with exposure to the best rock and best operators at a 13% FCF yield at $70WTI
🛢️a US/CDN driller at 3.1X EBITDA and a 20% FCF yield
🛢️a large cap uranium producer at 1.2X NAV that has fallen by 45% since January while spot/uranium prices have risen to at/near all-time highs
🛢️a Duvernay producer with massive running room at <3.5X EV/'28CF down 20% this week
🛢️large cap global oilfield service co.'s ahead of what we believe will be a 5%-10% growth capex cycle in 2027+
So what's our game plan? The market is assuming the historic Democratic sweep will force Trump to take his aircraft carriers and go home, essentially TACOing. This in spite of yet another 2 ships in the Strait struck overnight and his legacy in question. The oil market has violently corrected, with the 2027 WTI strip falling by ~$10 in the past 3 sessions, sitting about $10 higher than before the war. Oil stocks have been crushed, we think more by machine than by human as we could not find many major blocks to buy in stocks yesterday that were falling by 8% or more. It was all "in the machines." My view is oil stocks today are far more investable than they were a few weeks ago. Some are now near pre-war levels, while others have taken advantage of the past 9 month windfall to deleverage, consolidate, aggressively buy back stock, or at worst stockpile cash. Now that much of the war premium has been taken out, companies will feel more comfortable stepping up share buybacks. We are finding compelling value again and the sector is no longer "fairly valued" by our estimates at what we believe to be the marginal cost of supply ($70WTI). The war is not over and nor is the greatest energy supply crisis of our lifetimes. Oil exports through the Strait remain down 4-5MM Bbl/d, global oil inventories sit at record lows, and global SPRs will have to be restocked amounting to ~500k bbl/d of new demand for the next 3 years. Sentiment has gone from euphoria to disbelief in a matter of a week. Time will tell, but this feels like a good time to once again be selectively deploying capital.
There is blood in the streets and we are buying. At $70WTI you can now get a co. with royalties on the best rock in the best play in the US drilled by the best operators at a 13% free cashflow yield, or an oilsand co. with 35+ years of inventory at 5.2X EV/CF and a 12% FCF yield.
Wow, the war may have ended on the very day of the US midterms...what coincidence! We have for many months focused on "the day after" using $70-$75WTI for stock selection. Maybe that's today, maybe it isn't, but with the recent pullback the oil producers subsector has gone from fairly valued to now increasingly attractive with some names at <6x EV/CF and 11% FCF yields at $70WTI (strip = $83).
3rd Law➡️2027 WTI strip now at $89/bbl, I think it prudent for oil companies to begin hedging. We should fully expect a non-OPEC supply response to high prices in areas like the Permian, Canada, and Argentina, while demand in some parts of the world is suppressed by high cracks.
Despite Middle Eastern crude oil exports near/back to pre-war levels for over a month (?), onshore inventories have so far failed to rise, and the cost to accomplish this is a staggering ~$35/bbl. What happens if things escalate?
China is back buying oil (October imports now "only" down 1.8MM Bbl/d YOY) while Middle Eastern production remains down ~4MM Bbl/d vs. pre-war levels. 234 days into the "2 week incursion" and we've forfeited over 2BN barrels of production. Restocking to take years...
From 18 cents to $12 per share. Ninepoint's 2021 investment in Athabasca Oil has turned into a massive gain following Cenovus Energy's proposed acquisition of the company. Led by @ericnuttall and the Ninepoint Energy Fund team, the investment reflects a high-conviction view on Athabasca's assets and long-term potential. https://t.co/W8VbKmB6wy
Disclaimer: https://t.co/w5oALUJS5i
Varcoe: High oil prices leave Canadian oilsands producers with epic cash flow levels, some 'approaching debt-free status'
https://t.co/Bll6Xo6p7k #ableg#yyc#yeg#oilsands
We have in our energy strategies for the past ~2 months been defensively positioned. YTD returns have been solid and we feared bad energy policy from the WH (diesel export ban, etc.) ahead of the US mid-terms. With only 20 days to go to the election, we think that risk has been largely eliminated. The 2027 WTI strip is $84 offering eye-watering free cashflow yields for some, the situation in the Middle East continues to worsen with no end in sight, and for the first time in a decade we have a Canadian Government that is supportive of the energy sector. Despite some stocks appreciating by 70%+ YTD and making all-time highs, they are in some cases cheaper today than they were on January 1st. Given this, we have been deploying some of our cash, and continue to believe that we remain in a multi-year bull market for energy stocks.
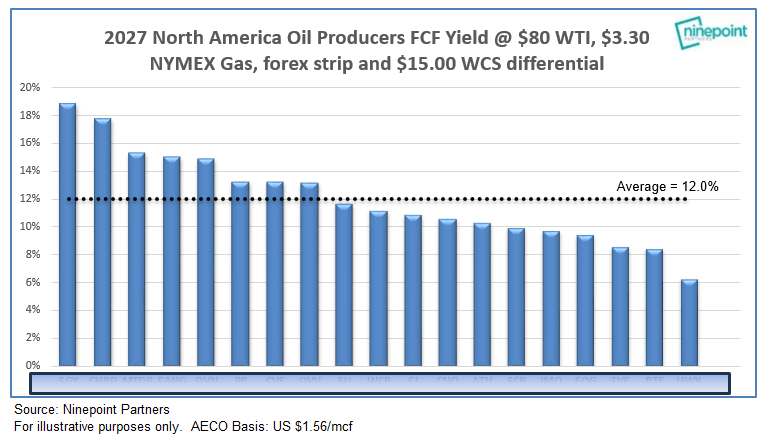
The question I ask myself every morning now...what oil price to underwrite for 2027? We've been using $70WTI, not a forecast but instead a defendable floor. If status quo persists, $80+WTI is on the table and with it a ~50% increase in average FCF yields:
We all know by now that these estimates move around, but with 2 ships/day over the past week getting hit by the IRGC, there seems to have been a believable, notable drop in Hormuz oil exports. $80+ 2027 WTI strip becoming more real by the day:
Joined the Global Risk Institute's 2026 Summit to talk about how the world has changed.
For much of my career, I thought about risk from the perspective of a banker.
Today, I think about it from the perspective of a country. The perspective of a Canadian who knows this is the best country in the world, and it can still get better.
The scale is different, but the principles are not: build optionality, avoid concentration, invest in productive assets, and never assume that the conditions that prevailed yesterday will prevail tomorrow.
Canada cannot control the rupture happening around us. But we can control our response, and we can build an economy that is not simply capable of surviving the next shock, but positioned to seize the opportunities that come with it.
That is the opportunity in front of us. I am confident we can, and will, seize it. 🇨🇦