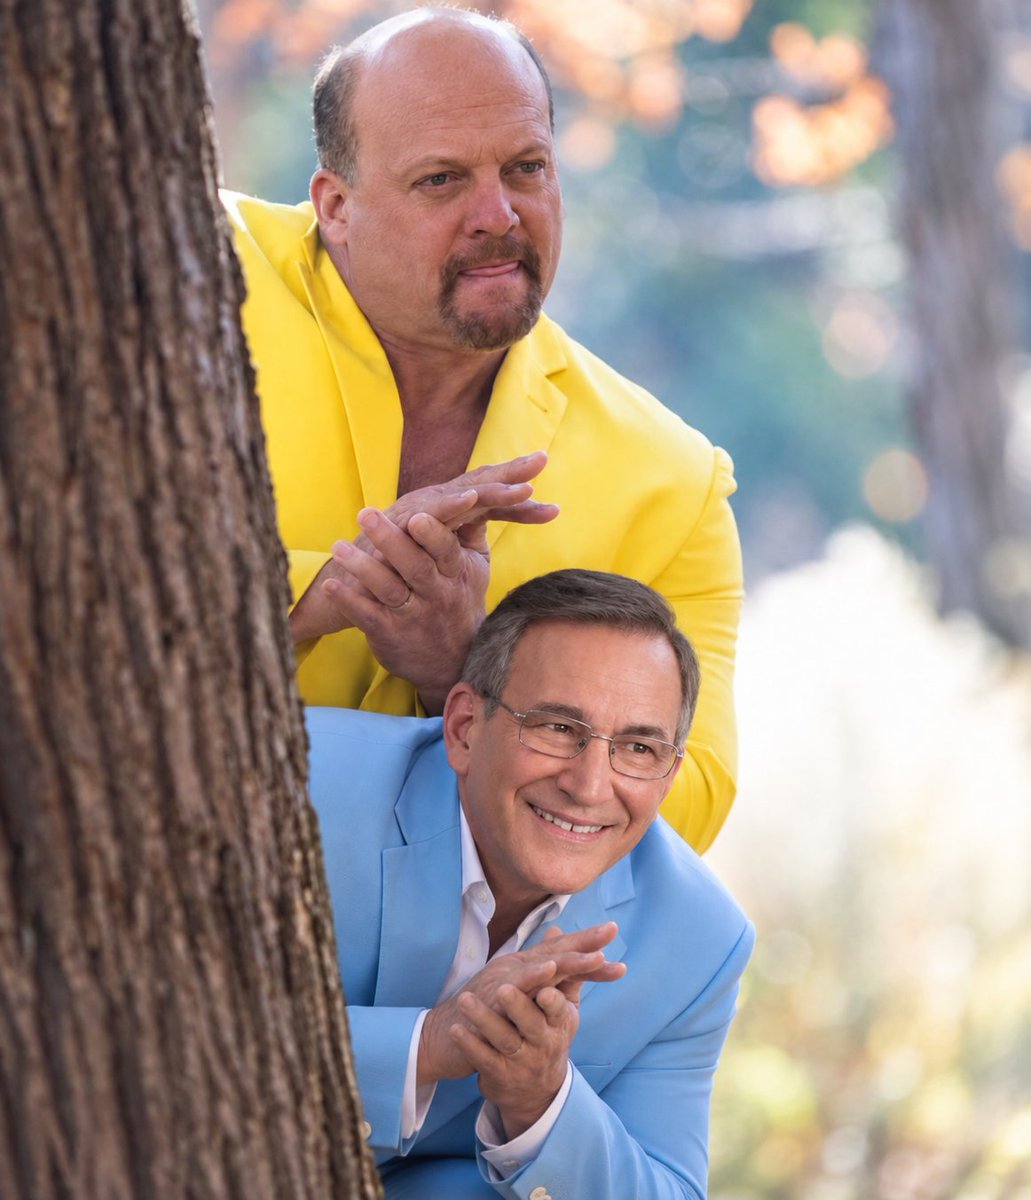
Kashkari: "I can tell AI 'take my kids & put them on a horse...eating strawberry ice cream'...it takes 1 minute...to create a 6 second video...It takes as much electricity as running your dryer for an hour."
Full disclosure, this video took about 2 hours of dryer time.
Liesman: "What good does it do to raise rates for people in AI... a quarter point is like I'm laughing at you. Then you say 'your mortgage will be 7.5% - 7.75%, not 7%'...that matters a lot."
Kashkari: "we have to use the tools we have, & monetary policy is a blunt instrument"
Kashkari: "higher interest rates are the mechanism by which capital gets reallocated in a market economy to its most productive use...capital that would have gone to build homes...to instead build data centers...it's not the Fed's job to stop that"
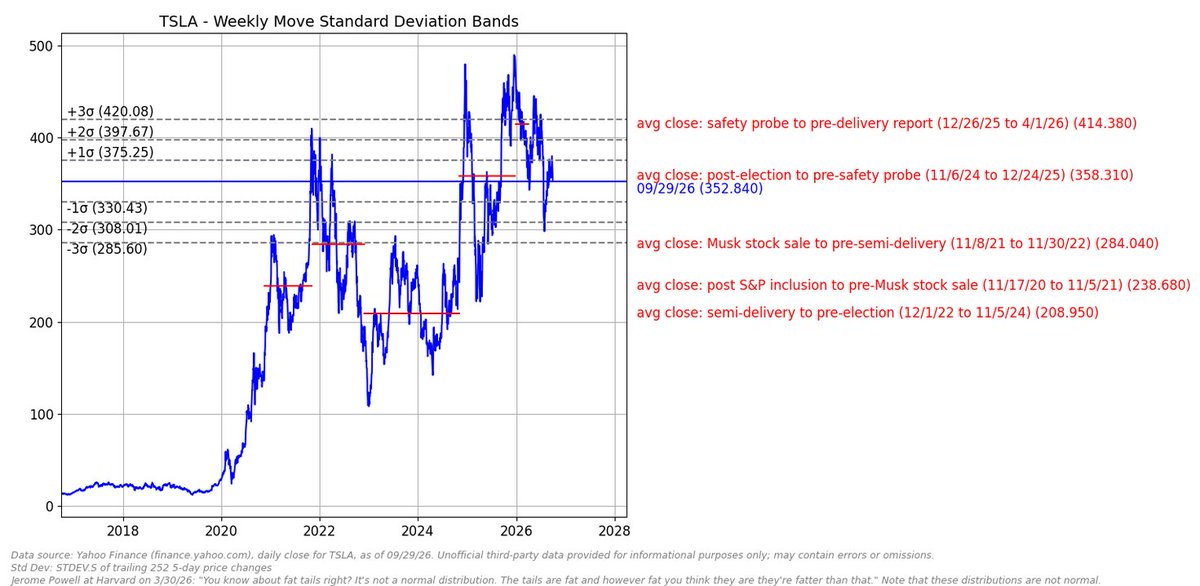
$TSLA eras, avg close:
S&P entry: market buys hype ($239)
Musk sells: stock holds up ($284)
Semi to election: priced like carmaker ($209)
Post-election: bet on friendlier DC ($358)
Probe era: full price for robotaxi/AI despite noise ($414)
Now $351: near post-election avg
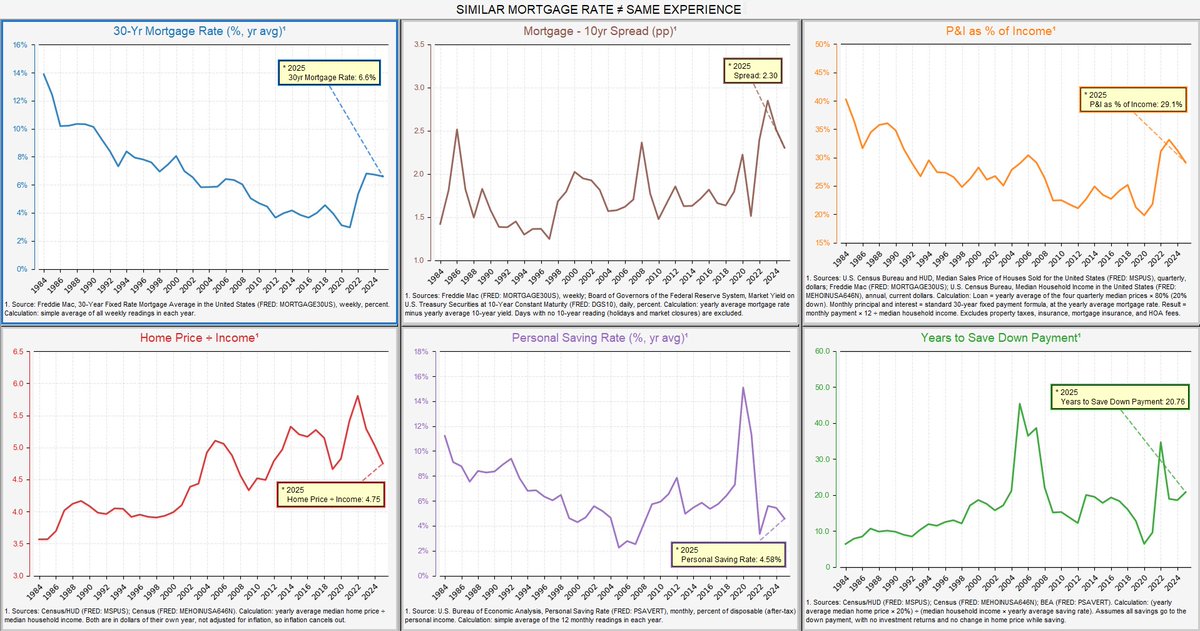
Housing Affordability: Normal rate. Abnormal wait.
Top: rates look normal, the premium over the 10-yr* is easing & the payment as % of income is near average.
Bottom: homes cost 4.8x income vs 3.9x in the '90s, we save less, & a down payment takes ~20 years vs ~10.
@MikeZaccardi Can someone tell the boomers that inflation will come down if they stop spending and buy bonds?
War bonds of the past = millennial bonds of today. #savethefuture
@MikeZaccardi Can someone tell the boomers that inflation will come down if they stop spending and buy bonds?
War bonds of the past = millennial bonds of today. #savethefuture
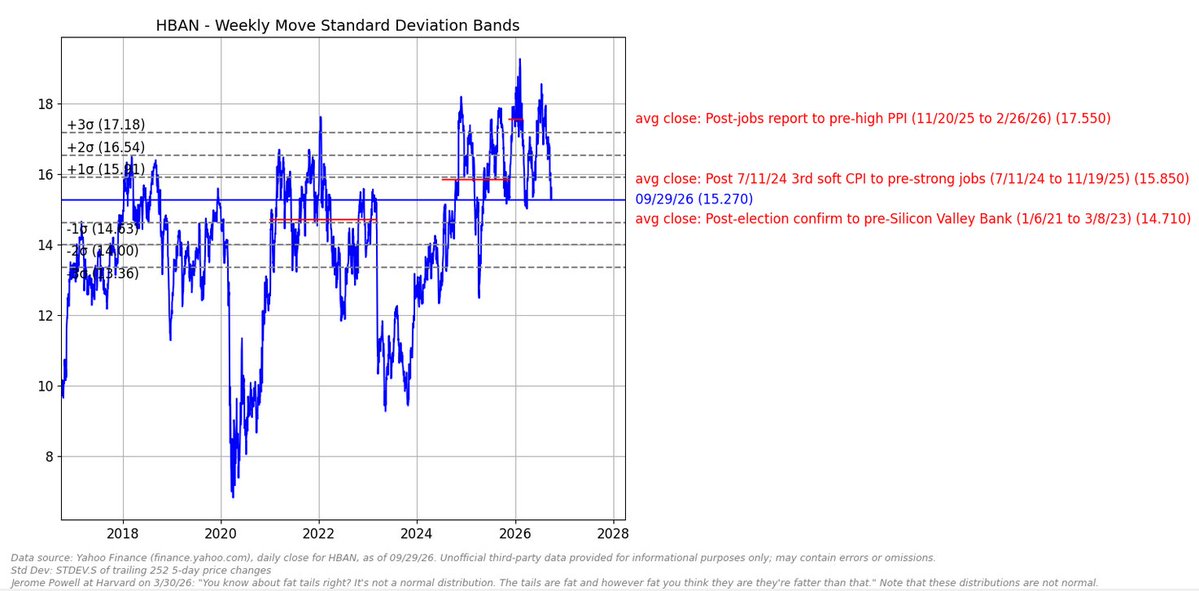
Timur Braziler, UBS: "what does the margin trajectory look like with one hike?"
Hope Dmuchowski, CFO: "the loan side reprices up first and the deposit price will lag... So you'll have some margin expansion in that first quarter, and then you'll see it compress back"
Housing Affordability: Normal rate. Abnormal wait.
Top: rates look normal, the premium over the 10-yr* is easing & the payment as % of income is near average.
Bottom: homes cost 4.8x income vs 3.9x in the '90s, we save less, & a down payment takes ~20 years vs ~10.
@MikeZaccardi Powell at Harvard 3/30/26: "energy shocks have tended to come & go pretty quickly. Monetary policy works with long & variable lags famously"