Chartered accountant from ICAP, love to read, write and talk on economy and finance. Work at Kifayah Investment Advisors and do separately managed accounts.
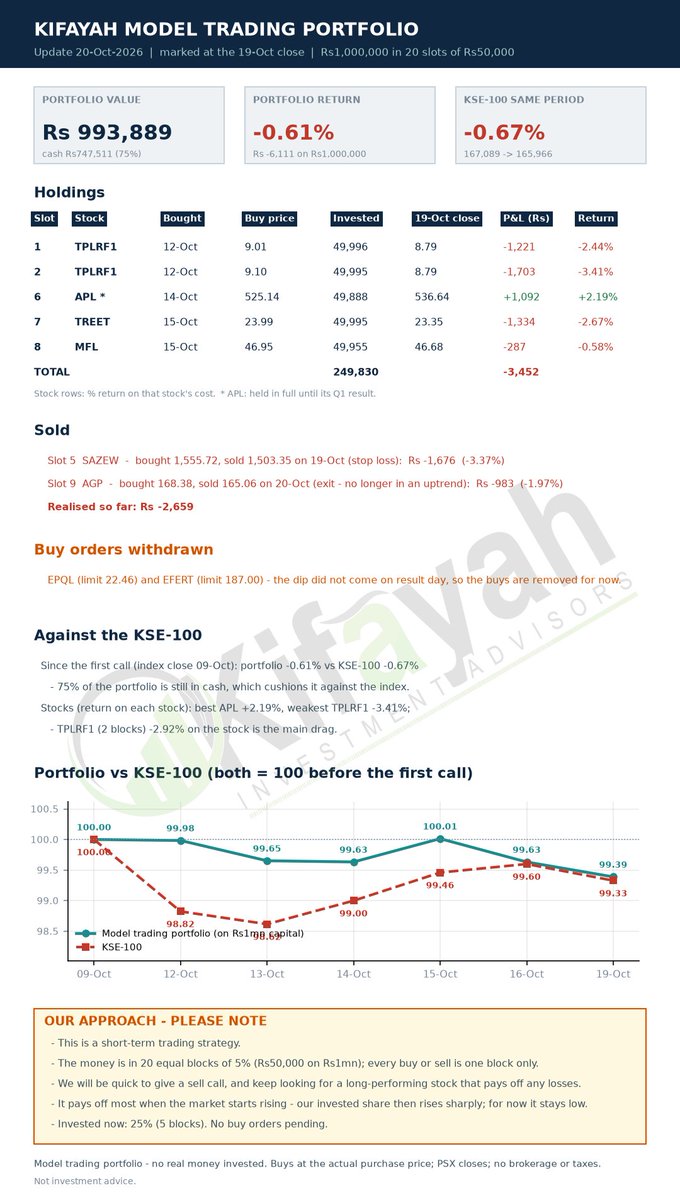
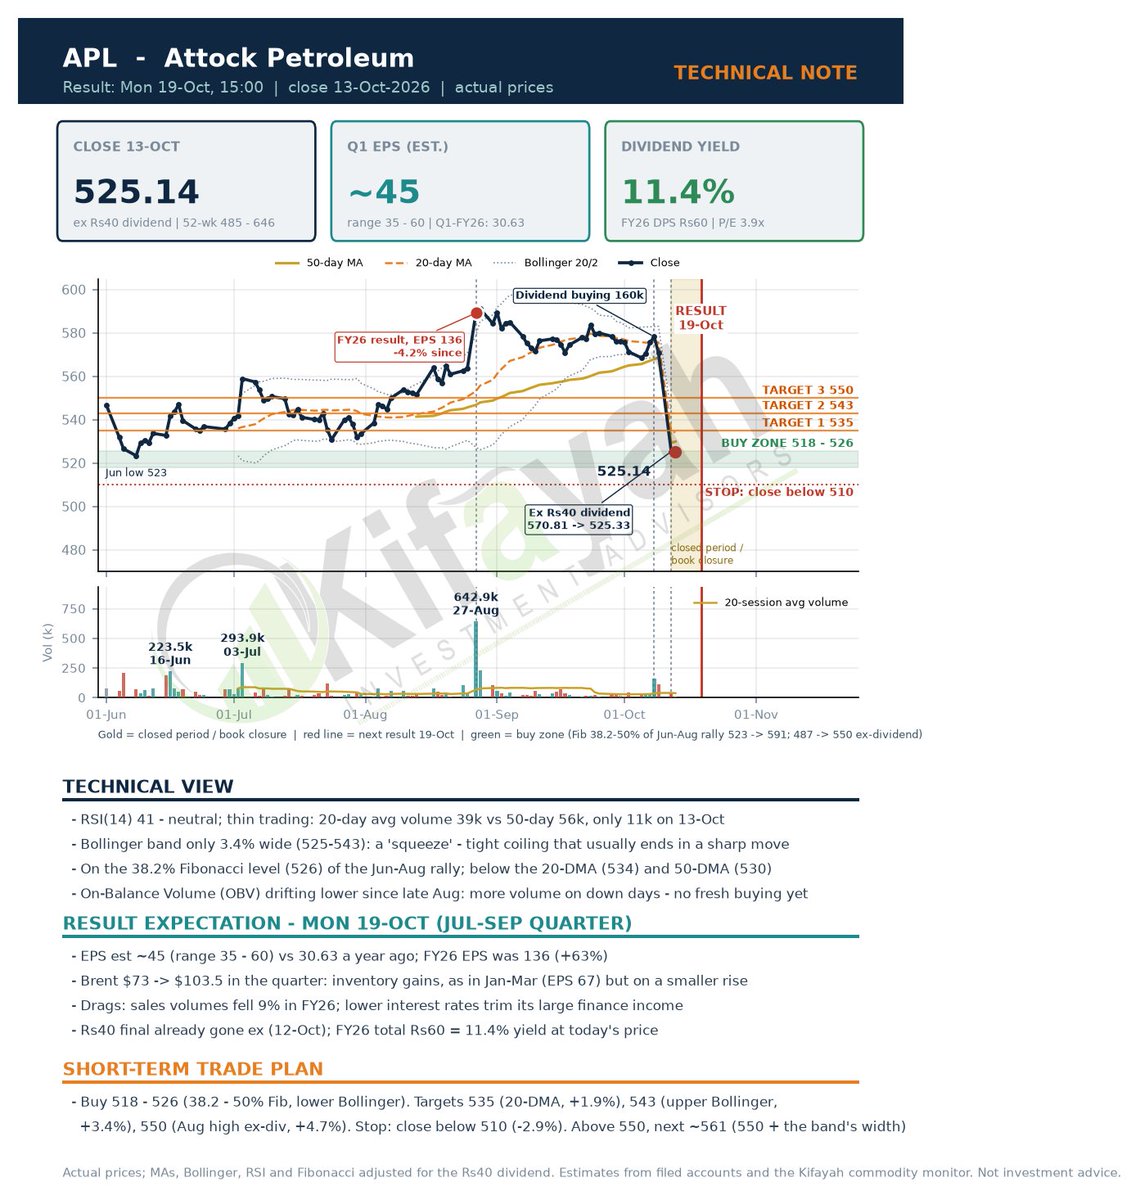
Kifayah Model Trading Portfolio, 20-Oct: –0.61% on Rs1mn vs KSE-100 –0.67%. Sold #AGP at 165.06 (–1.97%). #EFERT & #EPQL buy orders withdrawn – no result-day dip (EPQL vol 3.1x avg). Holding all #APL till its result. 25% invested. Not advice. #PSX
Refinery margins are easing but still healthy: crack spread ~56, –27% from Aug but +126% y/y, at the 2022 high. Key support 54; a break points to 47. #PRL#NRL#ATRL at record highs. Today's Q1 results should be strong. Stay realistic, avoid chasing. Not advice. #PSX
Kifayah Model Trading Portfolio, 19-Oct: –0.37% on Rs1mn vs KSE-100 –0.40% since our first call. #APL +1.9% leads ahead of today's result. New: #AGP at Rs168.38. Buy limits #EPQL 22.46 & #EFERT 187 carried forward. 35% invested. Not advice. #PSX
Model trading portfolio slot 9: #AGP at Rs168.38 (LDCP). Back above 20/50-DMA after a 31% slide; 1.30mn on 16-Oct (4.9x avg) as its buy-back ended (closed 18-Oct). OBS merger scheme awaits court sanction. Targets and stop limit to be given separately. Not advice. #PSX
Kifayah Model Trading Portfolio, 16-Oct: +0.01% on Rs1mn vs KSE-100 –0.54% since our first call. #MFL +8.5% on the corn-unit offer leads. Buy limits #EPQL 22.46 & #EFERT 187 not filled – carried forward. No action today; 30% invested. Not advice. #PSX
Model portfolio slot 7: #TREET at Rs23.99 (LDCP). Breakout held; above 20/50/100-DMA. Sep-qtr est: sales ~Rs4.0bn (+9%), margin ~41%; EPS ~0.80 vs 1.03 (one-off income last year). Result due late Oct. Targets and stop to follow. Not advice. #PSX
Kifayah Model Trading Portfolio, 15-Oct: value Rs996,329 (–0.37% on capital, 70% cash) vs KSE-100 –1.00% since our first call. New today: #TREET 23.99, #MFL 46.95. Buy limits kept: #EPQL 22.46, #EFERT 187. Not advice. #PSX
Model trading portfolio slot 8: #MFL (Matco Foods) at Rs46.95 (LDCP). Breakout from Sep base held; above 20/50/100-DMA. Sep-qtr est: sales ~Rs6.2bn, EPS ~0.80 vs 1.36. Result due late Oct. Targets and stop to follow. Not advice. #PSX
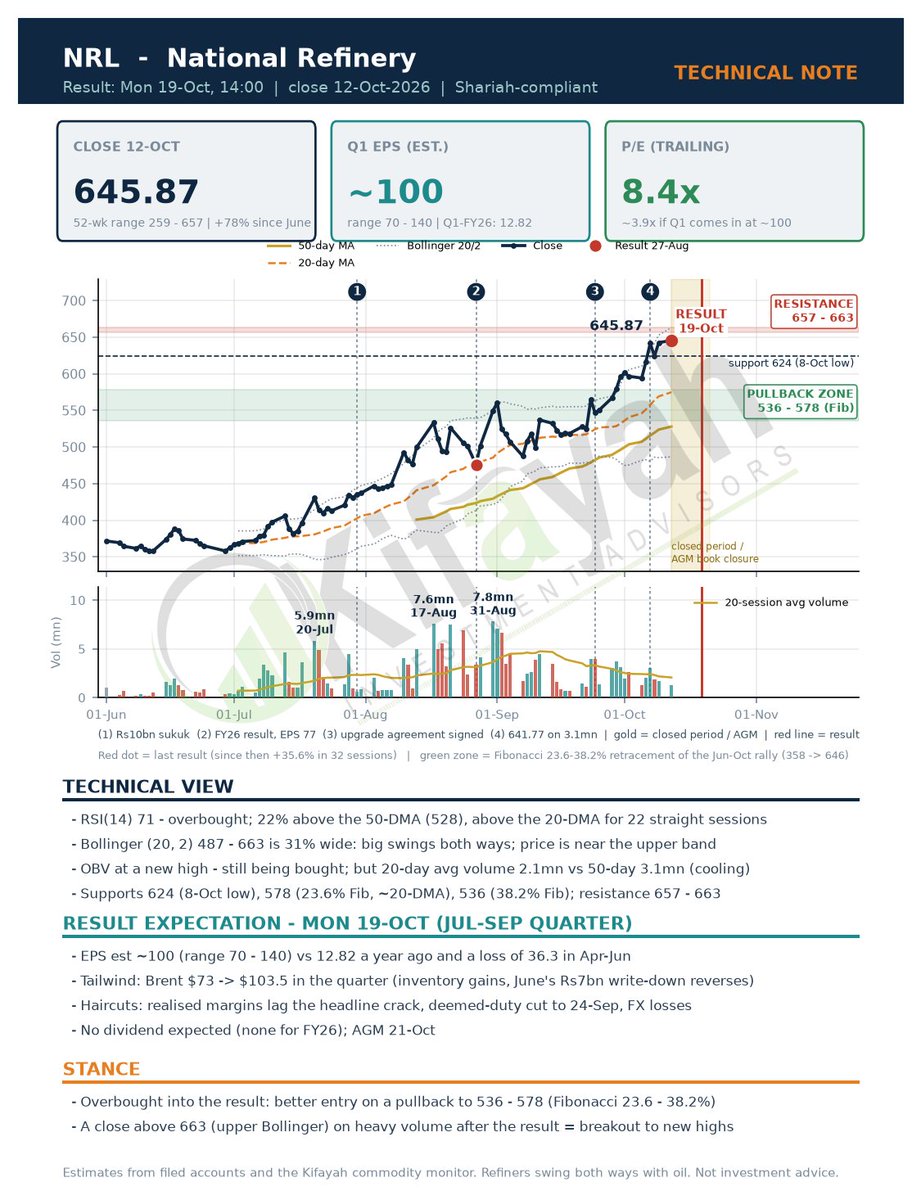
Not adding but still: #NRL reports Mon 19-Oct. Brent $73→$103.5 in Jul–Sep means inventory gains + June write-down reversing. My EPS est ~100 (70–140) vs 12.82. Stock +78% since June, RSI 71 overbought; better entry 536–578 (Fib), breakout above 663 with volume. Not advice. #PSX
Phantom portfolio order 4: #EFERT limit buy at Rs187 (~2% below close). The case is its 719kt urea stockpile being sold off: Q3 EPS est ~6.1 (vs 4.35), Dec qtr ~8.8, FY26 ~20.2 (~9.5x). Result Mon 19-Oct. Exit below 179.50. #PSX
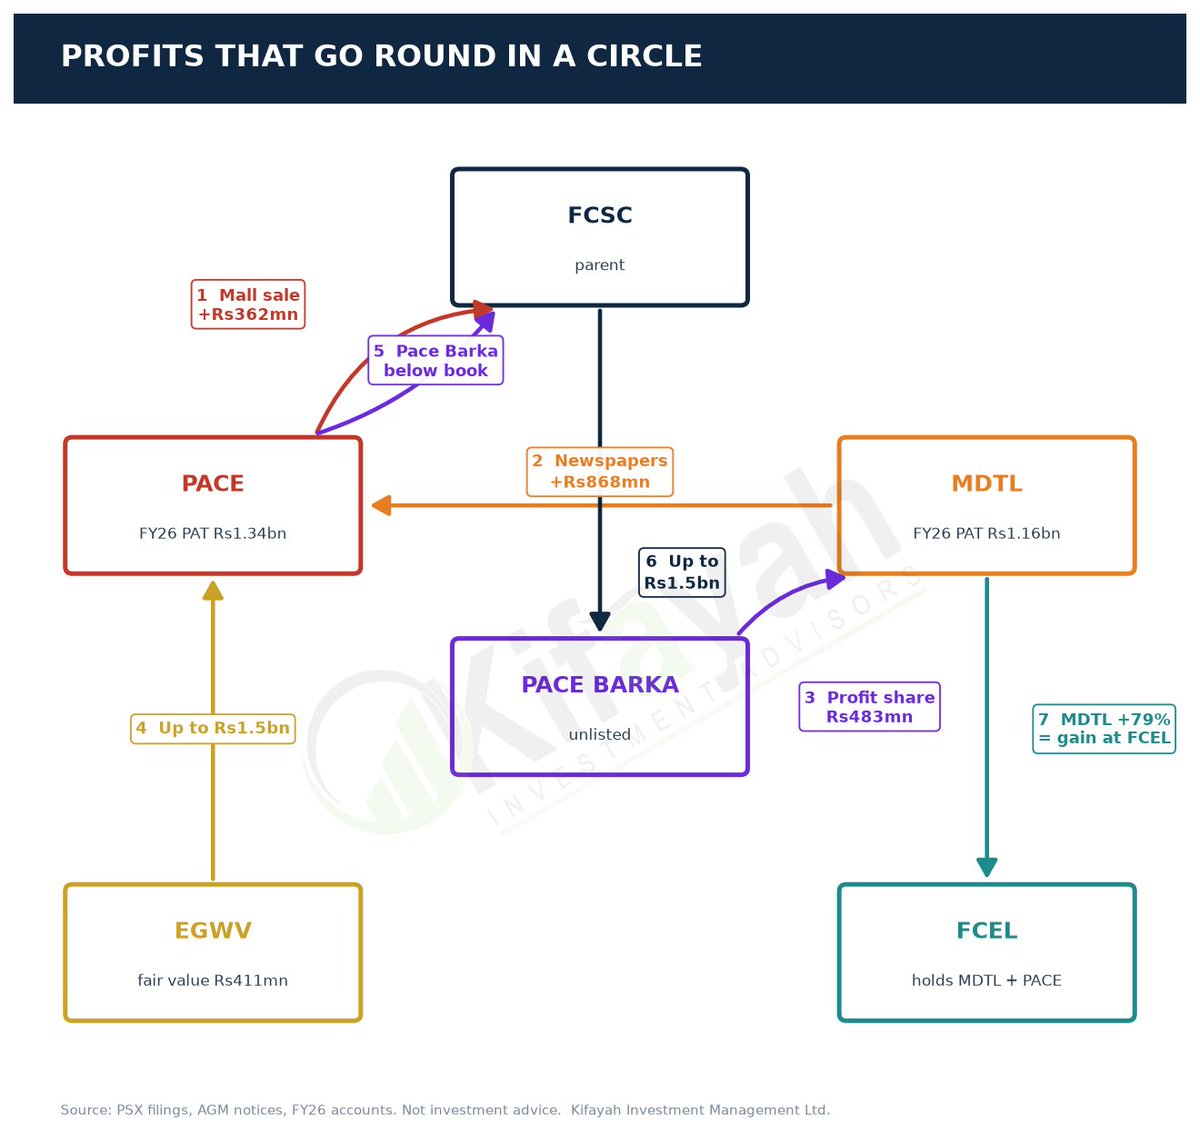
First Capital group (FCSC, PACE, MDTL, FCEL) reports Fri 16-Oct. FY26 profits look strong, but come mostly from deals inside the group: assets sold between companies, revaluations, marks on each other's shares. All circular. Minorities carry the risk. #PSX#Governance
Phantom portfolio: evaluating PSX names in order of result dates. LOTCHEM (Noventra) – result 15-Oct. Q3 EPS est ~0.62. Not buying: EPCL deal needs ~Rs27bn vs Rs20bn equity, authorised shares doubled – rights issue likely. Revisit once funding is clear. #PSX#LOTCHEM
Phantom portfolio pick #1: #TPLRF1. Cash-strapped – its high-end Mangroves prop. weren’t selling. Breakthrough venture with Saima Builders drew big bookings at Saturday’s launch. 20 projects lined up; price should close in on NAV. Bank selling may limit it so a trade(<1yr). #PSX