Filecrux reads every SEC filing, every day.
Hundreds of companies file paperwork. Most of it is nothing. We find the few that matter and write them in plain English.
Every report ends with a dated call. A later filing settles it. We publish the score either way.
$IDCC Is InterDigital's $193.4M Q3 beat repeatable when $36.2M of it was catch-up revenue?
🏢 InterDigital, a wireless and video patent licensor worth about $8.27B at $320.56 a share at 16:00 ET on October 28, 2026, posted Q3 revenue of $193.4M, up 17% from a year earlier and above its $154M to $158M outlook
⚠️ Catch-up revenue, which the company leaves out of its recurring run rate, was $36.2M against $17.7M a year earlier, about the same as the $35.4M by which revenue cleared the top of the outlook
📉 Smartphone licensing, the biggest line, fell 10% to $122.6M, while CE, IoT and auto nearly doubled to $55.7M and streaming added $15.0M
⚠️ The full-year revenue outlook of $813M to $819M counts only signed contracts and sits below 2025 revenue of $834M, with nine-month revenue at $659.0M against $675.8M a year ago
🏆 On the other side, the recurring run rate hit a record $628.9M, up 7%, Q3 diluted EPS rose to $2.34 from $1.93, and cash and investments of $1.12B at September 30 cover the $296.7M of 2027 convertible notes still outstanding
🤝 The new license with a top PC maker still has its terms to be set by binding arbitration, and the company says any Q4 deals or enforcement wins would add to the outlook
📅 Next: Management presents at the RBC Tech Conference on November 17, and holders can convert the 2027 notes in the quarter ending December 31, 2026
Source: GlobeNewswire release + SEC 8-K, Oct 29
$APG Can APi lift cash conversion from 84.2% so far this year to its 110% full-year target?
🏢 APi Group, a fire and life safety, security and elevator services company valued near $17.87B with its stock closing at $41.34 on October 28, 2026 (16:00 ET), grew Q3 net revenue 22.5% to $2,554M, or 15.7% organic
🚀 It raised 2026 guidance to $9,200–9,250M of net revenue (from $8,875–9,025M) and $1,235–1,255M of adjusted EBITDA (from $1,205–1,245M), which after $6,790M of nine-month revenue implies Q4 revenue of $2,410–2,460M, below Q3's level
⚠️ Adjusted free cash flow covered only 84.2% of adjusted net income over the first nine months ($468M of $556M), against the 110% full-year target, and Q3 conversion slipped to 109.6% from 142.5% a year ago
🏦 Cash fell to $373M at September 30 from $912M at December 31 after $1,356M of acquisitions and $252M of buybacks, while total debt rose to $3,574M from $2,759M
📉 Gross margin fell 120 basis points to 30.1% on project mix and rising material and fuel costs, so the 20 basis point rise in adjusted EBITDA margin to 13.7% came from SG&A leverage
📈 On the other side, Q3 adjusted EBITDA rose 24.6% to $350M and adjusted diluted EPS rose 22.0% to $0.50, and acquisitions added 6.9 points of Q3 revenue growth
📅 Next: Management held its results call October 29, 2026, and Q4 cash flow will show whether the 110% conversion target holds
Source: SEC 8-K and Business Wire release, Oct 29
$MPT Is tenant HSA's missed September rent the start of a deeper cut to MPT's $0.11 normalized FFO?
📉 Medical Properties Trust, a hospital landlord with about $14.4B of assets, reported Q3 2026 normalized FFO of $0.11 a share ($64M), down from $0.15 in Q2 and $0.13 ($77M) a year earlier
⚠️ Tenant Healthcare Systems of America (HSA), 6.2% of Q3 revenue, skipped September rent, cutting NFFO by two cents, and hired Ovation Healthcare to fix its billing and collections
⚠️ HSA is the second-largest operator by assets at $1.27B, or 8.8% of the total, and the revenue MPT booked from it fell to $15.5M in Q3 from $23.3M in Q2
⚠️ MPT's market value is about $1.64B at the $2.75 close (16:00 ET, October 28, 2026); HSA brought in 6.2% of Q3 revenue, and MPT says its hospitals are underwritten to attract a replacement operator if needed
⚠️ Q3 normalized FFO of $0.11 covers the $0.09 quarterly dividend paid in October with only two cents to spare, about the same size as the HSA rent hit
🧾 Q3 net income of $0.34 a share is not a run rate, because it includes a $158M gain on asset sales and a $70M refinancing gain
📈 On the other side, the Utah and Idaho hospital sales plus other deals brought in about $680M for debt repayment, and MPT still expects 2027 cash rent above $1.0B with conservative HSA assumptions already built in
📅 Next: MPT takes analyst questions on its webcast starting 11:00 a.m. Eastern Time today, and the key question is whether HSA has paid October rent
Source: SEC 8-K + Business Wire release, Oct 29
$FSS Will refuse-truck delivery delays that cut the 2026 sales ceiling to $2.64B outweigh a 33% jump in orders?
🏢 Federal Signal, which makes equipment that moves material, cleans infrastructure and protects communities for municipal and industrial customers, is worth about $6.93B at the $113.45 close at 16:00 ET on October 28, 2026, and its Q3 sales rose 18% to $656M
⚠️ The company narrowed its 2026 net sales outlook to $2.61B–$2.64B from $2.58B–$2.67B, citing anticipated delays in deliveries of third-party refuse trucks, which takes $30M off the top of the range while the midpoint stays put
📉 Q3 orders of $620M came in below Q3 sales of $656M, and backlog was $967M at September 30 against $992M a year earlier, so the 33% order jump has not yet grown the book
🚀 The adjusted EPS outlook rose to $5.20–$5.32 from $5.12–$5.30, and after $3.96 in the first nine months it implies about $1.24–$1.36 in Q4 against $1.34 in Q3, putting the stock at about 21–22 times this year's guided earnings
📈 On the other side, the adjusted EPS outlook rose to $5.20–$5.32 from $5.12–$5.30, operating cash flow reached $306M in nine months, up 94%, debt fell to $420M from $565M at year-end with $74M of cash and $1.04B of credit availability, and Environmental Solutions orders rose 43%
📅 Management's earnings call this morning is the first chance to ask how large the refuse-truck delays are and which quarter they push sales into
📅 Next: Q3 earnings call today, October 29, 2026, 10:00 a.m. ET
Source: PR Newswire release, Oct 29
$AMP Can Ameriprise's 22% EPS jump hold up while its fund arm loses $9.3B in net outflows?
🏢 Ameriprise Financial, the wealth adviser and Columbia Threadneedle fund manager worth about $43.27B at $489.8 a share at 16:00 ET on October 28, 2026, said Q3 2026 adjusted operating EPS excluding unlocking rose 22% to $12.07
📉 Asset management lost a net $9.3B in the quarter, almost triple the $3.4B a year ago and about 1.3% of its $743B in managed and advised assets
📉 Wealth management swung to $8.5B of total client net outflows, against $3.4B of inflows a year ago
📈 Buybacks did much of the per-share work, since adjusted operating earnings excluding unlocking rose 14% to $1.103B while diluted shares fell to 91.4M from 97.8M
⚠️ Total equity dropped to $5.11B at September 30 from $6.37B at June 30 as accumulated other comprehensive losses widened to $2.64B, and debt to capital rose to 39.4% from 37.5%
💰 Ameriprise returned $1.026B to holders in Q3, and its already-public $5.5B buyback authorization through September 30, 2028 equals about 13% of the $43.27B market value at the October 28 close
📈 Against the outflows, asset management pretax earnings rose 18% to $308M at a 45.7% net margin, and wealth inflows excluding Comerica rose 56% to $5.3B, though total wealth client flows were $8.5B of net outflows with Comerica
📅 Next: The 10-Q for the period ended September 30, 2026 may revise asset values, and about $32B of Huntington assets are due to move over through mid-2027
Source: SEC 8-K (Q3 2026 earnings release), Oct 29
$INDV Does Indivior's $95M sale of its SUBUTEX tablet business in France and Germany matter with the Supernus merger days away?
🤝 Indivior, which makes the opioid-addiction injection SUBLOCADE and whose October 29 Q3 release showed revenue up 13% to $356M, says in its 10-Q that on October 19, 2026 it agreed to sell its SUBUTEX tablet business in France and Germany for $95M
🏢 The $95M equals about 2.3% of Indivior's roughly $4.10B market value at $34.77 at 16:00 ET on October 28, 2026, and about 29% of the $332M of cash and investments it held at September 30
🏦 Indivior collects 90% of the price, about $85.5M, at a closing it expects later in 2026, and the rest only after regulators approve the transfer of marketing authorizations, which it expects in the first half of 2027
🏦 Separately, a $1,000M special dividend ($8.13 a share, record date October 30, 2026) is to be paid after the merger closes, funded by a $650M Citibank term loan plus the combined company's cash, not the SUBUTEX sale
⚠️ Against that, the filing gives no profit or gain figure for the business, so the deal's effect on earnings cannot be worked out, though the business made less than 4% of 2025 net revenue and Indivior expects a smaller share in 2026
📅 Next: Indivior expects the Supernus merger to close on or about November 2, 2026, and the SUBUTEX sale to close later in 2026, with 10% of the price due only after regulatory approval expected in the first half of 2027
Source: SEC 10-Q, Oct 29 + Q3 release (8-K), Oct 29
$NSP Can Insperity's 210% EBITDA rebound cover a dividend that ran $69M against $36M of nine-month profit?
🏢 Insperity, an outsourced HR and payroll provider (a PEO) for small and midsize businesses worth about $1.97B at $51.65 at 16:00 ET on October 28, 2026, reported that Q3 adjusted EBITDA rose 210% to $31M and its net loss shrank to $1M from $20M
⚠️ In the first nine months of 2026 it paid $69M in dividends and $10M in buybacks against $36M of GAAP net income, and credit-facility borrowings stood at $420M at September 30, up from $369M of long-term debt at December 31
⚠️ Even the new full-year guide for $32M to $45M of GAAP net income stays below the $69M of dividends already paid, so covering the payout rests on adjusted measures that add back $49M of non-cash stock pay
📈 The rebound came from pricing, with gross profit per worksite employee up 8% to $225 and operating expenses down 5% to $209M, even as average paid worksite employees fell 2% to 307,265
🏢 Full-year 2026 adjusted EPS guidance of $1.93 to $2.28 puts the $51.65 close at about 24.5 times the roughly $2.11 midpoint
📈 Against $69M of nine-month dividends on $36M of profit, adjusted cash rose to $119M from $57M at year-end and 2026 adjusted EBITDA guidance of $194M to $214M, which lenders use for leverage, is about half the $420M on its credit line
📅 Next: Q4 2026 guidance calls for adjusted EPS of $0.07 to $0.42 and GAAP net income of $(6)M to $8M; the release gives no date for the Q4 report
Source: SEC 8-K and Q3 release, Oct 29
$MA Does Mastercard's 22% EPS jump hold up when its nine-month operating cash flow fell about 6%?
🏢 Mastercard, the card payments network worth about $538.29B at $610.31 a share at 16:00 ET on October 28, 2026, reported Q3 net income up 18% to $4.6B and diluted EPS up 22% to $5.28 on net revenue up 14% to $9.8B
📉 Its cash from operations for the first nine months of 2026 fell to $11,859M from $12,646M a year earlier, about 6% lower, while nine-month net income rose 18% to $12.9B
⚠️ A $4,688M outflow into prepaid expenses, up from $2,939M in 2025, more than explains the drop, partly offset by accrued expenses adding $1,660M vs. $658M; amortization of customer incentives rose to $2,030M from $1,526M and Q3 payment network rebates and incentives rose 18%
🏦 Nine-month buybacks of $11,893M used slightly more than all of that operating cash, and long-term debt rose to $22.19B at September 30 from $18.25B at year-end, lifting Q3 interest expense to $250M from $186M
⚠️ EPS grew faster than profit because diluted shares fell to 876M from 905M and the Q3 tax rate dropped to 19.4% from 21.5% on discrete tax benefits, which may not repeat every quarter
📈 On the other side, Q3 operating income rose 16% to $5.9B, the operating margin widened to 59.8% from 58.8% and value-added services revenue grew 19%, so the core business is still growing at a double-digit pace
📅 Next: Management hosts its Q3 call at 9:00 a.m. ET today, October 29, 2026, and the release itself gives no outlook
Source: SEC 8-K, Oct 29 (Q3 2026 earnings release)
$OSK Is Oshkosh's $1.50–$2.50 cut to 2026 EPS guidance just a short-term fire-truck production glitch?
🏢 Oshkosh, the maker of JLG lifts, Pierce fire trucks and Oshkosh Defense vehicles, was worth about $8.60B at $137.93 a share at 16:00 ET on October 28, 2026, and now expects 2026 adjusted EPS of $8.50 to $9.50, down $1.50 to $2.50 from its most recent guidance
✂️ It also cut 2026 sales guidance by $0.2B to about $11.0B because it is building fewer fire trucks and NGDV postal delivery vehicles, which more than offsets higher volume at its JLG lift (Access) business
📉 Q3 adjusted EPS fell to $2.41 from $3.20 a year earlier, as Vocational operating income dropped 38.2% and fire-truck sales slipped to $362.1M from $405.5M
⚠️ Nine-month adjusted EPS of $6.12 leaves $2.38 to $3.38 for Q4 in the new range; its low end reflects the possibility of no 2026 NGDV order, costing up to $0.50 a share
📈 On the other side, Access sales rose 20.7% to $1.34B, total backlog grew to $15.1B from $13.7B a year earlier, and the CEO calls the fire-truck slowdown a near-term problem with its causes already identified
💰 Nine-month operating cash flow rose to $533.2M from $183.3M, against $221.3M of buybacks and $106.2M of dividends paid before the newly declared $0.57 payout; $558.0M of cash covers $500.4M of debt due within a year
📅 Next: The $0.57 dividend is payable November 30, 2026 to holders of record November 16, 2026; watch for an NGDV order and fire-truck output in the Q4 report
Source: SEC 8-K and Q3 release, Oct 29, 2026
$ITGR Does Integer's 50% drop in Q3 operating income put any doubt on its pending sale to KKR?
🏢 Integer, a large contract maker of medical devices whose stockholders approved a merger with a KKR affiliate on October 21, 2026 per that day's 8-K, reported Q3 GAAP operating income of $28M, down 50%, on sales down 3.9% to $450M
🏢 Integer's market value is about $4.30B at $126.55 a share at 16:00 ET on October 28, 2026
📉 Adjusted EPS fell 25% to $1.34 and adjusted EBITDA fell 17% to $88M for the quarter ended October 2, so the drop is not just one-off charges
📉 Gross margin worked from the release slid to about 22.6% from 27.0% a year earlier, because cost of sales rose to $348.1M while sales fell
📉 Cardio & Vascular, the largest line, fell 5% to $263M on a previously flagged hit from two new Electrophysiology products
✅ On the other side, antitrust early termination came on September 29 and the stockholder vote is done; if the deal closes, holders receive $127 a share in cash, about $0.45 above the $126.55 close at 16:00 ET on October 28, 2026
⚠️ The release still lists Parent's financing and a possible termination among the risks, though the company said at signing the deal is not subject to any financing contingency; it gives no outlook and holds no call
📅 Next: Integer expects the deal to close by the end of 2026, subject to remaining closing conditions including required regulatory approvals
Source: GlobeNewswire release Oct 29 + SEC 8-K Oct 21
$HTO Follow-up: Will H2O America's $325M equity unit sale deepen the share-count drag on its EPS?
🏢 H2O America, a water and wastewater utility serving over 1.7 million people in four states, has launched a proposed $325M equity unit offering, subject to market and other conditions, about 11% of its roughly $2.99B market value at $61.8 at 16:00 ET on October 28, 2026
🏦 Each $50 unit pairs a contract to buy common stock with a slice of senior notes due 2031, and the company expects to issue the shares on or about November 1, 2029
⚠️ Until the shares are issued on or about November 1, 2029, the contracts count in diluted EPS under the treasury stock method, on top of the share-count drag that the October 26 Q3 release blamed on 2025 at-the-market sales and the early-March 2026 stock issuance
⚠️ An underwriter option for 975,000 more units, open for 13 days after first issuance, would lift the deal to $373.75M, about 12.5% of the market value at $61.8 at 16:00 ET on October 28, 2026
🤝 In return, the money can go to acquisitions, capital spending or debt repayment, and the company says part of it will satisfy a portion of its future equity needs to refinance debt maturing in 2029; the cash arrives now alongside senior notes due 2031, while the new shares are not expected until on or about November 1, 2029
📅 Next: The company expects the units to start trading on Nasdaq within 30 days of issuance, subject to listing approval
Source: GlobeNewswire release, Oct 29 + SEC 8-K, Oct 26
$SIRI Will SiriusXM's raised $1.40B free cash flow guide turn into much bigger buybacks in 2027?
🏢 SiriusXM, the satellite radio and Pandora audio company worth about $9.21B at $27.32 a share at 16:00 ET on October 28, 2026, raised its 2026 guidance by $25M each, to about $8.55B revenue, $2.65B adjusted EBITDA and $1.40B free cash flow
💰 The company says it has reached its long-term leverage target, with net debt at 3.3x adjusted EBITDA at the end of Q3, and the CFO expects to meaningfully accelerate share repurchases in 2027
📈 Q3 free cash flow rose 14% to $293M, and nine-month free cash flow of $1,057M is up 48% from $715M, so Q4 needs about $343M to reach the $1.40B guide
💰 The $1.40B guide equals about 15% of the $9.21B market value at 16:00 ET on October 28, 2026, yet Q3 returned only $124M through $91M of dividends and $33M of buybacks; the CFO ties faster 2027 buybacks to a more efficient operating model and declining satellite capex
⚠️ Debt still totals about $9.3B, or $1,250M due within a year plus $8,066M long-term, against $210M of cash, roughly matching that same October 28 market value
📉 The gains come from cost cuts, favorable working capital, lower interest and lower capex, not growth, as Q3 revenue was flat at $2.15B and diluted EPS fell 7% to $0.78 on convertible-note accounting even as net income rose 7% to $317M
📅 Next: The Q3 10-Q will carry segment detail; the release gives no size for the 2027 buyback, so watch for one
Source: SEC 8-K, Oct 29, 2026
$BDC Can 11% organic growth and a $100M data center deal carry Belden's $3.03B debt load?
🏢 Belden, a networking-gear maker worth about $4.17B at $106.66 a share at 16:00 ET on October 28, 2026, posted record Q3 revenue of $966M, up 38%: 24 points came from acquisitions, 3 from copper pricing and 11% was organic growth
🏦 Long-term debt rose to $3.03B on September 27 from $1.29B at the end of 2025 to pay for the roughly $1.9B Ruckus wireless deal, against $380.7M of cash
🔥 Net interest expense jumped to $41.8M from $11.6M a year ago, and with $100M of non-cash Ruckus charges it left a Q3 GAAP net loss of $11M, or ($0.29) a share
✅ The $100M of fiber assemblies Belden agreed to supply a major US data center customer in 2027 is about 2.6% of revenue at the Q3 pace, yet it lifts the company's data center growth outlook to more than 50% next year
📈 Adjusted EPS rose 15% to $2.26 and orders topped $1B for the first time, but Q4 guidance of $2.20-$2.35 in adjusted EPS is roughly flat with Q3
💰 The case for holders is that the loss is mostly non-cash: Q3 free cash flow rose to $81.9M from $65.4M, and adjusted EBITDA of $171M covered interest about four times
📅 Next: Earnings call today at 8:30 am ET, and Q4 2026 guidance calls for $960M-$980M of revenue
Source: SEC 8-K + earnings release, Oct 29, 2026
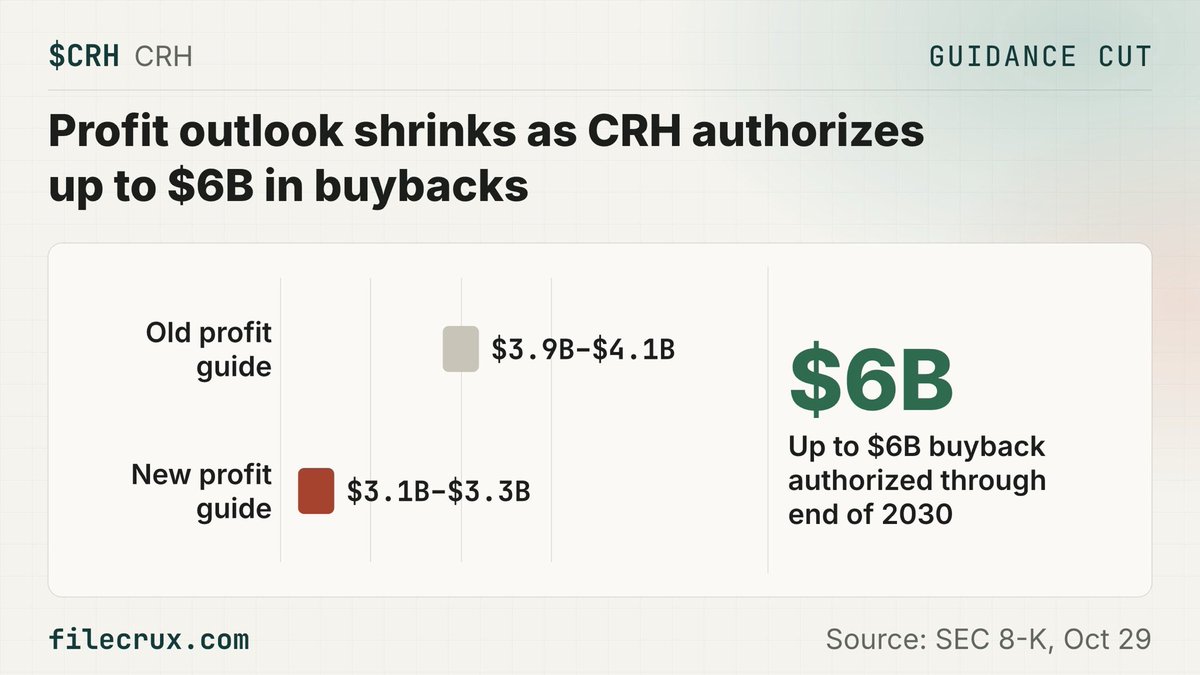
$CRH Does an up-to-$6B buyback offset CRH cutting its 2026 net income guide by 20%, a cut that includes Arcosa deal costs?
✂️ CRH, an S&P 500 building materials maker, cut its 2026 net income guide to $3.1B-$3.3B from $3.9B-$4.1B on cost inflation, weak housing and Arcosa's early close, including Arcosa's fourth-quarter profit and costs
📉 At $86.54 (16:00 ET close, October 28, 2026), or about $57.6B in market value, the stock sits near 18 times the new diluted EPS guide of 4.63-4.85 dollars, up from about 15 times the old range of 5.60-6.05 dollars
🧾 Adjusted EBITDA's fall to $7.9B from $8.3B is half the $0.8B midpoint net income cut, and the rest is a non-cash $0.2B impairment booked through September, $0.2B of deal costs and $0.1B each of interest and other costs, less $0.2B of tax
💰 Buybacks of up to $6B through 2030, timed and sized at management's discretion, are about 10% of the market value at the Oct. 28, 2026 close, and the 10-Q says none were made yet
⚠️ Net debt was $15.0B on September 30, and the $8.5B Arcosa deal that closed October 23 was funded with a term loan, a bridge facility and cash, so buybacks compete with paying down that debt
📈 In return, CRH targets about $400M a year of run-rate benefits from its Velocity program by end of 2028, for about $400M of one-off costs, and calls its 2027 outlook positive across key end-markets
📅 Next: The quarterly dividend of $0.39 a share, up 5%, is paid December 9, 2026 to holders registered November 13, 2026
Source: SEC 8-K, Oct 29
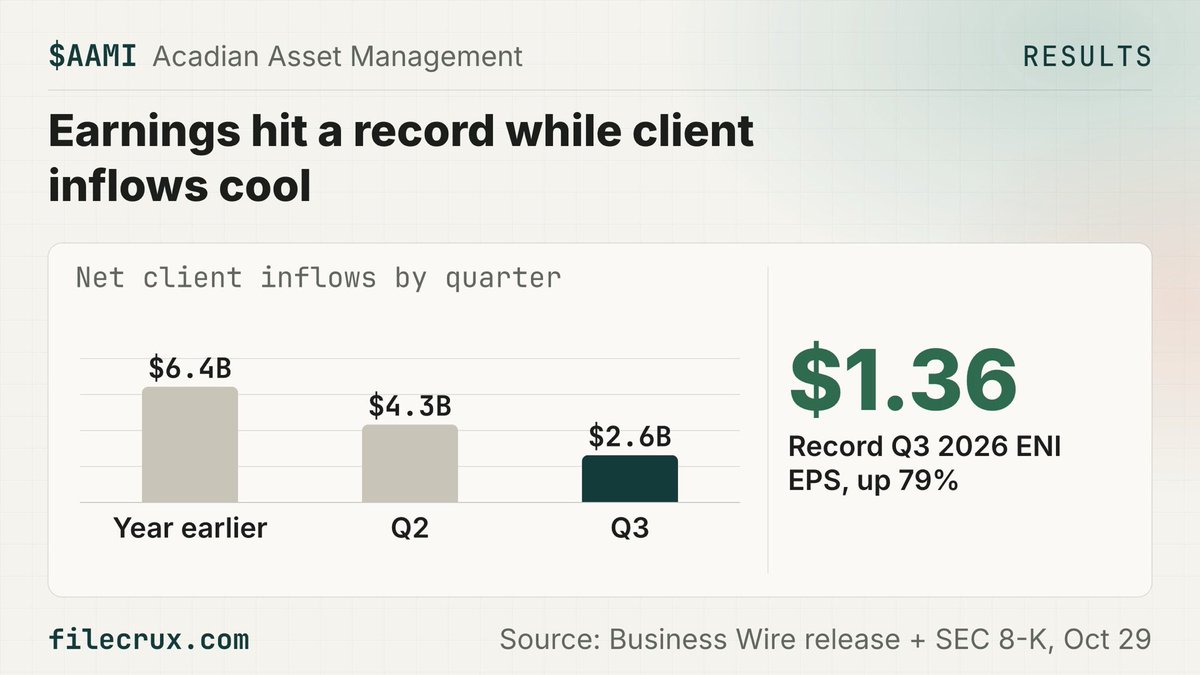
$AAMI Can Acadian's record $1.36 adjusted EPS keep rising as quarterly net inflows slow to $2.6B?
🏢 Acadian Asset Management, a Boston quant manager running $239.6B for institutions, posted Q3 2026 revenue of $191.2M, up 32.6% from a year earlier, and GAAP diluted EPS of $1.00 against $0.42
🏆 ENI EPS, the company's adjusted measure, hit a record $1.36, up 79%, as the ENI operating margin widened 9.4 points to 42.6%
📉 Net client inflows slowed to $2.6B, a 4% annualized growth rate, from $4.3B in Q2 and $6.4B a year earlier, so $4.3B of market gains did most of the quarter's AUM lift
⚠️ Against Q2 the pace is flatter: revenue rose 3.3% and ENI EPS 2.3% from $1.33, while the fee rate held at 32 basis points, down from 35 a year ago
🏢 At the $91.27 close at 16:00 ET on October 28, 2026, the market value is about $3.24B, about 16.8 times Q3 economic net income of $48.3M run for four quarters
📈 On the other side, 96% of strategies by revenue beat benchmarks over 3, 5 and 10 years, year-to-date inflows total $28.3B, and $150.0M of cash against a $200.0M term loan leaves net leverage at 0.2x
⚠️ Employees share the upside, as key-employee distributions rose 119% to $11.4M, and the company gives no 2026 earnings guidance, only ratios of 34%-38% for variable pay and 12%-14% for distributions
📅 Next: Management walks through the quarter on a call set for October 29, 2026, and the $0.10 dividend is payable December 23, 2026 to holders of record December 11, 2026
Source: Business Wire release + SEC 8-K, Oct 29
$ICE Can ICE's 18% EPS jump hold when trading revenue, up 23%, drove about three-quarters of the growth?
🏢 Intercontinental Exchange, owner of the New York Stock Exchange and big energy futures markets, grew Q3 2026 net revenue 15% to $2,765M and adjusted diluted EPS 18% to $2.02, against a market value of about $87.56B at $155.96 a share at 16:00 ET on October 28, 2026
📈 Transaction revenue, which rises and falls with trading volumes, jumped 23% to $1,400M, and by my arithmetic it supplied about $264M of the $354M year-over-year revenue gain
📈 Energy trading revenue rose 25% to $603M and financial futures revenue rose 37% to $190M, within exchange segment revenue of $1,542M, up 22%
💰 Buybacks of $1.6B through September cut diluted shares to 563M from 574M a year earlier, which lifted per-share growth, and ICE guides Q4 to 558 to 563M shares
⚠️ Debt stood at $23.3B against $936M of unrestricted cash on September 30, and the MarketAxess purchase is being funded partly by $3.73B of notes sold in August and a $2.0B term loan
📈 Recurring revenue, the steadier subscription-like half, still rose 7% to $1,365M, and ICE now guides 2026 recurring revenue growth of 9% at exchanges and 8% in fixed income and data
📅 ICE now expects MarketAxess to close in the first quarter of 2027, ahead of its July first-half timeline, after US antitrust clearance on October 21, 2026
📅 Next: Q4 2026 earnings call on February 4th, 2027 at 8:30 a.m. ET
Source: ICE Q3 release in SEC 8-K, Oct 29
$AGCO Is AGCO's balance sheet stretched after cash fell to $415.1M while it spent $403.7M buying back stock?
🏢 AGCO, the Fendt and Massey Ferguson tractor maker worth $7.15B at $102.16 (16:00 ET, October 28, 2026), earned Q3 adjusted EPS of $1.05 vs $1.35 a year ago and targets about $5.50 for 2026, putting the stock at 18.6 times that target
🔥 Cash fell to $415.1M from $861.8M in nine months as operations used $218.4M and buybacks $403.7M, partly offset by $344.6M borrowed and $188.4M of stake sales
🏦 Borrowings due within one year rose to $536.1M from $117.7M while long-term debt fell to $2.14B from $2.32B, so total debt rose about $236M and short-term debt is now larger than cash
⚠️ Reaching about $5.50 requires roughly $2.08 of adjusted EPS in Q4 after $3.42 through nine months, nearly double Q3's $1.05, on implied Q4 sales of about $2.6B to $2.8B from the $9.8B to $10.0B full-year guide
📉 Europe/Middle East, the largest region at $1.31B of Q3 sales, fell 19.1% and its operating income dropped $115.1M, while inventories rose to $3.0B from $2.71B at year-end, using $302.4M of cash in nine months
📈 On the other side, buybacks cut Q3 diluted shares to 69.5M from 74.7M and North America sales rose 34.8%, though about $13.0M of its $13.8M Q3 operating income was IEEPA tariff refunds AGCO may have to repay
📅 Next: Management takes questions on its October 29 results call, where Q4 production plans and the cash and debt outlook are the points to watch
Source: PR Newswire release, Oct 29
$PHIN Does PHINIA's raised $500M–$520M EBITDA guide show growth beyond the stoba deal it just closed?
🏢 PHINIA, a Michigan maker of engine fuel systems and aftermarket parts worth about $2.11B at $57.68 (16:00 ET, October 28, 2026), posted Q3 2026 adjusted EPS of $1.83, up from $1.59, on sales of $912M, up 0.4%
🚀 PHINIA raised its full-year adjusted EBITDA guide to $500M–$520M from $485M–$515M, but the new range includes the fourth-quarter contribution of stoba Group, a deal that closed October 1, and the release does not say how much stoba adds
⚠️ After $380M in the first nine months, the range implies a Q4 of $120–140M against $116M a year earlier, so the midpoint rose only $10M even with an acquired business added
💰 Buybacks did much of the EPS work, since $65M of Q3 repurchases helped cut diluted shares to 37.1M from 39.6M, so adjusted net earnings rose about 8% to $68M while adjusted EPS rose 15%
📉 Adjusted free cash flow fell to $73M from $104M on withholding tax payments tied to cash repatriation and higher receivables, and net debt climbed to $657M from $611M at the end of 2025
📈 On the other side, core sales rose $21M once tariff refund swings are stripped out, Aftermarket Solutions sales grew 4.2% to $351M, and the low end of the free cash flow guide rose to $220M from $210M
📅 Next: Conference call to review Q3 2026 results at 8:30 a.m. ET on October 29, 2026
Source: SEC 8-K and earnings release, Oct 29, 2026
$SAIA Does a $250M buyback make up for Saia's operating ratio of 87.6%, worse than last year's GAAP 85.9% and flat only against the adjusted 87.6%, despite 17% revenue growth?
🏢 Saia, a Georgia less-than-truckload freight carrier with 219 terminals, posted record Q3 2026 revenue of $982.5M, up 17.0%, and authorized a $250M buyback, about 2.9% of its roughly $8.66B market value at the $324.62 close at 16:00 ET on October 28, 2026
⚠️ Diluted EPS rose 21% to $3.41 from an adjusted $2.81, but the operating ratio, costs as a share of revenue, was 87.6%, the same as Q3 2025's adjusted 87.6%
⚠️ Fuel surcharges did much of the lifting, as LTL revenue per shipment rose 16.1% in all but only 5.8% without fuel, while revenue per hundredweight without fuel fell 2.2% because shipments got 8.1% heavier (1,465 vs 1,355 lbs)
📈 Against the July 30 call's guide of about 100 basis points of worsening from Q2's 86.9%, the 87.6% ratio came in roughly 30 basis points better
💰 Nine-month free cash flow of $244.9M, up from $11.6M a year earlier, backs the plan, and at $324.62 the full $250M would retire about 770,000 shares
⚠️ The $250M exceeds the $202.5M of cash on hand at September 30, the program obligates no purchases, and about $114M of the roughly $350M 2026 net capex plan is still to be spent in Q4
📅 Next: Conference call today, Oct. 29, 2026, at 10:00 a.m. Eastern Time; watch Q4 margin commentary and how fast buybacks start
Source: GlobeNewswire release, Oct 29 + SEC 8-K, Aug 5