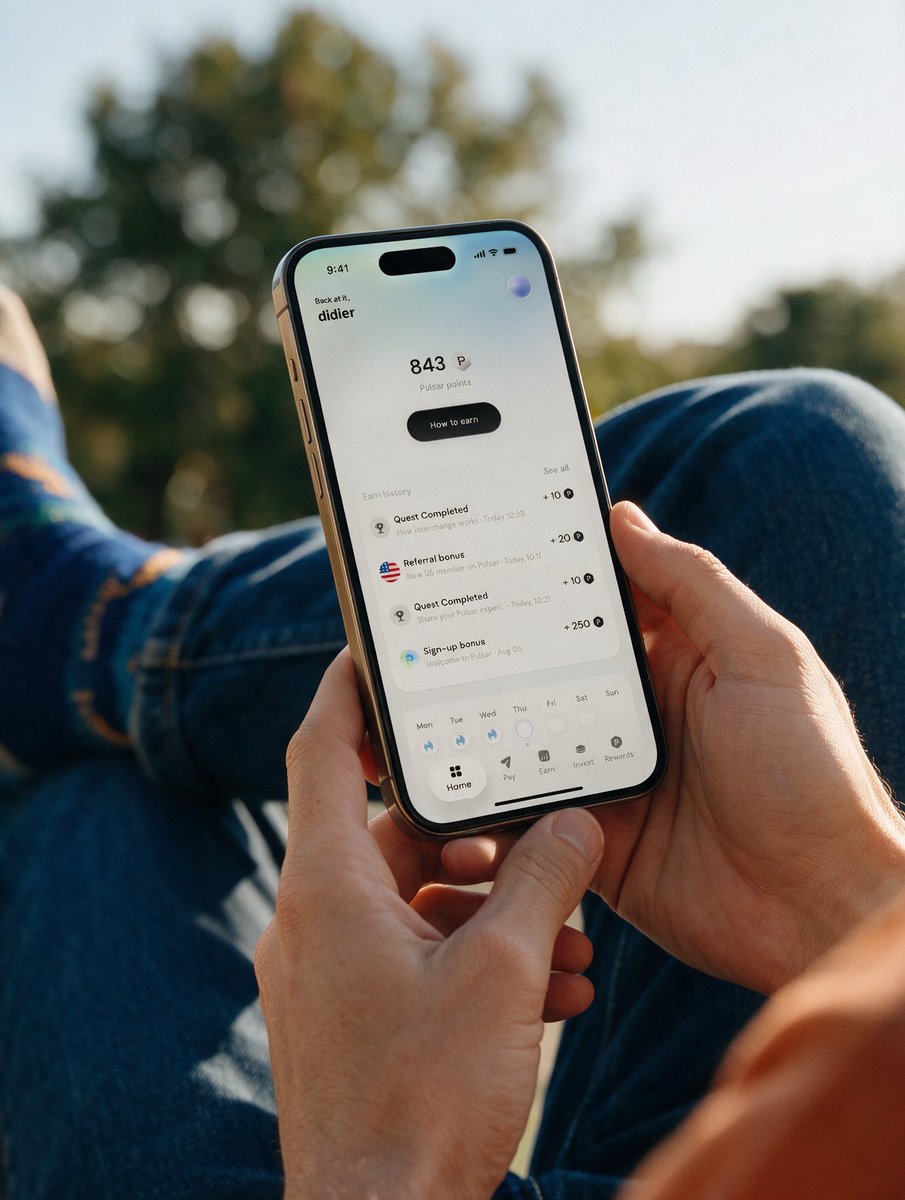
Your next Points could come from being Pro 👀
Earn your first month’s subscription back in Points and enjoy higher card rewards.
Get Pulsar Pro to have all benefits.
@RadziSlAU@KASTxyz 2% USD cashback on the first $10k plus uncapped points sounds strong on paper.
The interesting part is that some accounts receive it without ever seeing a payment screen2
,000+ US stocks are now available to EEA users in the Kraken app 🇪🇺 Invest in stocks, tokenized equities, and crypto all in one platform. Explore stocks 📷 https://t.co/7uxSr6JKv8
Memecoins I'm keeping an eye on, besides $CASHCAT : • $CATSTR• $FCAT• $NASDANQ A few quick thoughts: $CATSTR - I view this as a proxy play for CASHCAT to farm extraCASHCAT yield $FCAT - Just an influencer meme token on my radar.
@votesa
transferred 33.3% of the supply to
Until now Revolut operated in France mainly through passporting.
The full banking licence removes the regulatory limit on regulated savings and local credit.
The real test is how many of its existing users will actually switch their primary account.2
One clearer way to look at the @Revolut French licence:
Until now they could offer payments and basic accounts through passporting.
They could not fully compete on regulated savings, local credit, or deposit perception.
The licence removes that ceiling.
The hard part is no longer regulatory.
It is whether tens of millions of users who treat Revolut as a secondary app will make it their main bank.
That conversion rate will matter more than the licence itself.
Stablecoin cards just hit $12B+ annualized run-rate 👇
Most people still have no idea how they actually work.
You load USDT or USDC
Tap anywhere Visa / Mastercard is accepted
Merchant gets normal fiat
Simple flow:
- Send stables to the card (any major chain)
- Balance sits as pure $1
- You spend → exact amount deducted
- Issuer converts to fiat and settles in the background
Seller never sees crypto.
You never feel volatility.
Why this is exploding in 2026:
- Zero price risk
- Usually no taxable event on spend
- Yield on idle balances
- Full Apple Pay / Google Pay support worldwide
@KASTxyz and @ether_fi and @RedotPay are leading the charge right now.
Quick one:
USDT or USDC for top-ups?
Which card are you actually using?
XPlace Platinum looks expensive, but the math is actually pretty clear.
It only makes sense if you already spend a lot on AI, travel, and rides.
That’s where the boosted rewards can pay back the $999 fee fast.
For small everyday spend, though, it is probably too much.
The base rate is decent, but not enough to justify the card on its own.
So my takeaway is simple:
this is not a card for everyone.
It is a premium spend layer for heavy users who will actually use the boosted categories.
If that is you, the card can work.
If not, it is overkill.
Would you call this a real premium card, or just a very expensive one?