UK investor building a long term portfolio of high quality, wide moat stocks. Receive a Free fractional share worth up to £130 when you deposit just £1 ↙️
Cantor Fitzgerald have maintained an overweight rating and $9 price-target for Merlin $MRLN ✈️
Merlin are a first mover in pursuing certifiable, takeoff-to-touchdown autonomy, and although they’re burning through cash, they maintain a strong cash position with 0 debt.
Credit @Investingcom
Merlin was invited to demonstrate its aircraft-agnostic autonomous flight platform at the kickoff of the @TxDOT’s Project NEXUS eIPP in front of federal, congressional, and state officials.
Read why that invitation matters, what the demonstration proved, and why programs like NEXUS are how autonomy moves from development toward safe deployment at scale. https://t.co/R8Nb5cm0Ul
Stocks like this can underperform for years, then suddenly rocket up and outperform the general market by a long way.
I completely agree with you that it could take awhile to get back to $5, but while they're still executing and my thesis is in tact I'll use it as an opportunity to DCA down. My cost basis will be into the high $4 range by the end of this month and low 4's before the end of the year (Based on the stock staying around $2). This is why position sizing is important, and I'll obviously be investing into other stocks during this time as well to hedge the risk, so even if Merlin under performs and takes 2 years to get back to $5, all being well, I should still make money on other stocks.
I think outside of Merlin the company, the macro facts aren't doing Merlin any favors with rate hikes, inflation worries, oil over $110 a barrel. So, once these hopefully calm down, more speculative stocks should see a bump to the upside.
Another tough week for $MRLN, but here’s why I’m still bullish…
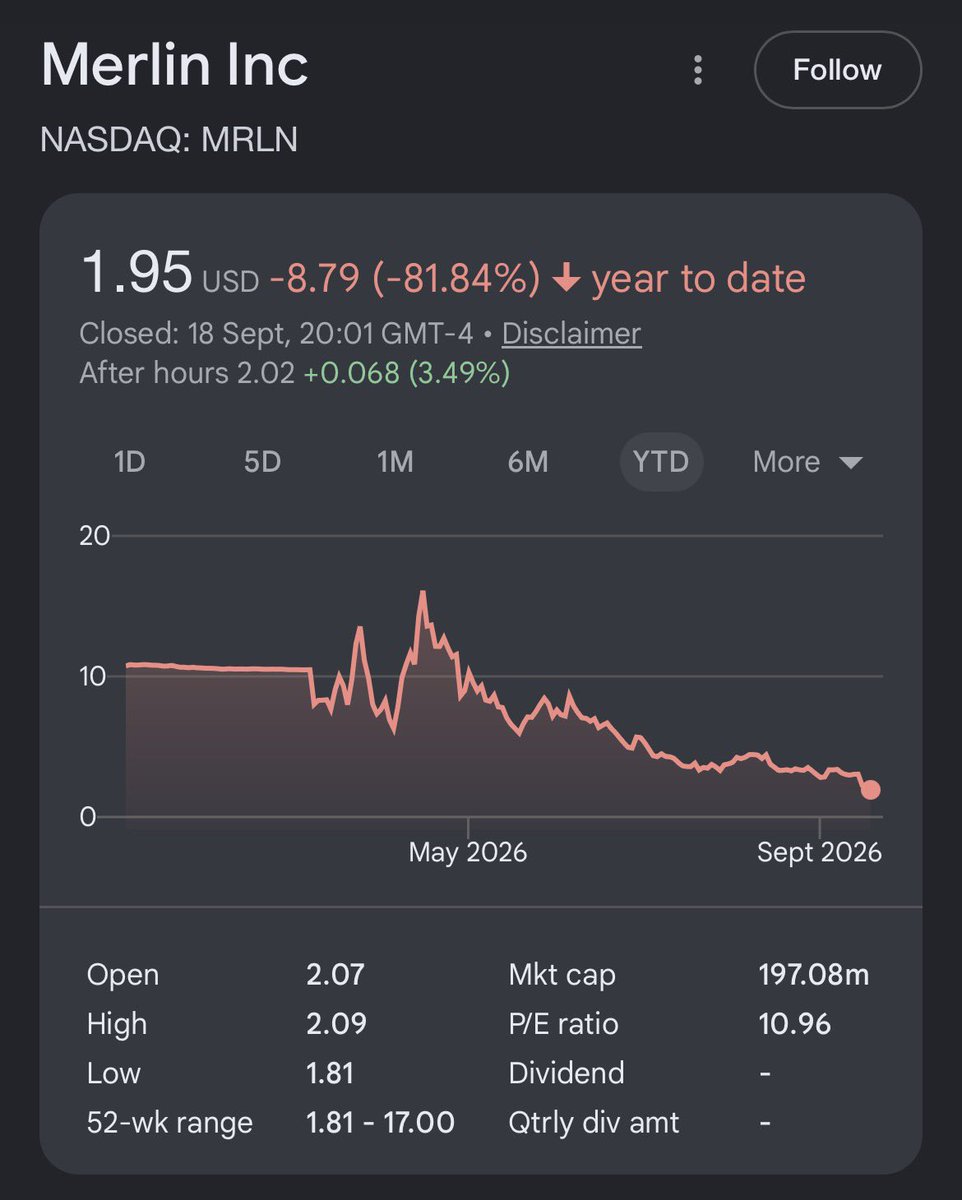
The stock is now down around 82% since going public back in March and there’s no sugar coating it. The sell off has been brutal.
But when I look at the business rather than the chart, I still see a company making progress.
Since going public, Merlin has:
✅ Secured a $105M USAF IDIQ contract
✅ Continued work on the KC-135 with GE Aerospace
✅ Announced an MOU with Northrop Grumman
✅ Expanded its relationship with IAI
✅ Received CAANZ Part 146 certification
✅ Continued flight testing and demonstrating its autonomy technology
The biggest issue remains monetisation. Meaningful revenue is still expected to be weighted toward 2027/2028, and the recent lock up expiry has added another layer of selling pressure.
But that’s exactly where I think the opportunity could be.
The share price has collapsed while, in my view, the underlying story has continued to develop. I’m not ignoring the risks such as dilution from needing to raise capital again and the long road to meaningful revenue are all real.
But at around $2, I’m continuing to DCA aggressively because my long term thesis hasn’t changed!
As long as they’re executing and progressing I’ll continue to add.
Long $MRLN
Your investing time horizon is too short if you’ve already written Merlin off as a loss.
It’s a pre-revenue SPAC. It’s going to come with risks. At these levels, I think it offers an asymmetrical reward, and it’s a risk I’m willing to take. The stock being down 80% from the IPO price is rough, but if the C130-J program is successful and a clear path to revenue is achieved this stock will fly.
This isn’t something that will happen overnight, and during that time they’re burning through around $25m a quarter, but with $183m cash on the books and 0 debt, it gives them a runway into financial year 2028 to show they are capital of producing real revenue. They already said in their Q2 earnings they expect cash burn to stabilise, or even be slightly lower for Q3/Q4, plus expect commercial revenue to come in 2027. Even if it’s a small amount the stock could rally, as it proves the product works and can produce consistent revenue.
@FactChecker92 If I didn’t have conviction I wouldn’t still be buying.
It’s easy to be bearish on a stock when it’s tanking, but if you take emotions out of the picture and focus on the company and its execution, I can’t fault them.
I’m still extremely bullish on Merlin $MRLN and will be allocating all of this months investment budget to build up my position even further.
The plan is to have 10k shares by EOY and a sub $5 cost basis (Which I’ll probably hit next month).
Moments like this are when emotions can take over, but looking at the execution of Merlin keeps me grounded and reminds me they’re executing incredibly well.
The C130-J, IDIQ contract is the revenue driver for now so once the next task order is released, I believe we will see more positive price action. Until then, I will be making the most of what I believe is a huge oversell, into what potentially could be the next big prime defence/aerospace player!
Long $MRLN ✈️
$MRLN Vu que c’est un titre dont j’ai parlé, je me dois de faire un petit update.
Évidemment, voir un mouvement pareil ne fait jamais plaisir. On paye clairement aujourd’hui la structure du titre. J’avais identifié ce risque en étudiant l’entreprise, mais je reconnais que le mouvement est plus violent que ce que j’avais anticipé.
C’est malheureusement quelque chose qui peut arriver sur les small caps et les micro caps, particulièrement lorsqu’elles sont issues d’une SPAC.
Pour autant, ce mouvement ne change pas ma lecture de la technologie de Merlin. La technologie existe, elle fonctionne et elle est déjà testée dans un environnement militaire.
Ce qui compte maintenant, c’est la transformation de cette technologie en contrats significatifs. Un seul contrat de déploiement sur une flotte publique ou militaire pourrait complètement changer la dimension de l’entreprise. Et si Merlin parvient notamment à transformer son travail actuel autour du C-130J en véritable contrat de production et de déploiement à plus grande échelle, le marché pourrait évidemment réévaluer très rapidement le dossier.
Mais c’est un pari de long terme. Ça peut prendre deux ans, cinq ans, voire davantage. Personne ne connaît le calendrier exact.
C’est pour cette raison que j’ai toujours insisté sur le niveau de risque : sur ce type de dossier, il faut être capable d’accepter des drawdowns de -50 %, -60 %, voire davantage. On peut avoir raison sur la technologie et sur la thèse à long terme tout en ayant un très mauvais timing boursier.
MRLN reste donc pour moi un gros pari sur l’avenir : le potentiel peut être considérable si la technologie débouche sur des déploiements à grande échelle, mais le risque l’est également.
À court terme, c’est surtout la structure post-SPAC et la pression potentielle liée aux titres devenant négociables qui pèsent sur le cours. À long terme, ce qui décidera réellement de la valeur de Merlin, ce seront les contrats, les déploiements et la capacité de l’entreprise à transformer sa technologie en revenus significatifs.
@TheGeordiePig Yeah, it looks quite attractive at these levels. I bought earlier this year for $240 and sold close to $280 and I think the company is in an even stronger position this time.
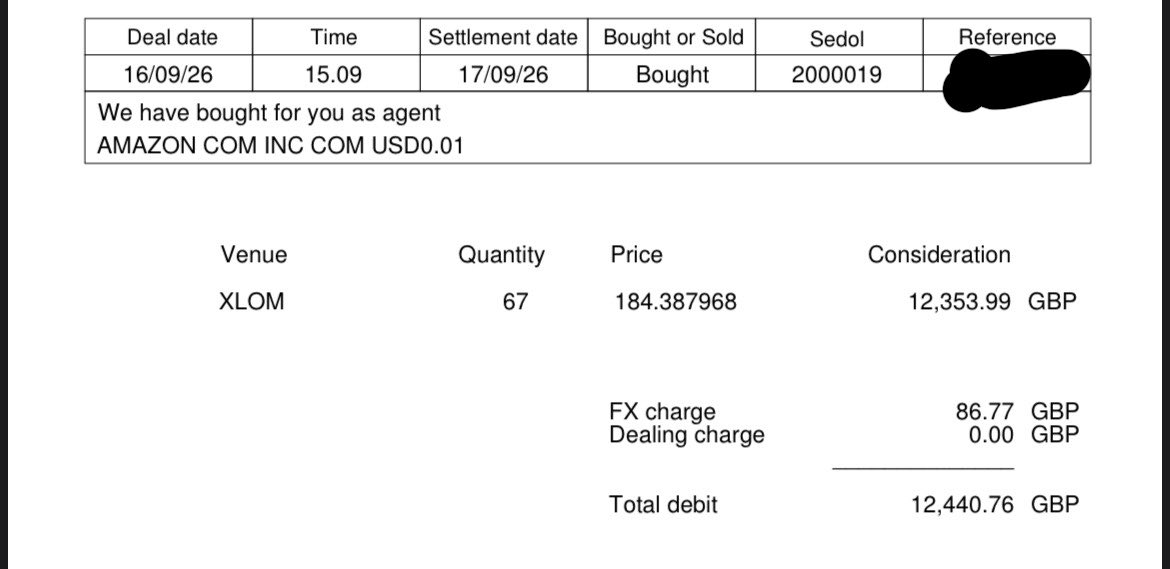
I bought back into Amazon $AMZN today.
67 shares @ $248.
It’s seems below fair value here, and has traded down from its highs.
FED meeting later today where they will most likely raise rates, but I think this is mostly priced into the market.
Matt George, Merlin $MRLN CEO and founder confirms he hasn’t sold a single share today!
This aggressive sell-off we’re seeing is most likely from early VCs taking profit.
It’s not nice to see, but this is a long term play and you can’t fault their execution.
Even though it’s hard, you always have to remember to seperate the stock from the company.
I’ve added around another 200 shares of $MRLN today.
I bought it just after market open, so it was quite far off today’s lows but still a solid price long-term imo.
The insider lock-up period ended today, so lots of new shares have flooded the market and some insiders are cashing in.
I’ll be honest, I didn’t expect such a big sell-off, but the thesis of the company is still in tact and I think if they can execute these will be attractive prices in a couple years times.
Not financial advice.