NEW Industry developments , Regulations is something one should never Ignore
IRDAI's draft proposes:
1) Nil commission on new-vehicle third-party motor, 5% cap on OD
2) Health capped at 15% first year, 5% on renewals
3) Tighter EoM limits, plus no mandatory bundling of insurance with loans
Motor commissions average ~24% today. Credit-linked insurance via NBFCs pays ~42% .
Start with PB Fintech & Turtlemint because they are purest play on this development . Health, term and motor are the core of Policybazaar's revenue, and potentially there could be commissions cut by a third to a half which could lead to substantial cut in earnings
Now look at the chart - Insurance income as % of PBT:
L&T Finance 25.6% | Poonawalla 17.8% | Chola 16.3% | Bajaj Finance 10.0% | Shriram 2.6%
Lose even half of it, and L&T Finance gives up ~13% of PBT.
Summing it up : It's a draft, comments are open till Oct 25, However even if the drafts doesnt materialise this could be a perception derating factor to entire space.
This is the power of tracking NEW developments , which one has to look during Anti thesis pointers as well.
Not a buy/sell recommendation. DYOR.
#PharmaStocks In Focus | US Sets Out Section 232 Pharma Tariff Framework
#Macquarie on Indian CDMOs
- Exemptions remove key overhang for Indian CDMOs like Divi's Lab
- 9 drug classes exempted from tariff; 19 jurisdictions, including India, exempted
@ekta_batra#Pharma #PharmaTariffs #Section232 #IndianPharma #CDMO #DivisLabs #SunPharma #ZydusLife #DrugTariffs #USPharma #PharmaStocks #CNBCTV18Market
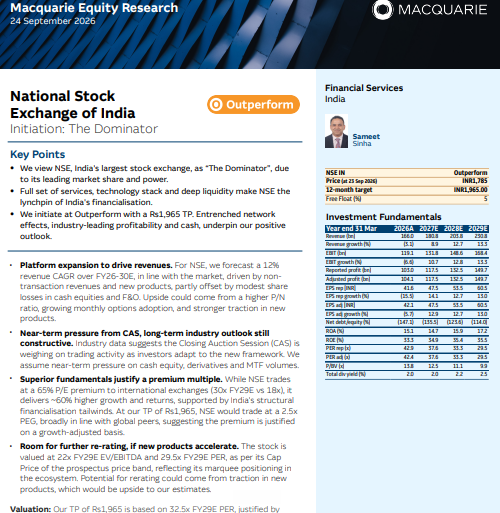
Macquarie initiates coverage on NSE on the day of its listing
Macquarie on NSE
Initiate O-P, TP Rs 1965
view NSE, India's largest stock exchange, as “The Dominator”, due to its leading market share and power.
Full set of services, technology stack and deep liquidity make NSE the lynchpin of India's financialisation.
Entrenched network effects, industry-leading profitability and cash, underpin our positive outlook
@CNBCTV18News@_prashantnair@Nigel__DSouza
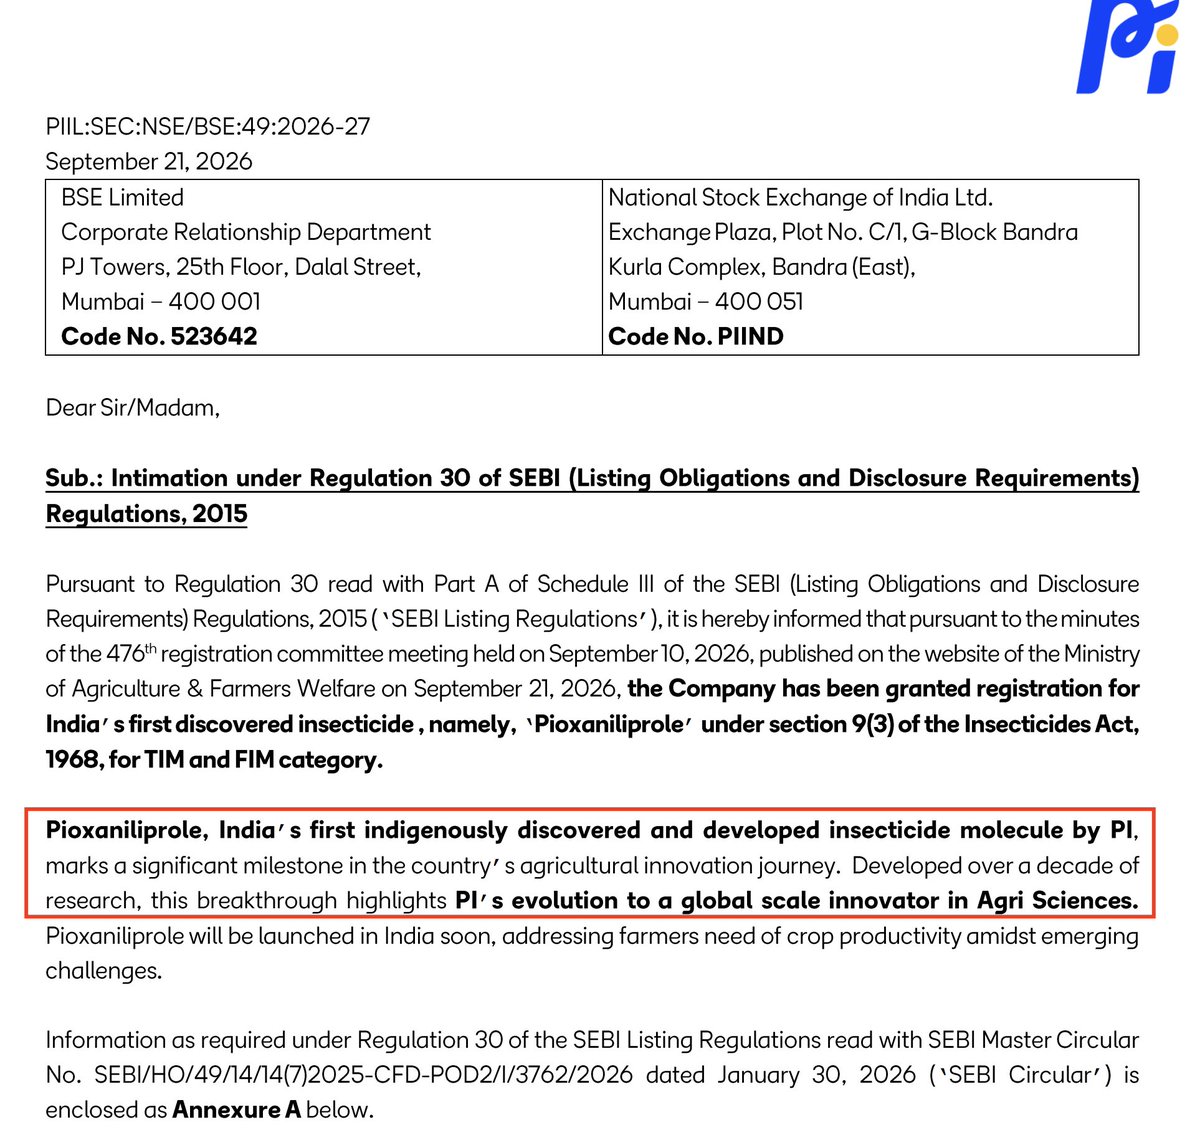
Interesting development from PI Industries!
PI has developed India's first indigenously discovered insecticide after more than a decade of R&D.
Discovering a new molecule typically takes 10-12 years, requires around $300 Mn of investment & has a success rate of just 1 in 100,000 molecules tested.
- PI has spent over a decade building its R&D capabilities, with 700+ scientists, 250 PhDs & investments of several thousand Cr.
- The new insecticide targets a domestic market opportunity of 3,000-4,000 Cr across crops such as chillies, rice, corn etc
- The global market opportunity is estimated at $750-800 Mn. PI is targeting 10-15% market share over time, with plans to enter the US, Brazil and select Asian markets.
#Nity#Stockmarket#Optiemus
Too good to be true
Just heard Ashok Gupta, Chairman of Optimus Infra on @NDTVProfit
FY26 Revenue Rs 1770 cr
FY28 Revenue above Rs 7000 cr
2000 cr Revenue from new vertical Screen Protectors !!! ( Production capacity 2 cr, pricing Rs 1000 cr per piece??)
And core business revenue growth from around 1800 cr to 5000 cr? That too without considering Nothing-CMF JV???
Stock up 37% in 2 days…
Be aware…..
@NDTVProfit
#Nifty#Stockmarkets
A gem presentation from Ishmohit @soicfinance
Covered all 5 futuristic themes;
Semicon, Space, EMS, ADS &
EVs
Complete value chains, TAM, supporting Govt policies, Capex, Individual cos within this ecosystems
Just spare 42 minutes and you can develop a portfolio for next decade.
👇🏻👇🏻👇🏻
Where I’m looking for India’s next big stocks https://t.co/mQkkD0VcOX via @YouTube
#DIXON_TECHNOLOGIES#JPMorgan
Overweight Call
Target Price At Rs 16,400/Share
India Has Potential To Become A Major Global EMS Hub As Companies Diversify Mfg
Co Targets Top-10 Global EMS Position In 5 Years & Top-5 In 10 Years
Next Growth Phase Expected To Be Increasingly Export Led
Component Ecosystem & Lower Land/Power Costs Critical To Export Competitiveness
Co Targets Maintaining 30%+ RoCE, ECMS Incentives Support Component Manufacturing
Moving Into Higher-margin, Low-Vol Areas Including Defence, Medical Elec, Drones & Robotics
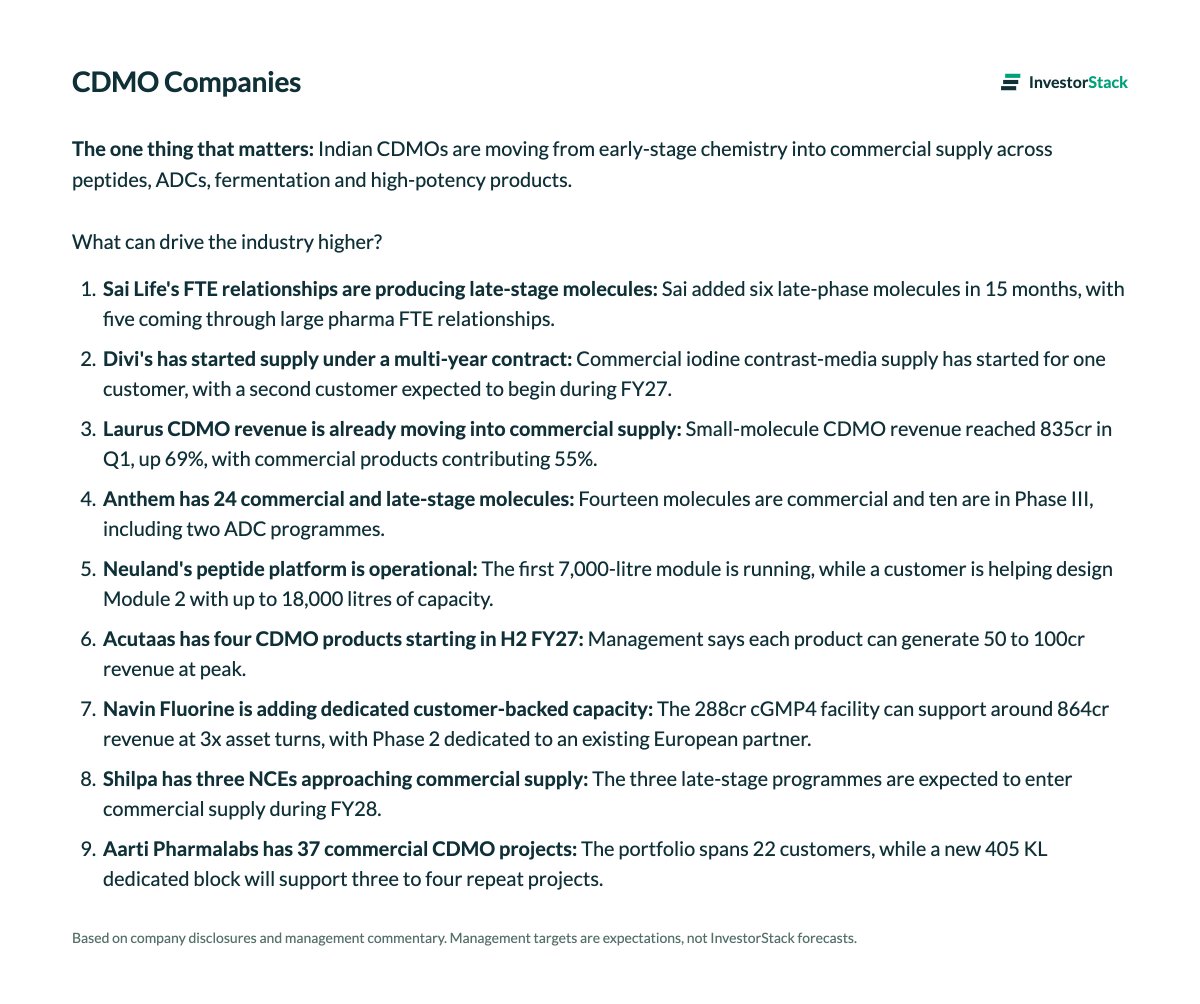
Growth Triggers for CDMO companies.
Indian CDMOs are moving from early stage chemistry into supply across peptides, ADCs & fermentation.
Sai Life added 6 late phase molecules in 15 months. 5 came through big pharma FTE relationships.
Sai's new discovery facility is already sold out.
First dedicated peptide lab for a top tier pharma is coming online shortly.
Divi's has 18 to 20 custom synthesis projects that are commercial or moving into commercial supply.
Divi's makes its own peptide building blocks, amino acids, resins and fragments.
Anthem has 14 commercial molecules and 10 in Phase three. Two of the Phase three programmes are ADCs.
Management expects some of its Phase III pipeline to commercialise in 18 to 24 months.
Acutaas has 4 CDMO products starting from H2 FY27. Each can do 50 to 100cr revenue at peak.
Shilpa has 3 late stage NCEs approaching commercial supply in FY28.
Shilpa is developing ADC biosimilar with payload, linker and conjugation capabilities in house.
Polycab Family Office 🔥
Everyone knows Polycab, but very few know this
Jaisinghani family’s exposure goes well beyond Polycab, across multiple Mainboard & SME-listed companies
Mainboard Companies -
La Tim Metal
Jaro Education
Sai Parenterals
Ardee Industries
Arrow Greentech
SME Companies -
L.T. Elevator
Star Finvest
Parth Electricals
Yash Highvoltage
Shanti Inorganics
Qualiance International
Grand Continent Hotels
& Separately, Polycab holds ₹3,405 Cr in current investments, largely in debt & arbitrage funds
Polycab story is bigger than just Polycab 🔥
#WATCH | Is India’s Market Underperformance Finally Set To End?
Kunal breaks down Nifty’s deep oversold reading, extreme market sentiment and historical Fed rate-hike cycles — and explains why these signals could point towards a potential market bottom and a stronger setup for Indian equities ahead.
#WATCH #Nifty50 #DStreet #IndianMarkets #StockMarket #Markets #Fed #ETNOW @kbbothra
Jefferies has mapped India's next industrial wave: 36 stocks across six sectors set to ride the shift into semiconductors, space, data centers, electronics, solar and aerospace. Think Dune, except the buried treasure here is silicon, satellites and solar cells. A 🧵
5 Pharma CDMO Stocks with Strong Capex Plans
India’s Pharma CDMO opportunity is getting bigger.
Global pharma is diversifying away from China, molecules are becoming more complex, and Indian companies are ramping up capacity aggressively.
Here are 5 CDMO stocks worth watching over the next 3–5 years.
#IntellectDesignArena
Can Intellect Design’s AI Product generate assymetric growth ?
Based on the interview with Arun Jain, the Chairman and Managing Director of Intellect Design Arena, sharing the key drivers for their financial metrics :
1. Drivers of Sales Growth % (Getting more money in the door)
For a software company, growth is about launching high-value products and making them incredibly easy for customers to buy. Intellect is driving this through three main levers:
Solving the "Last 10% AI Problem" (The Product): Banks are investing heavily in general AI models like Claude or OpenAI, but general AI cannot easily understand a bank's highly complex internal rules, risks, and policies. Intellect created a new product called MSoC (MML System of Connected Knowledge). Think of it as a "translator and secure brain" that sits between a bank's data and the AI engine, ensuring the AI gives 100% accurate, safe, and private answers based on the bank's own internal rules.
The "Netflix-Style" Subscription Model (The Sales Process): Traditional banking software takes months or years to sell and install. Intellect has changed the game with MSoC: they can demonstrate its value to a bank in just 2 days, offer a 30-to-60-day free trial, and then convert them into paid subscribers. This speed makes scaling global sales much faster
Large Backlog and Geographies: They already have a massive sales pipeline of 13,000 odd crores (deals they are bidding for), with North America emerging as a key growth engine
2. Drivers of Operating Profit Margin % (How much of each rupee they keep)
Pre-paid R&D: All the research and development costs to build MSoC are already fully paid for and "burnt into" that 680-crore cost base
The Margin "Shoot-Up" Effect: Since their costs are locked at roughly 680 crores, once their revenue crosses this threshold, almost every single rupee of new sales (especially high-margin MSoC subscriptions) flows directly to profit. Management expects this dynamic to cause operating margins to suddenly shoot up from 19% to 25% or even 30% over the next 12 to 18 months
3. Drivers of Reinvestment Rate (Planting seeds for future growth)
A technology company can only stay ahead if it constantly invents new things. How a company allocates its cash is crucial:
Heavy R&D Spending: Instead of letting cash sit idle or paying it out in short-term buybacks, Intellect aggressively reinvests 100 crores every single quarter from its core cash directly into research and development
Immediate Expense Policy: Rather than hiding this R&D expense on the balance sheet as an asset (capitalizing it), they write it off immediately as a current expense. This temporarily lowers their current reported margins but builds massive, long-term, debt-free intellectual property
Patented Moat: This continuous reinvestment funds a team of 1,200 research specialists and has successfully generated 39 patents filed from India in spatial graphs and connected knowledge systems
Investor Cautionary Note:
While management has outlined an ambitious future revenue potential of ₹500 crore to ₹2,000 crore for their new MSoC product, investors should treat this as a high-potential "growth option" rather than a guaranteed revenue stream. The technology is entering a critical 12-month "evangelisation" phase, and management itself has cautioned that they "do not know" if they will ultimately succeed, noting that many Indian software companies have historically struggled to scale products in this space. Because the near-term financial success of MSoC is not yet locked in, investors must closely track tangible customer adoption, trial conversions, and recurring subscription updates over the coming quarters rather than pricing in this growth prematurely
link to the interview - https://t.co/Gj0NBTCgJ6
🚨 I strongly believe 2027–2028 could be BIG years for Indian equities. 🇮🇳📈
Think about it:
2024 → 2026 = Almost 2 years of consolidation/time correction.
Nifty? Still around the same 24K zone.
Portfolios? For many investors, almost 2 years with hardly any meaningful movement.
But beneath the surface, something is changing.
I’m checking hundreds of charts — and the pattern is becoming increasingly clear:
👉 Most quality stocks have completed significant time-wise corrections
👉 Some overheated names have already corrected heavily price-wise
👉 Roughly 20–30% of charts are already showing signs of waking up
👉 The remaining 70% could gradually follow one by one
This is exactly when you DON'T want to get bored and leave the market.
Consolidation builds the base.
The base builds the next trend. 🚀
2024–26 may ultimately be remembered as the period when portfolios tested our patience.
2027–28 could be when that patience gets rewarded.
Time to identify quality, build the PF carefully and BOARD before every chart starts looking obvious.
Good times may be closer than they appear. 🇮🇳🔥
This is my market view, not investment advice. Do your own research
India’s growth engine is firing on all cylinders.
GFCF growth more than doubled YoY to ~12% in Q1, reflecting stronger Capex and investment momentum. Robust PFCE signals resilient domestic demand, while key economic sectors also gain traction, reinforcing broad-based growth.