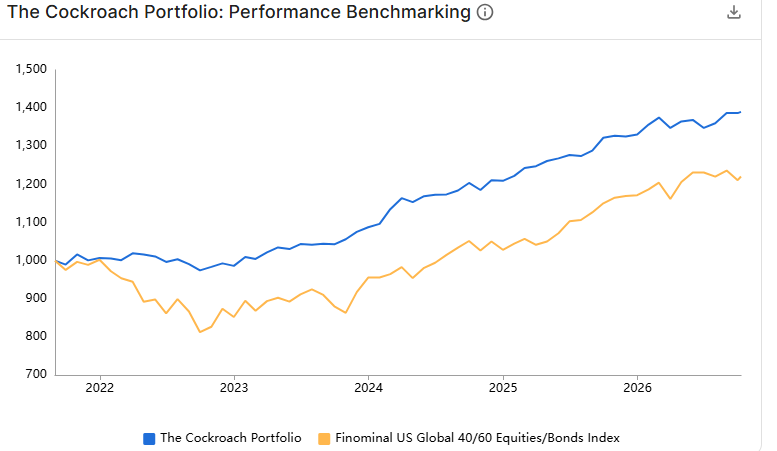
What was the out-of-sample performance? The article on the Cockroach portfolio was published on September 1st, 2021, and most complex portfolios perform poorly out of sample. However, in this case, the portfolio has generated a higher return (6.7% vs 4.0%) and Sharpe ratio (0.77 vs 0.03) than the benchmark index since then, primarily due to poor bond performance. Naturally, you could switch to an all-weather benchmark, but that introduces the risk of benchmark optimization. Long live the cockroaches.
https://t.co/to0EbOaNP2
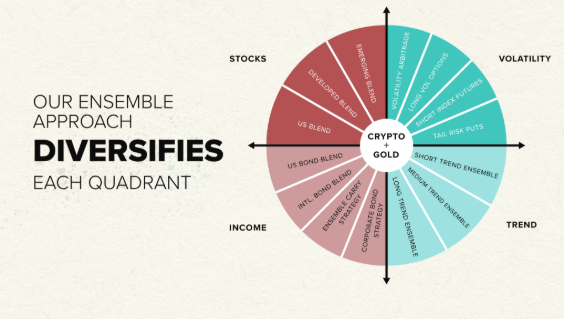
Portfolio Review: The Cockroach Portfolio. What is the investment strategy? We're analyzing a portfolio based on the investment philosophy of the Cockroach Fund run by Mutiny Funds. RCM Alternatives described the portfolio construction as comprising equal allocations to global equities, global bonds, long volatility, and trend-following strategies, with a dash of gold and crypto. The article was published in 2021, so we have five years of out-of-sample performance.
https://t.co/40sFOOabJO
Which funds were the major risk & return contributors?
Global equities generated most of the returns, followed by managed futures. However, cryptocurrencies also contributed significantly for a 2.5% position. GBTC's marginal contribution to risk was 47%, and it accounted for 25% of total risk, given Bitcoin's volatility over the last decade.
https://t.co/MHXoDHACN7
We can extend the analysis to 2004 using the Finominal USA Momentum and Growth Indices. This changes the perspective, as growth stocks have generated higher absolute returns and Sharpe ratios than the U.S. stock market and momentum stocks. We can attribute momentum stocks' poor long-term performance to their much worse 2009 performance, when stocks started recovering after the GFC. However, the long-term evidence for growth stocks shows that there is no positive excess return associated with them. The starting point for the indices in 2004 is also before the tech bubble implosion, when growth stocks performed poorly.
https://t.co/j612FGx75G
Product Review: Momentum vs Growth ETFs (SPMO vs VUG). What's the strategy & portfolio composition?
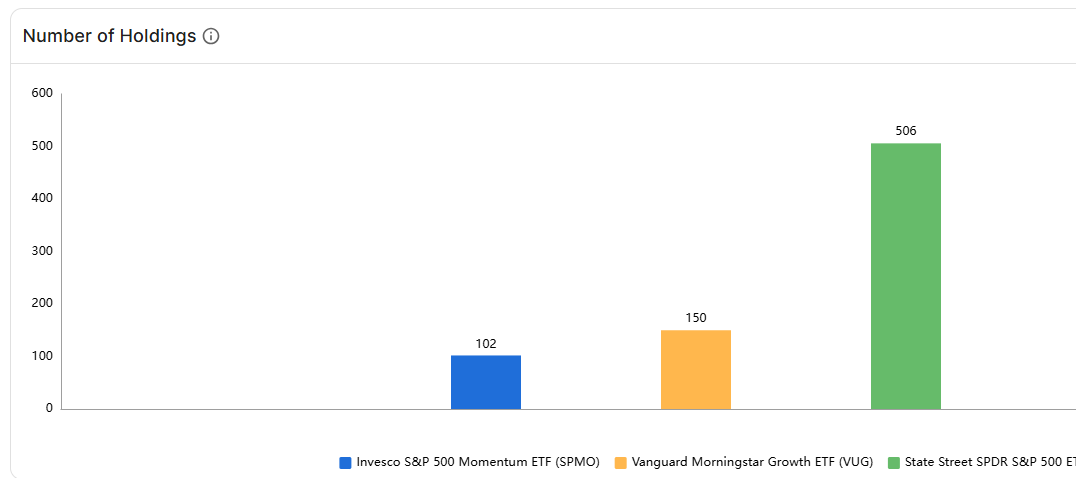
On Bloomberg or CNBC, talk show hosts often use momentum and growth stocks interchangeably, but they are two distinct strategies. We use the Invesco S&P 500 Momentum ETF (SPMO) and the Vanguard Growth ETF (VUG) as case studies. SPMO selects the top 100 momentum stocks from the S&P 500, and scales the score by volatility to identify consistent outperformers. VUG selects large-cap stocks based on expected and historical EPS & sales growth, along with two quality metrics. SPMO holds roughly 100 stocks and charges 0.13% pa, compared to 150 stocks and 0.04% for VUG.
https://t.co/2XWK1IDPq9
How have the funds performed? We have only 11 years of common track record: VUG outperformed significantly from 2020 to 2022, and SPMO from 2024 onward. Both have outperformed the S&P 500 since 2015. SPMO also generated a significantly higher Sharpe ratio of 0.82, compared to 0.71 for VUG and 0.72 for the S&P 500.
https://t.co/Jzq6gnM7I8
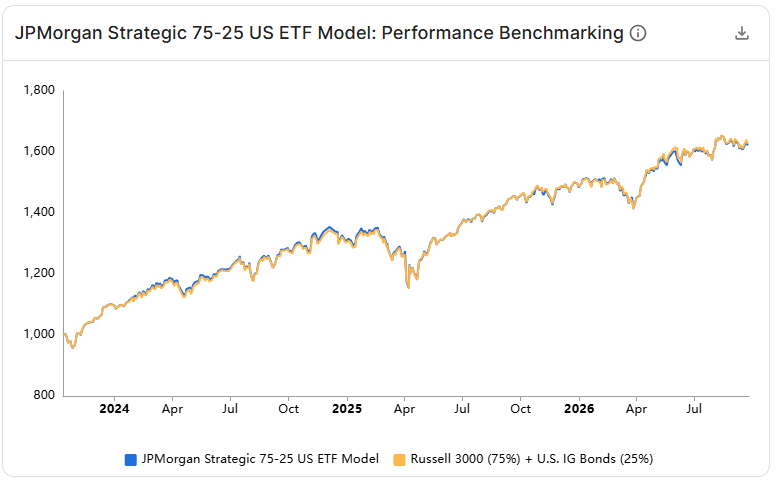
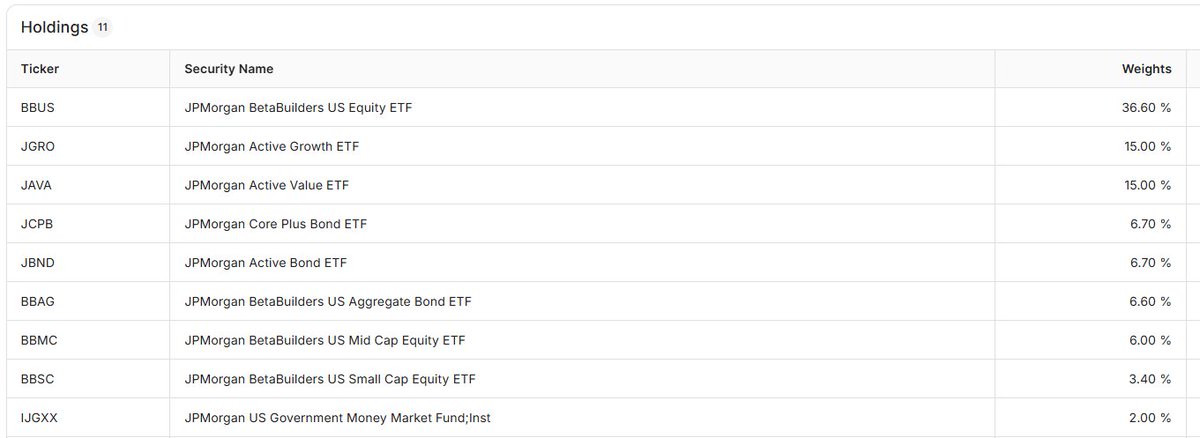
Can the portfolio be simplified? Allocating to 11 funds for U.S. equity and bond exposure makes little sense, since these funds overlap or conflict in risk exposures. Investors can replace the portfolio with the benchmark, ie the Russell 3000 Index (75%, IWV) and U.S. IG Bonds (25%, AGG), which are available via iShares for a total fee of 0.16% pa.
https://t.co/DbtuNbUEJA
Portfolio Review: J.P. Morgan's Strategic 75-25 US ETF Model. What is the investment strategy? Provide a growth-oriented portfolio dominated by U.S. equities (75%), with only moderate fixed-income exposure (25%).
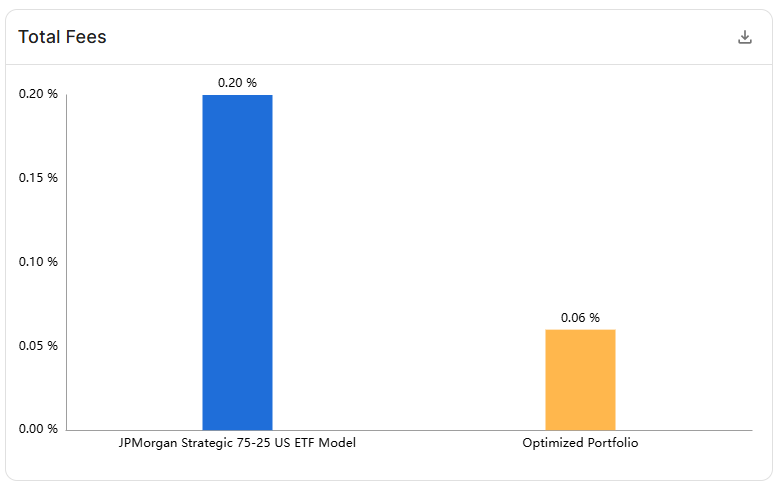
What are the holdings? The portfolio comprises 11 ETFs from J.P. Morgan, with the largest allocation to the JPMorgan BetaBuilders US Equity ETF (BBUS, 37%), followed by JPMorgan Active Growth ETF (JGRO, 15%), and JPMorgan Active Value ETF (JAVA, 15%). The portfolio is cheap at a 0.20% pa.
https://t.co/rkSZ0LqgKv
Can fees be reduced? We can replace every fund in the portfolio with a cheaper option, reducing the portfolio cost from 0.20% to 0.06% per annum. For example, we could replace the JPMorgan Active Growth ETF (JGRO), which charges 0.43%, with the Vanguard Russell 1000 Growth ETF (VONG), which charges only 0.07%. The cheaper portfolio would have slightly outperformed.
https://t.co/nks3Mg2okO