Shorting Leveraged ETFs: The Role of Borrowing Costs and Rebalancing in Volatility-Decay Strategies
Leveraged ETFs provide amplified exposure to an underlying index, but their daily reset mechanism creates volatility drag, which can substantially reduce their long-term value. This raises the possibility of exploiting the effect by simultaneously shorting leveraged ETFs with opposite exposures. We examine a 50/50 short portfolio of TQQQ and SQQQ, which provides approximately neutral exposure to the Nasdaq-100 while seeking to capture volatility decay. We analyze the strategy explicitly incorporate borrowing costs. We further investigate daily and weekly rebalancing, execution timing, and tranche-based rebalancing over five-, ten-, and twenty-day horizons. The results show that borrowing costs materially reduce the apparent profitability of the strategy. Moreover, after costs, returns are concentrated in a small number of high-volatility periods, while the strategy is largely neutral during ordinary market conditions. The findings demonstrate that ignoring short-selling costs and implementation details can substantially overstate the attractiveness and robustness of volatility-decay strategies.
https://t.co/3TI9Sh5H45
#triple #leveraged #etfs #TQQQ #SQQQ #volatility #decay #arbitrage #strategy #quant #trading
Bitcoin Runs on a Clock: Why Every Price Indicator Dies and the Halving Clock Doesn’t
For anyone trading or investing in Bitcoin, a familiar indicator can become a dangerous comfort blanket. Josh Molnar’s Bitcoin Runs on a Clock argues that classic cycle signals—such as MVRV, the Mayer Multiple and Pi Cycle Top—have weakened as Bitcoin’s price swings become less extreme. Thresholds calibrated to earlier cycles may consequently stop triggering, leaving investors waiting for a sell signal that never arrives. The practical takeaway is that a strong historical record does not make an indicator’s settings permanent. If the market changes, the dashboard needs to change with it.
https://t.co/0PbuuGGfeJ
#bitcoin #halving #quant #analysis #investment #trading #strategy
The alignment is a forward-fill, which is causal. The monthly series is resampled onto the Friday grid and then forward-filled. There is one residual bias, though. FRED stamps the monthly Moody’s yields on the first of the month, but the figure is a monthly average of daily yields. By placing that value in the first week of the month and ffilling, the code makes a month-average observable at month-start. It's a genuine optimistic bias, although small in magnitude. Credit spread is the most persistent feature in the panel, so month-to-month drift is tiny.
Does More History Help? A Market-Regime HMM and the Trouble with Out-of-Sample Evaluation
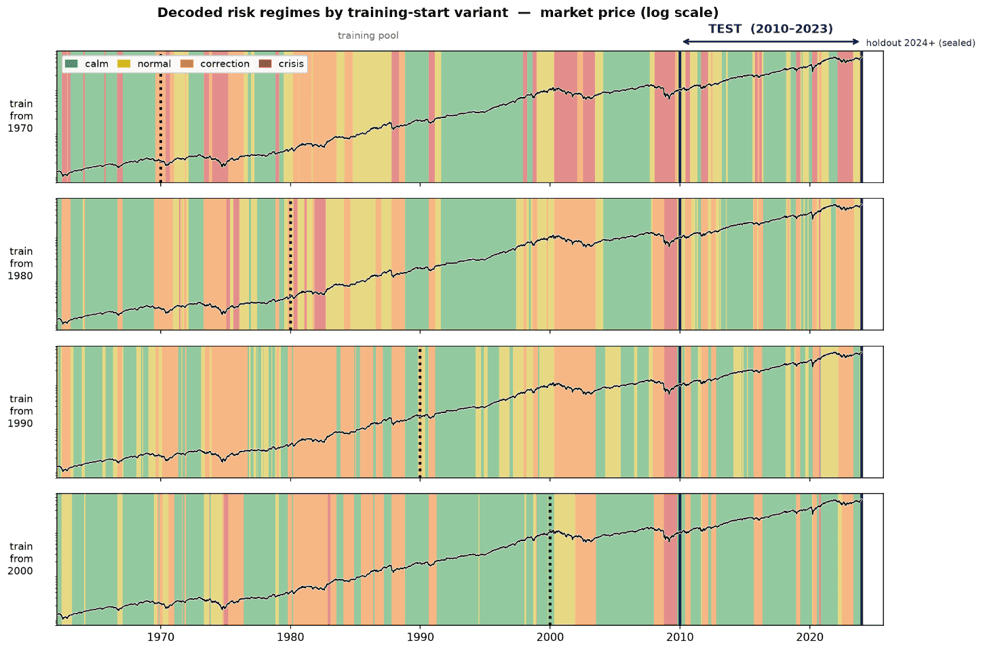
This article investigates whether longer historical training periods improve the out-of-sample performance of a Hidden Markov Model (HMM) used for identifying financial market regimes. Four four-state Gaussian HMMs are compared, differing only in the starting point of their training data (1970, 1980, 1990, and 2000), while being evaluated on the same test period. The model uses five market-based features capturing volatility, drawdowns, credit conditions, and sector rotation to identify latent risk regimes.
The results show that selecting models solely by out-of-sample likelihood can lead to misleading conclusions, favoring shorter training histories that fail to capture crisis regimes. When evaluated using regime stability, economic interpretability, and strategy-based metrics, the model trained on the longest history provides better generalization and avoids overfitting.
The study highlights that validation methodology and evaluation criteria are as important as model design and data length when assessing regime-based investment models.
https://t.co/TfpVCHIPKO
#HMM #market #timing #risk #regimes #model #quant #trading
Hello all,
With autumn underway, we’d like to share the latest developments at Quantpedia.…
– Screener and API extended with two new fields: Transaction Costs and Robustness
– 11 new Quantpedia Premium strategies
– 7 new related research papers
– 8 new backtests
– and finally, 6 new posts on our Quantpedia blog
https://t.co/A7JrJD3Dfv
Trading the Multi-Asset Drift Around U.S. Elections
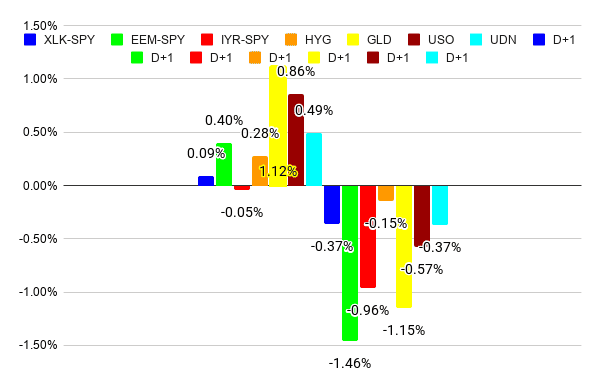
We analyze a multi-asset calendar anomaly around U.S. federal elections that is consistent across assets and simple to trade. While our previous study documents a robust pre-election drift, the cross-asset pricing of its D+1 resolution remains unmapped beyond SPY. Using a diversified ETF basket spanning technology, emerging markets, real estate, high-yield credit, gold, oil, and foreign exchange, we show that election day itself is neutral to slightly positive — an equal-weight D0 long earns a modest 1.03% p.a. at a Sharpe of 0.19, which we document as the control arm of the experiment but do not trade — while the following session delivers a systematic sell-off across all seven legs as the political uncertainty premium collapses. An equal-weight short on D+1 yields 1.86% per annum with a Sharpe of 0.31 and a maximum drawdown of -4.16%, achieved over 13 trading days in 26 years. Intermediate Treasuries exhibit the inverse pattern, selling off in the four days before the vote and rallying from D0 to D+2, with a Sharpe of 0.48.
https://t.co/cDykYREsjv
#election #stock #market #timing #trading #strategy #trump #quant #algo
A Century of Meme Stocks and the Price of Coordination
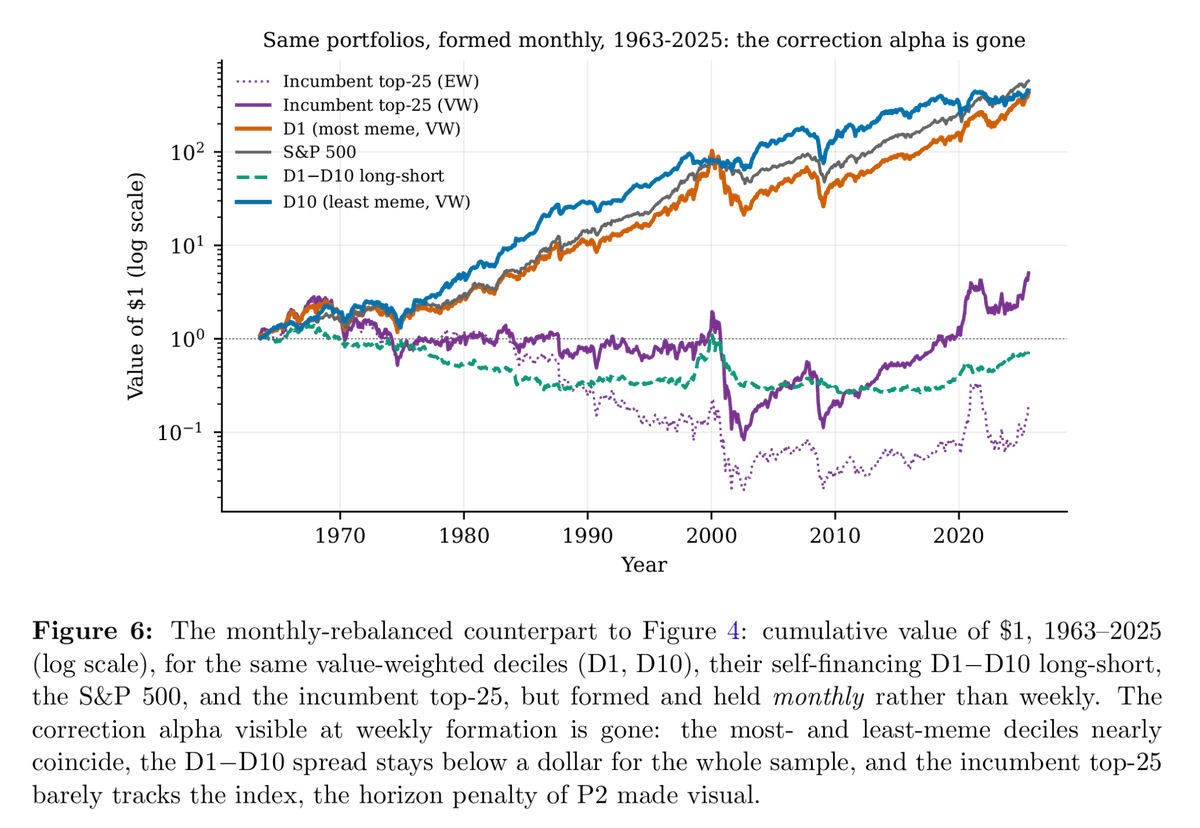
Meme stocks are commonly studied through social-media activity, but this approach limits both the historical scope of research and the signals available to practitioners. In A Century of Meme Stocks and the Price of Coordination, Chad Schmerling develops an alternative: a machine-learning model trained to identify the holdings of the Roundhill MEME ETF using market and firm-level data rather than textual inputs. By adapting the feature set to historical data availability, the paper constructs a measure of “memeness” extending back to 1926. For traders and portfolio managers, its principal contribution is a framework for identifying speculative activity and examining how its return implications vary with the investment horizon.
https://t.co/H6GIZFpg0Y
#meme #bubble #fomo #stocks #quant #algo #trading #strategy #analysis
A New Stage, a New Deadline: Quantpedia Awards 2027 Are Here Again!
Quantpedia Awards 2027 are here — with over $25,000 in prizes and a bigger stage for outstanding quant research! In partnership with The Data Driven Market Show, we’ll announce the winners live on stage at Future Alpha 2027, during the conference on March 16–17, 2027, putting their work in front of the global quantitative investing community.
Compete for cash awards, education, research tools, and industry recognition — but note the earlier submission deadline: December 31, 2026, at 23:59 UTC.
https://t.co/PGf8Dx1m5I
#quant #algo #trading #research #competition #quantpedia #awards
Can Weakening Morning Order Flow Predict SPY Reversals?
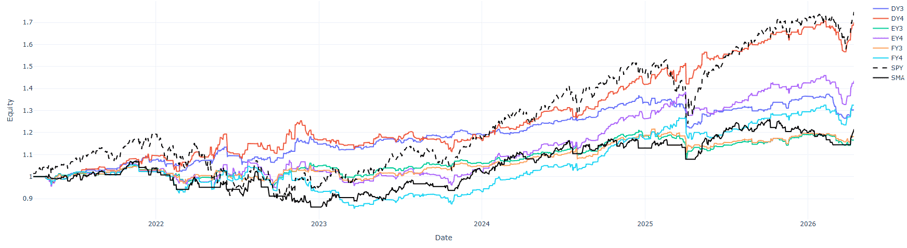
In a previous article Building and Testing Trend-Following Strategies on One-Minute SPY Data, we investigated whether retail activity indicators derived from one-minute SPY data could be used to construct profitable trend-following strategies. The results suggested that we are able to construct strategies that are often able to achieve superior risk-adjusted performance. In this article, we examine an alternative hypothesis. Instead of assuming that changes in retail activity signal the continuation of an existing trend, we investigate whether persistent declines in order flow may create conditions for a subsequent market reversal. More specifically, we analyze situations in which selected trading activity indicators decrease for several consecutive trading days and evaluate whether such sequences are followed by above-average SPY returns.
https://t.co/DHQe1bxO9A
#intraday #extended #alternative #dataset #quant #algo #trading #strategy #reversal #equity #market #timing #orderflow #activity
Building and Testing Trend-Following Strategies on One-Minute SPY Data
Intraday trading strategies have gained increasing attention as advances in computing power and market data availability have made intraday strategy analysis more accessible. While many trading strategies are traditionally developed and evaluated using daily price data, shorter timeframes can provide additional opportunities to identify and exploit market trends within a single trading session. In this article, we investigate the performance of trend-following strategies based on selected technical indicators computed from one-minute price data for SPY ETF. The historical dataset, provided by Algoseek, serves as the basis for designing, backtesting, and comparing several intraday trading approaches.
https://t.co/1P2Ed0K2g7
#intraday #extended #alternative #dataset #quant #algo #trading #strategy #trendfollowing #equity #market #timing #retail #activity
@KestrelQuant We use intraday just for the signal generation, not for trading alone. Trades are open and closed once a day. Therefore there is not a problem with a slippage/costs.
This is not 20 crossing in a session ... if you read the paper more deeply, there is written, that we just use the intraday signal for as the trigger, but the trade is just one in a day (at maximum) - either for overnight period or for the next day ... which is 1/20 of the costs you mentioned ...
We are well aware of the dangers of crossing spread and would not write article that has a problem with slippage/costs.
Do Airline Stocks Take Off Around U.S. Holidays?
Holidays put people in motion. In the days surrounding major U.S. holidays, airports become busier as travelers visit their families or take advantage of extended weekends. Financial markets themselves are known to display a holiday-related seasonality. In our previous research on the Pre-Holiday Effect in Commodities, we identified a short-term price drift in crude oil and gasoline before major U.S. holidays. Increased travel and the associated expectation of higher fuel consumption offered one possible explanation. This naturally raises another question: if holiday travel leaves a seasonal footprint in energy markets, can it also be detected in the stocks of the airlines transporting those travelers? To investigate this possibility, we analyze the performance of the U.S. Global Jets ETF (JETS) around major U.S. holidays. We first examine its daily returns from ten trading days before to ten trading days after each holiday and use the resulting return profile to identify the strongest seasonal windows. We then formulate two directional JETS strategies and a JETS–USO strategy.
https://t.co/S4sLOR7qwP
#holiday #seasonal #quant #trading #strategy #jets #uso #etf
From Barrier Crossings to Terminal Distributions: A Skellam-Based Options Pricing Framework for 0-DTE Markets
The explosive growth of hyper-liquid 0-DTE markets has pushed traditional options pricing infrastructure to its breaking point, as continuous Black-Scholes calculus can collapse into an unusable point mass at expiration. Rather than patching a broken formula with hand-fitted tweaks, a new paper suggests dismantling legacy math by replacing continuous geometric Brownian motion with a discrete, order-book-driven structural layer. Instead of smoothing over intraday price action, this model captures the raw physical reality of high-frequency liquidity by deriving a closed-form framework where the implied volatility surface is built directly from actual market microstructure.
https://t.co/2seNW2Syw5
#0DTE #options #trading #pricing #quant #algo #strategies
Quantpedia in August 2026
Hello all,
We hope you had a great end to the summer, whether August meant a final holiday or a return to the office. Here’s a quick recap of the latest developments we prepared for Quantpedia in the last days of summer…
– new report in the Live Strategies section called Composite Analysis
– 11 new Quantpedia Premium strategies
– 5 new related research papers
– 8 new backtests
– and finally, 5 new posts on our Quantpedia blog
https://t.co/LJNCHTy8qk
#quant #algo #live #trading #strategies #backtesting
Do LLM "Crowds" Produce Investment Signals? An Empirical Test
The integration of artificial intelligence into algorithmic trading has ignited a race to transform generative text into systematic alpha. A new paper written by Steven Edwards empirically investigates whether constructing a synthetic consensus using large language models can simulate information aggregation dynamics or if it merely acts as a sophisticated echo chamber. By utilizing an expansive framework to evaluate portfolio construction across distinct synthetic mandates, the study challenges whether generative agents can truly democratize the wisdom of crowds within highly efficient capital markets.
https://t.co/cIOnPNmAZu
#trading #strategy #LLM #agents #quant #AI #signals
Why Average Strategy Performance Can Mislead Portfolio Research
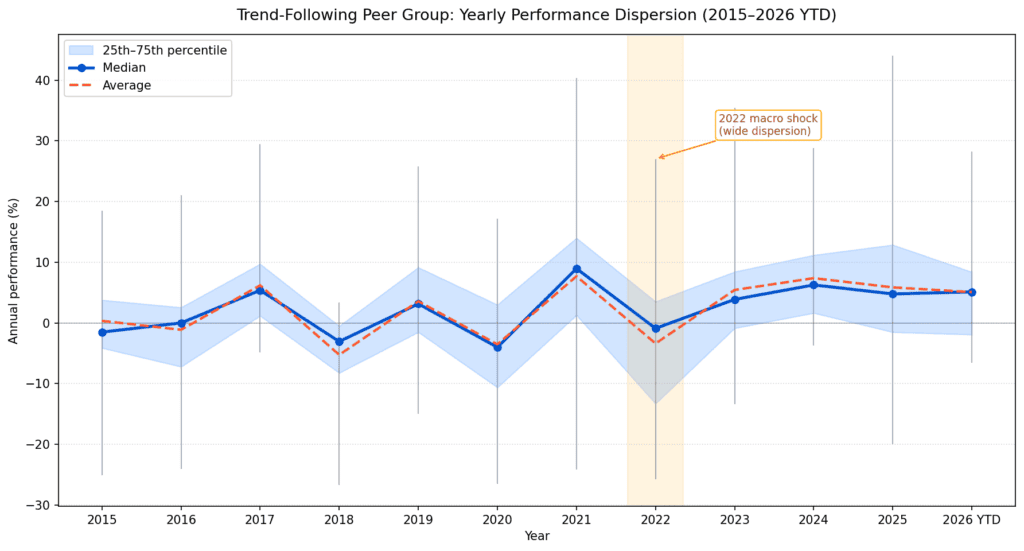
Average strategy performance is one of the most common shortcuts in portfolio research. It gives the researcher a clean benchmark, a single reference line, and a simple way to compare one strategy against a broader group of similar strategies. In many cases, this is useful. But it can also be misleading.
The problem is that an average hides dispersion. Two peer groups can have the same average return, but the internal structure of those groups can be completely different. In one year, nearly all strategies may behave similarly and cluster around the median. In another year, the same average may hide a wide spread between winners and losers. For portfolio construction, this distinction matters.
This case study shows how Quantpedia API can be used to go beyond the average peer group return and measure yearly performance dispersion across a group of trend-following strategies. The goal is not only to ask how the average strategy performed, but also how different the individual strategies were from each other.
https://t.co/9ef8Uqa16J
#benchmarking #trendfollowing #trading #strategies #peer #group
Boundaries of Time Series Momentum
Time-series momentum stands as one of the most reliable and heavily backtested anomalies in quantitative finance, serving as a foundational alpha source for modern managed futures and trend-following strategies. However, a recent academic paper by Matti Suominen and Erik Hjalmarsson, titled “Boundaries of Time Series Momentum,” uncovers a structural vulnerability that every practitioner must account for. The authors demonstrate that while equity market trends persist reliably during normal business cycles, they systematically break down and aggressively reverse when market valuations reach historical extremes. This phenomenon establishes clear macro “boundaries” where chasing the trend shifts from a highly profitable strategy to a severe drawdown risk.
https://t.co/7IANInAKVt
#momentum #trendfollowing #reversal #valuation #CAPE #bubble #managed #futures