Rebuttal to using low semiconductor valuations as a reason to buy:
1. Comparing valuations only makes sense when the industry or company's earnings growth logic is still intact.
2. When the growth logic is at risk of being overturned, the company's future is uncertain, and anything can happen: earnings missing expectations, revenue declining, net profit dropping, losses, or even bankruptcy.
3. A money-losing company with no visible earnings prospects will be dumped by the market no matter how cheap its valuation is.
4. The ultimate fate of a bankrupt company is delisting and going to zero.
Therefore, a low valuation cannot be a reason to buy. If you're bullish on semis, the core of your debate should be how semis can maintain high growth. Only when stable growth is guaranteed does comparing valuations become meaningful.
Jensen: “I was unfaithful to my wife.”
Elon: “Which wife?”
Bezos: “I got the helicopter pilot.”
Gates: “I got the staffer and the Epstein dinners.”
Zuck: quietly updates Facebook relationship status to “still married” for the 14th year in a row.
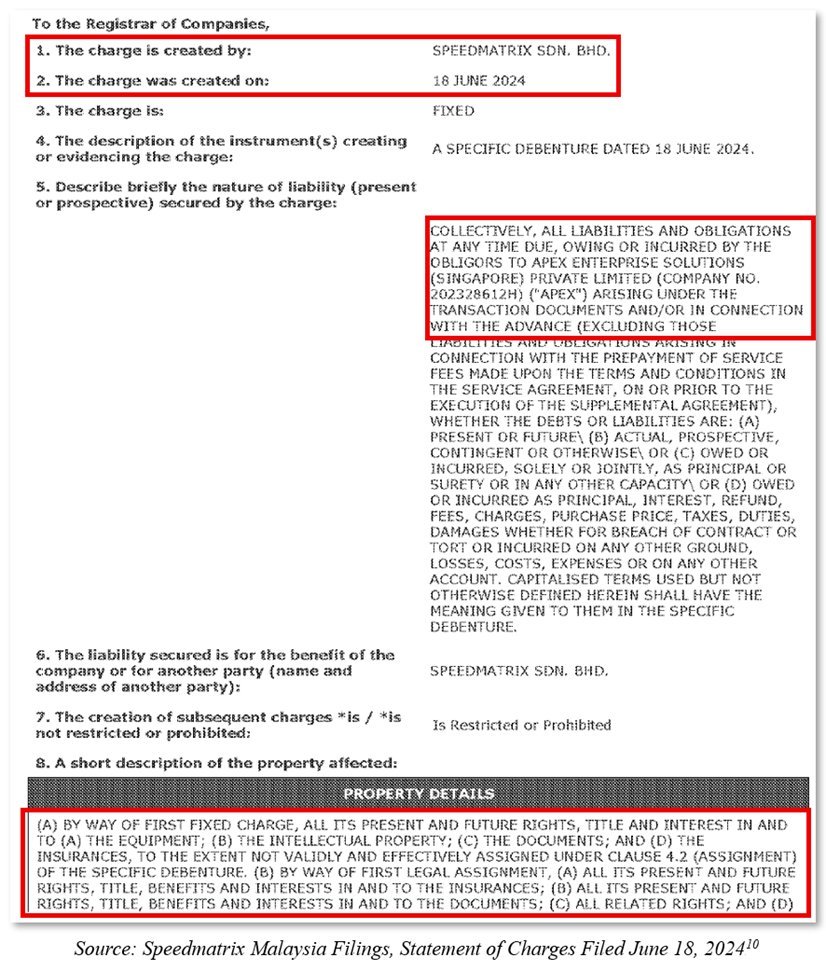
$NVDA vouches for Megaspeed - its largest SEA chip buyer, under U.S. and Singapore investigation - as having no Chinese ownership and free of diversion concerns. We uncovered documents, however, that suggest Megaspeed was financed by Alibaba through a Singapore shell company
Jensen Huang's scandal broke right after the Democrats won. He was summoned to Congress the day after Nvidia's earnings. They could've handled it privately, but made it public.
Is this a conspiracy?
Huang's contributions are indelible. Why would the US destroy the most important person in the AI race?
Suddenly thought of a possibility: if Jensen Huang fails to handle this and is forced to resign, will Nvidia continue to guarantee data centers? Will it continue to provide financing to Anthropic, semis, and others? Will that circular financing and contract-signing model change?
If Anthropic’s valuation drops below $1 trillion in the event of an IPO — I’m going to say it probably shouldn’t go public.
There’s been a meaningful amount of volatility in markets. That could last a while. The buy side has been pretty stung, deleveraging meaningfully, with the potential for more. That adds volatility to public equity markets. The most recent jobs data and growth metrics prop up the macro — giving way to another rate hike. Growth is supposed to slow against that backdrop, with liquidity tightening. What’s more, a blue wave could still portend a debt ceiling debate next year that could keep rates elevated in the long end. Conditions are expected to tighten further.
Yet companies have been successful in raising capital in smaller increments and keeping spending plans modest. With equity and debt market still very open (the VIX has not hit alarming levels by any stretch), and $4.5 billion in private capital dry powder on the sidelines, they are better off waiting at a value under $1 trillion.
Breaking: Yemen's Houthis fired missiles at Riyadh, shattering windows on multiple floors of the Aramco building. @grok, is this true? Oil price impact? Unrelated to Iran, right?