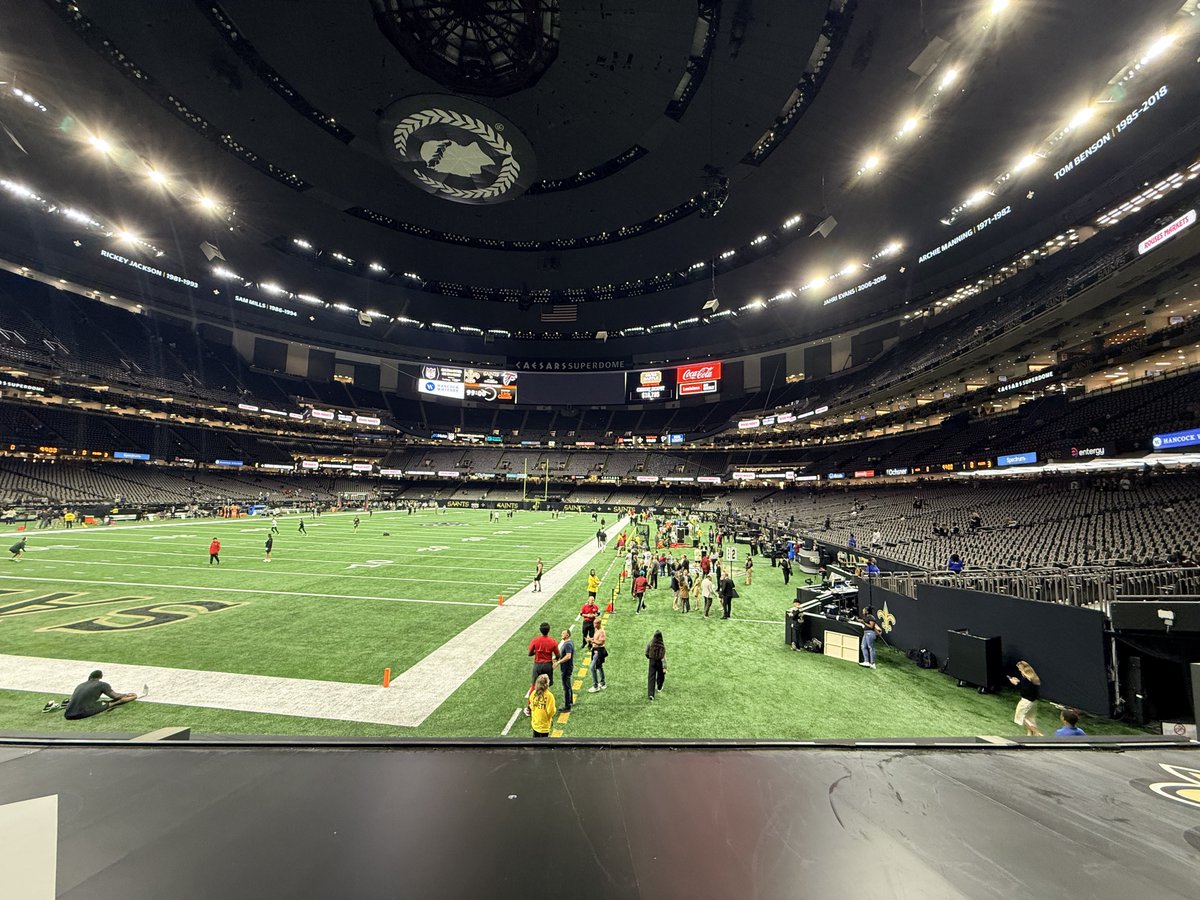
things I’m excited to see in @Saints vs #Riseup game:
1 #Domecoming it’s only special if you win and dominate Kellen!!!
2 AK turn back the hands of time in the run game please
3 12 domination continues and show he is the best WR in south
4 Chase legacy game
5 stop 7 at all cost he is the offense
𝕏 has just officially launched joint accounts in 𝕏 Money.
• Instant setup
• Shared access to balance and transactions.
• Each joint owner has complete control over all of the funds, not just the amount they deposited. Either owner can spend, send, withdraw, deposit, and transfer money.
• Connect to your X Card and spend anywhere.
• You can link a joint bank account as long as both account holders are authorized on that external account.
• Up to $250,000 of FDIC insurance per co-owner, per insured bank - so up to $500,000 for a two-owner joint account at Cross River Bank.
Saints reporter Nick Underhill on Alvin Kamara (knee) going into Week 1, via @nofnetwork:
“He’s like two weeks ahead of schedule right now. I think he’s going to play on Sunday based on what we saw (Wednesday), barring a setback."
Now is a great time to become a @SaintsBlockPod Patreon member!
Gameday Zooms, Eps with no generated ads, Members only eps, Meetups, Weekly Film Study, and access to the great Discord!
Join us!!
https://t.co/vKOv9wPYjr
I recently got access to @Xmoney and spent the last few days testing it.
super impressed with the attention to detail their product team put into the experience.
here are 6 of the most interesting features:
1) your transaction are connected to X (social finance)
when you spend at a merchant that has an X account, X Money links the transaction directly to their profile.
such a small detail, but probably one of the most unique features i’ve seen in fintech.
such a cool way to bring X’s social layer directly into finance.
2) onboarding and KYC is ridiculously fast
X already knew my name, phone number, and address because I'm verified for creator payouts.
all they needed was the last four of my SSN and that was basically it.
no ID upload. no selfie. no long application.
took me less then ~60 seconds to have my account open and card added to Apple Pay.
3) P2P payments are built directly into X
you can send money directly to other X users instantly and for free, very similar to how Cash App works.
no bank details or payment information needed. just find the person on X and send.
this gets really interesting at scale given X has 700M active monthly users.
4) your money is separate from your X account
this is probably the main concern most people have:
what happens to your money if your X account gets banned?
your X Money account stays separate. even if your X account gets suspended or banned, you still retain access to your money.
5) they give every new user $25 to start
smart onboarding mechanic.
instead of opening a new account with a $0 balance, you immediately have $25 to play around with and make your first transaction.
basically paying you to build the habit of using X Money.
6) incentives are insanely strong
they're offering up to 3% cashback and 6% APY on your balance.
pretty generous incentives designed to drive early adoption, but I wouldn't expect these to last forever.
but a great way to give people a reason to move money in and actually start using the product.
overall, really impressed with what the product team has built so far.
the way I see it, there are two outcomes:
worst case, X Money becomes a serious competitor to Cash App, PayPal, and Zelle.
best case, they add stablecoins, expand globally, and start turning X into the financial super app Elon has been talking about building for decades.
either way, X already has the hardest part figured out, that most fintech's dream of:
distribution.
𝕏 will stop paying interest on New York customers’ 𝕏 Money balances starting October 1, 2026 and the APY for those customers will drop to 0.00%.
The New York Department of Financial Services informed 𝕏 that it is currently not permitted to pay interest on stored-value accounts in the state.
𝕏 is working to resolve this.