@IRDA_OFICIAL@LICIndiaForever@nsitharamanoffc@RBI@FinMinIndia As an investor, I believe every ULIP holder should be able to easily access:
• Fund portfolio
• Historical NAV
• Unit movement details
• Charges
• Performance reports
Transparency builds trust.
RUN filed vide SRN AB1873871 on 16.11.2024 but still under processing.
Seriously, my client got tensed that how he will run his business in India this way!!
As a CS professional We did lots of commitment to run his business but sad, broken and down @MCA21India
Update on S.87A Rebate Issue-Favorable Order issued by Commissioner of Income Tax-Appeals, Pune!!
@CAKushalFofaria has presented exceptionally valid arguments in the appeal filed for his mother. His efforts deserve much appreciation 👍🙌
Here is the Summary of Arguments & link to the Order :-
🚨Rebate Restriction on Long-Term Capital Gains: Section 87A disallows rebate on long-term capital gains taxable u/s 112A, but no such restriction applies to short-term capital gains taxable u/s 111A or 115BAC(1A).
🚨Allowance under Section 115BAC: While Section 115BAC disallows certain deductions, rebate u/s 87A is not included in this disallowed list, making it allowable under Section 115BAC(1A).
🚨Definition and Computation of Total Income: As per Sections 2(45) and 14, total income includes all heads of income, including capital gains. The computation of total income is the summation of income from all these heads, explicitly incorporating capital gains.
🚨Budgetary Intent and Section 87A Amendment: The Budget Memorandum increased the rebate threshold from ₹5 lakhs to ₹7 lakhs as a beneficial measure. No restrictions were imposed on rebate for short-term capital gains on equity shares, aligning with the legislature's intent to extend this benefit without limitations.
🚨Rebate Based on Total Income Threshold: The total income of ₹6,93,260/-, being less than the threshold of ₹7 lakhs, satisfies the criterion for allowing rebate u/s 87A. The AO's disallowance of the rebate in this case was incorrect, as the income was within the eligible limit.
🚨Explanation of 'Subject to Chapter XII': The phrase "subject to Chapter XII" ensures that the tax on short-term capital gains on equity shares is computed at the 15% rate prescribed under Section 111A. However, this does not preclude rebate eligibility. Since these gains are part of "total income chargeable to tax" under Section 115BAC(1A), rebate u/s 87A is still allowable if total income remains below ₹7 lakhs.
🚨Settled Position of Rebate u/s 87A: Section 112A excludes rebate u/s 87A for long-term capital gains, while no such exclusion exists under Section 111A for short-term capital gains. This confirms the legislature's intent to allow rebate for short-term capital gains if total income is within ₹7 lakhs.
🚨Legislative Intent and Rebate u/s 87A: Section 112A explicitly excludes rebate u/s 87A for long-term capital gains, while no such exclusion exists under Section 111A for short-term capital gains. This shows the legislature's intent to allow rebate u/s 87A for short-term capital gains, provided the total income is within ₹7 lakhs. If a restriction was intended, a similar exclusion would have been added to Section 111A.
🚨Violation of Natural Justice in Rebate Disallowance The AO disallowed the rebate u/s 87A on short-term capital gains without issuing a show cause notice or providing the appellant an opportunity to be heard. This violates the principle of natural justice ("audi alteram partem") and settled legal norms, making the disallowance procedurally flawed.
🚨Prima Facie Adjustment Beyond Scope of Section 143(1) – Detailed Assessment Required: The AO disallowed rebate u/s 87A on short-term capital gains through prima facie adjustment under Section 143(1), which is impermissible for contentious issues. The eligibility of rebate, particularly for taxpayers not opting under Section 115BAC(6), requires judicial scrutiny and detailed assessment under Section 143(3) or 147, not summary adjustments under Section 143(1).
Link of Complete Order:-
https://t.co/TvGRUi8TgH
@IncomeTaxIndia@FinMinIndia Kindly revisit the matter seriously & provide a clarification or communication regarding the issue regarding rebate u/s 87A!!
गाजियाबाद के GST अफसरों ने कारोबारी को आंदोलनकारी बना डाला
मेरठ के अक्षय जैन की गाड़ी छोड़ने के बदले 1 लाख रिश्वत मांगने पर कारोबारी ने "नंगा अनशन" किया था.
वीडियो वायरल हुई तो GST ने अक्षय पर फर्जी केस दर्ज कराया
अक्षय पदयात्रा करते हुए लखनऊ रवाना हुए है.
CM योगी से मिलेगें
Incorrect interpretation of 87A has become a reality now. Again its the MIDDLE CLASS taking the hit!!
Sharing a case where a tax liability of ₹8K was processed as ₹29K due to incorrect interpretation of the law.
This issue could cost taxpayers (read MIDDLE CLASS) thousands of crores, particularly among individual & HUF taxpayers with rising market involvement in FY 23-24.
The law's intent has always been to support the middle class by providing a rebate up to ₹25K for those with total income under ₹7 lakhs(irrespective of normal or special rate).However, silently restricting this through the tax utility from 5th July, without any communication would classify this as a Financial blunder.
Request @IncomeTaxIndia@FinMinIndia Hon. FM @nsitharaman@nsitharamanoffc to revisit the intent of law-turn of events in below🧵 and control the situation before its gets out of hand 🙏🙏
Requesting tax professionals to revisit the thread whenever time permits, so the issue remains on radar and doesn't take the backseat.
Under GST, registration is rejected without any valid reasons, assessment orders are passed without applying mind, vehicles are stopped by officers with unsound mind
In this mindless game of corruption, use hashtag #MindlessGST and post your order/letter/notice and let's make a compendium of mindless GST regime
CAAS has submitted a detailed follow-up letter to Commissioner SGST, highlighting ongoing issues of harassment by SGST officials asking for alms.
We demand prompt action to protect stakeholders' rights.
Read more: https://t.co/Jd3cVEWdW0
#GST#TaxReform#Accountability#CAAS
Dear @IncomeTaxIndia
Thank you for all the troubles you give each and every year..
At the end of the day I find myself more commited to leave basic practice.
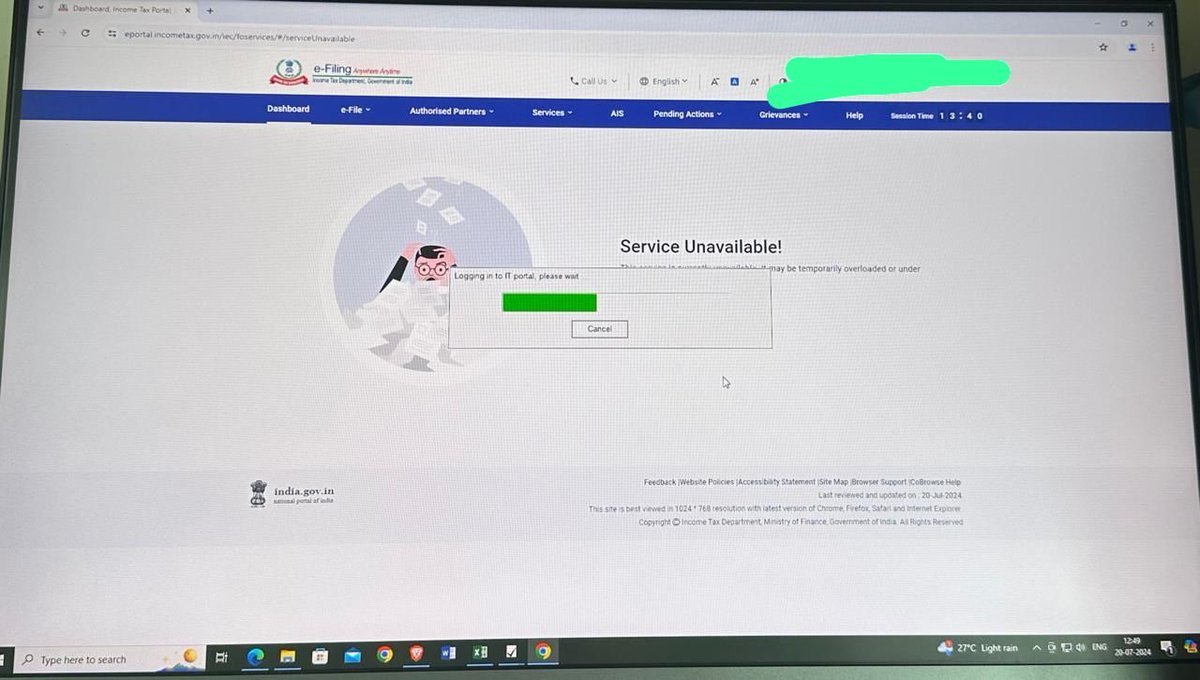
#Incometax_site_not_working
In 1940s, Men faked their age to be able to Fight in WW2.
In 2024, Boys can’t even write ✍️ against a faulty portal due to fear of being Politically incorrect.
Grow up Boys, Be a Men!!
#Incometax_site_not_working#IncomeTaxPortal
Requesting All Chartered Accountants, Tax Professionals and tax payers to trend #Extend_due_date_immediately if you are facing issues while working on @IncomeTaxIndia portal.
If mam @nsitharaman ji considers request to extend date, then you will get news on 31st July at night, so that as many as possible ITR can be filed &
if no extension then they should not levy any late fee in case of IT Portal Glitches, Retweet if you agree #incometax#caguruji
Dear @IncomeTaxIndia ,
Either provide us with a working portal or Extend the date to an undefined period.
Seems non working of portal is Intentional. Govt is being greedy for late fees.
Dear @IncomeTaxIndia
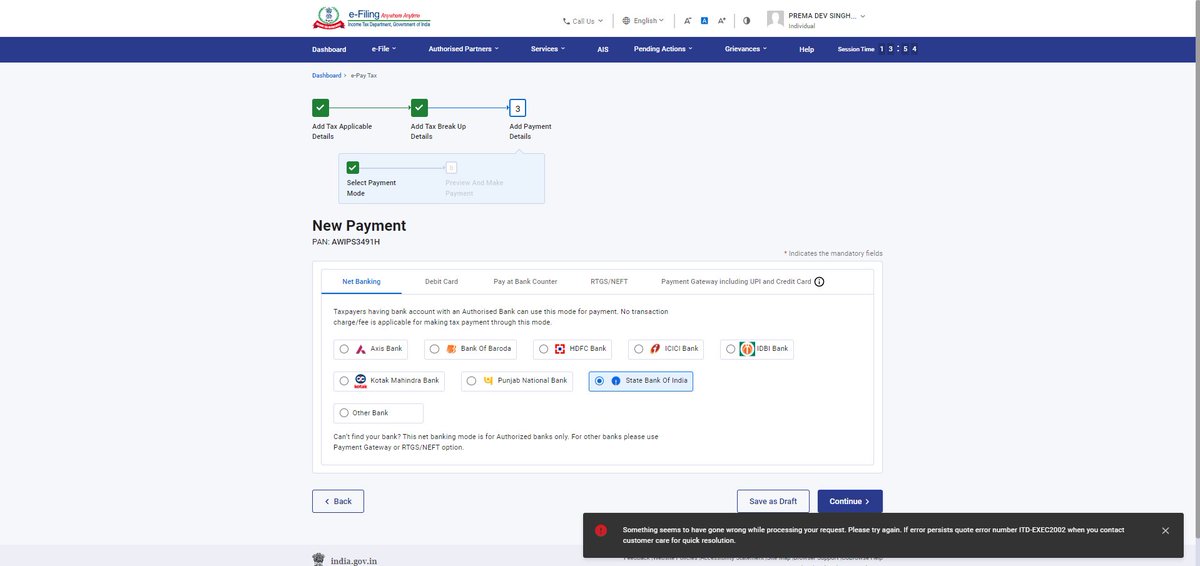
Income Tax Portal is not working properly
Unable to Download Acknowledgements after filing ITR
Unable to Import 26AS
Tax Payment Service not Working Properly
Kindly Extend the Due Date