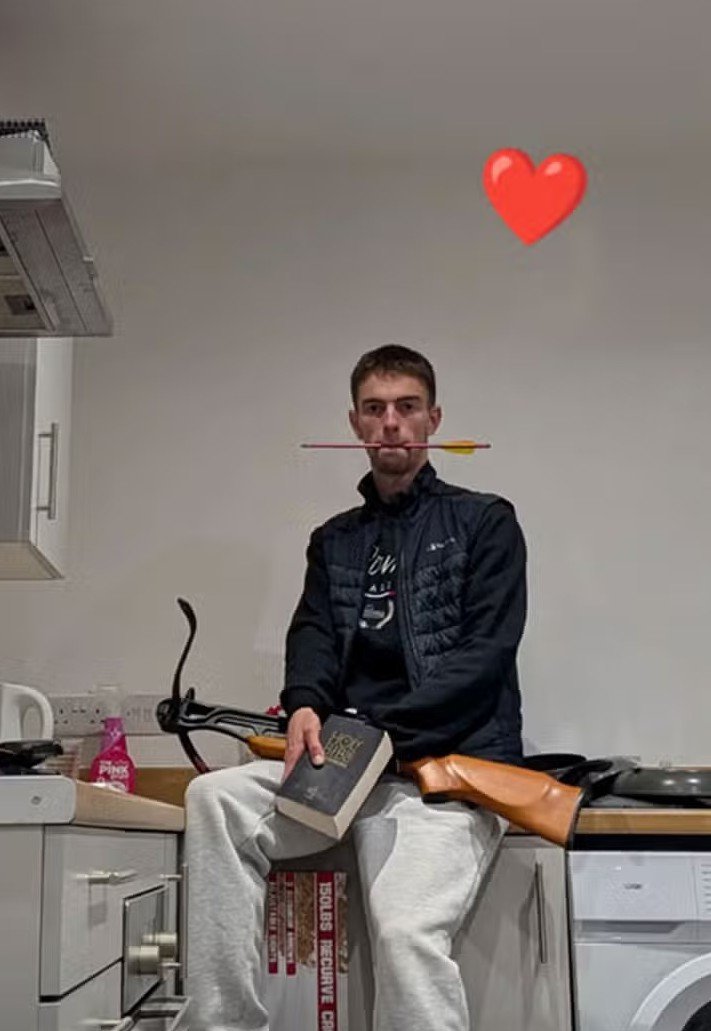
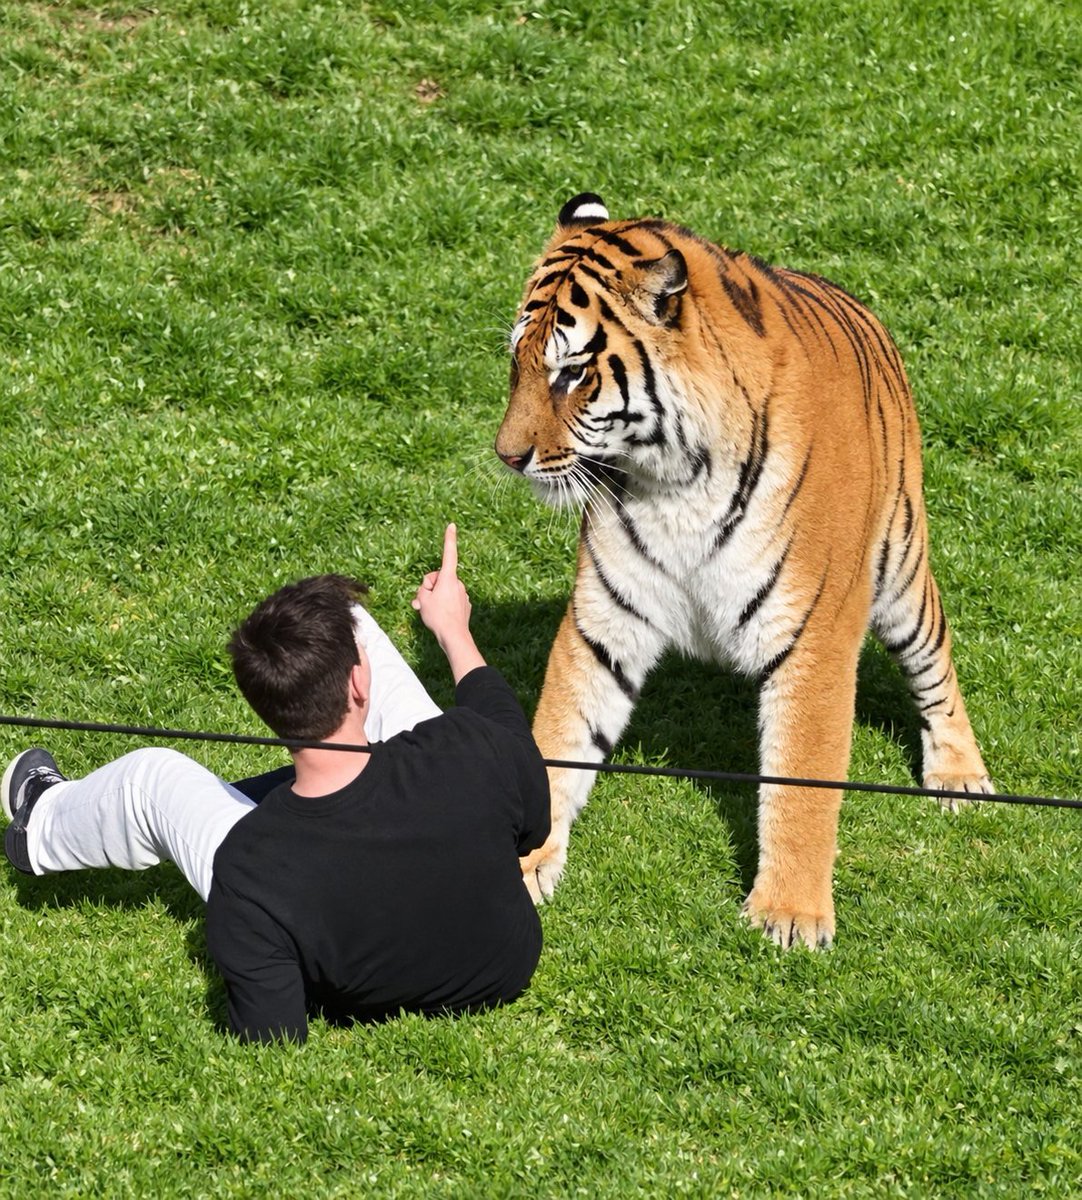
🚨 William Chapman's father. The man who was mauled by the tiger in Yorkshire, Northern England.
His father reveal that William was forced to take strong medication before entering the Tiger's enclosure.
Video 👇
Most companies already have agent data. They just don’t treat it like something that can pay.
Every time an agent collects a deposit, chases a late payment or swaps a faulty unit, they leave a trail. Who actually pays. Which neighbourhoods buy. Which agents move product and which ones just collect names. That trail can tell you who deserves a bigger loan, who is ready for the next product, and where a supplier should put stock next month.
The fastest money usually stays inside the network. Cleaner repayment data means fewer defaults and room for better commissions. Agents who prove they sell can get inventory financing instead of waiting on cash. External buyers (insurers, distributors) only become realistic once the records are clean and the agents still trust you enough to keep sharing.
The data is already there. The question is whether you have shaped it well enough to act on without breaking the local relationships that keep it coming.
Where would this make you money first—sharper decisions inside your own business or something you can sell outside?
Skills that compound in African tech and business are specific, not broad.
The highest-leverage ones are reading repayment and cash-flow patterns from mobile-money data, designing offers that survive agent commissions and daily payment friction, and inserting small automations that remove repeated manual hours.
Operators who can map real agent incentives, price against the cost of inaction, and keep unit economics visible outperform those who only optimise models or content.
Distribution still dominates pure technical skill. Understanding how M-Pesa flows, agent density, and customer cash cycles interact produces more durable results than additional certificates.
These skills appear in higher effective rates, lower churn, and cleaner data—not in course lists.
Which specific skill gap is currently costing you the most revenue or time?
Agent networks don’t scale because of ads. They scale because someone the customer already knows stands behind the product.
Sun King, M-KOPA and d.light recruit local people—shop owners, teachers, existing mobile-money agents—who live in the same community. These agents demo the kit, collect the deposit, and stay the first call when something breaks.
Trust sits in three places. The agent is known personally. The company backs them with remote locks, payment tracking and replacement stock so the agent isn’t carrying the risk alone. Neighbours who already paid and kept the light on create the social proof that makes the next person say yes.
When any of those layers slips—agent stops visiting, keycode arrives late, support vanishes after the last payment—the whole arrangement collapses faster than pure digital models.
How much of the trust in your market still comes from the local agent versus the company name?
Most sales and marketing still wastes time on volume. The useful work is narrower.
People chase more leads, more posts, more ads. Real gains come from fixing the few steps that convert: clearer offer, tighter qualification, faster follow-up, and proof that matches what the buyer already cares about.
AI helps most when it sits inside those steps—drafting, scoring, or reminding—not when it spits out more generic content.
In African markets the pattern is the same. Agent networks, mobile-money data, and existing relationships often beat broad digital ads because trust and reach are already there. Marketing that ignores how people actually buy (cash, agents, referrals) underperforms even with better tools.
The bottleneck is rarely awareness. It is the handoff from interest to paid.
Where does your process leak the most right now—getting attention or turning interest into a decision?
Are you a student, graduate, or remote job seeker who genuinely needs a breakthrough? 😔
I have compiled about 27 opportunities consisting of:
✅Current Scholarships
✅Paid internships
✅ Remote jobs
✅ Dollar-paying platforms and online earning opportunities
Eligibility requirements and application links included!
Đứng trước quả cỗ siêu to khổng lồ mà da hà mã nó dày quá, gặm thử mấy phát bất lực luôn ae ạ :))
Chúa sơn lâm đoạn này nhìn ngơ ngơ đúng kiểu "miếng ăn đến miệng rồi mà vẫn không xong".
Innovex AI is Hiring a Virtual Assistant (Remote)!
An interior design business is looking for a part-time Virtual Assistant.
✅ Experience in customer service and administrative support
✅ Strong English communication skills
✅ Social media management (Instagram)
✅ Content creation and sales support
🕒 28 hours/week | 11 AM–3 PM Melbourne time (core hours)
📅 Deadline: October 31, 2026
📩 Apply: Send your application to [email protected]
Africa’s fintech grew by making cash move. AI will grow by making those same rails smarter.
Mobile money already moves roughly $1.4 trillion a year across the continent. That transaction history is the raw material most markets still lack. Lenders, insurers, and logistics platforms are starting to use it for scoring, fraud detection, and credit decisions instead of relying only on formal bank records.
The constraint is not model access. It is clean data, reliable power for inference, and people who can wire AI into existing payment and agent networks without breaking unit economics. Pure chatbots add little. Tools that sit inside M-Pesa flows, agent workflows, or SME cash-flow data do.
Fintech created the volume. AI that improves repayment, reduces fraud, or speeds up lending on top of that volume is the next practical layer.
Where do you see AI actually changing fintech operations in your market right now?
Sometimes, I sit down and wonder if I’m doing enough with my life. I see people winning, making money, and moving forward while I’m still trying to figure things out. But deep down, I know my journey is different. God, please let my efforts pay off someday. 🙏
The AI bubble is mostly noise around models and valuations. The real work is quieter.
Most money is still chasing the next big model or chatbot. The durable demand is simpler: tools that actually reduce hours, catch errors, and fit inside the software people already use.
In Africa the constraint is sharper. Compute is expensive, so the edge is not training giant models. It is using smaller ones on local data and wiring them into payments, logistics, or farm operations that already have volume.
Wrappers get squeezed as base models get cheaper. Companies that own the workflow or the data tend to keep the value.
Where are you seeing AI that actually sticks in your market—inside existing processes or as something new?
There’s More to Life:
Sometimes, we’re so busy chasing money and trying to become successful that we forget to enjoy the life we’re working so hard for. Make time to live, laugh, rest, and create beautiful memories too.
Kenya’s credit bureau integration
Kenya runs a formal Credit Information Sharing system supervised by the Central Bank of Kenya. Three licensed Credit Reference Bureaus—TransUnion, Metropol and Creditinfo—collect and share borrower data from banks, microfinance institutions, SACCOs and licensed digital credit providers.
Licensed lenders must submit both positive and negative information. Negative listings usually require a minimum amount (around KSh 1,000) and prior notice to the borrower. Records are linked to the national ID, so history follows the person across phones or SIMs. Lenders query the bureaus during underwriting and often combine the data with alternative signals such as M-Pesa activity. Scores typically range from roughly 200–900. Negative information remains for five years after the debt is settled.
Since the 2021–2022 reforms, Central Bank-licensed digital credit providers must report to the bureaus. This includes major platforms such as M-Shwari, Fuliza, Tala and Branch. The growth in licensed digital lenders has increased the volume of short-term loan records in the system. Unregulated lenders are barred from submitting data.
Positive repayment can improve access to formal credit. Defaults on small digital loans, however, appear on the same reports that banks use, which has raised concerns about listings for minor arrears. Data quality still varies because not every lender submits complete or timely records, and coverage of informal activity remains incomplete. Borrowers can check and dispute their reports.
The system is moving from simple blacklisting toward scored files that mix traditional and digital-loan data. Integration works best where lenders are licensed and submit clean records. Gaps remain in consistency of submission and in how much weight short-term digital performance receives relative to longer formal credit history.