Since April, a small team inside Metaplanet has been working on something we could not talk about. Today it is public.
Metaplanet is taking a controlling stake in Super League Enterprise (Nasdaq: SLE). At closing it will be renamed Superplanet, our U.S. Bitcoin treasury platform, seeded with 2,100 BTC of our own Bitcoin and consolidated into our group.
Here is what it means.
In two years, Metaplanet became one of the largest corporate Bitcoin treasuries in the world, listed in Japan and backed by shareholders around the world, from Japanese retail investors to global institutions. Every decision has run through one question: does it increase Bitcoin per share? This one is no different.
America is the deepest capital market in the world, and it is home to something that exists nowhere else at such scale: investors who fund Bitcoin treasury companies with permanent capital, no maturity, no repayment, no dilution of common shareholders. Until now, our group had no way to issue into that market. Superplanet gives us a direct presence in it.
So the strategy now runs on two engines. Superplanet raises in America. Metaplanet raises in Japan. Both feed a single Bitcoin position that never leaves the group. When Superplanet raises capital without adding common shares, Bitcoin per share rises there and at Metaplanet at the same time. Two markets, two currencies, two investor bases, one balance sheet compounding.
The platform opens doors in both directions. Superplanet can acquire in the U.S. Bitcoin treasury sector in ways not available to a Japanese parent. And in time, subject to laws and regulations, our securities arm may bring Superplanet securities to investors in Japan.
We seeded this investment with less than 5% of our Bitcoin, with the ability to contribute much more as the platform grows. And we structured it the way long-term owners should: we invested at the market price, no discounts, no special terms, locked up every share for five years, and ranked our entire position behind the investors who will fund Superplanet's future. Our capital, our balance sheet, and everything we have learned building Metaplanet stand behind this platform.
Super League brings a Nasdaq listing and a decade of relationships with many of the world's largest brands across gaming, an audience that understood digital value before most of the world did. There is real chemistry between that community and what we are building.
Closing is expected in Q4 2026, subject to customary closing conditions, including Super League stockholder approval.
Japan gave us our foundation. America gives us our second engine. One Bitcoin position, compounding through the world's two deepest capital markets.
We are very pleased to welcome Jesse Myers @Croesus_BTC. Jesse joins Super League now and will lead Bitcoin treasury strategy as Chief Investment Officer of Superplanet once our transaction closes and the company joins the Metaplanet group.
Jesse is a well-known Bitcoin analyst and author, widely respected across the industry and best known for his Full Potential Valuation framework. At SWC in the UK, he helped develop its perpetual preferred offering.
I recently spent several days with Jesse in New York, and I’m confident his experience, strategic clarity and relationships make him an excellent addition to the Metaplanet family.
Superplanet’s goal is to grow Bitcoin per share over time. Super League has said it intends to issue perpetual preferred equity in the US after closing, subject to Board approval and market conditions, and Jesse will lead that work. $SLE
Excited to announce that I will be joining @Superplanetinc to lead Bitcoin strategy as Chief Investment Officer, pending transaction close.
Right now, the company is known as Super League (Nasdaq: $SLE), but will become Superplanet upon completion of the proposed transaction, becoming a controlled subsidiary of Metaplanet.
The stated mission of Superplanet is simple: launch a perpetual preferred instrument in the US and pursue an Amplified Bitcoin strategy, with the backing of Metaplanet as a parent company with ~44,000 BTC.
Right now, Super League has 39 BTC. Upon deal close with Metaplanet, the company will have 2,139 BTC and a pathway to rapidly scale from there. We are on the launchpad for that journey, and with Bitcoin now on sale.
Today, I am excited to officially join CEO @matt_edelman and the excellent Super League team around him to help bring that vision to reality with the support of the Metaplanet team, including @gerovich and @DylanLeClair.
In terms of Bitcoin strategy for Superplanet, we intend to deliver shareholder value by growing Bitcoin per share via 1) amplification and 2) accretive transactions.
Much more to come on all that – I’m incredibly excited about the setup for Superplanet and look forward to committing my full focus to sending this thing interplanetary.
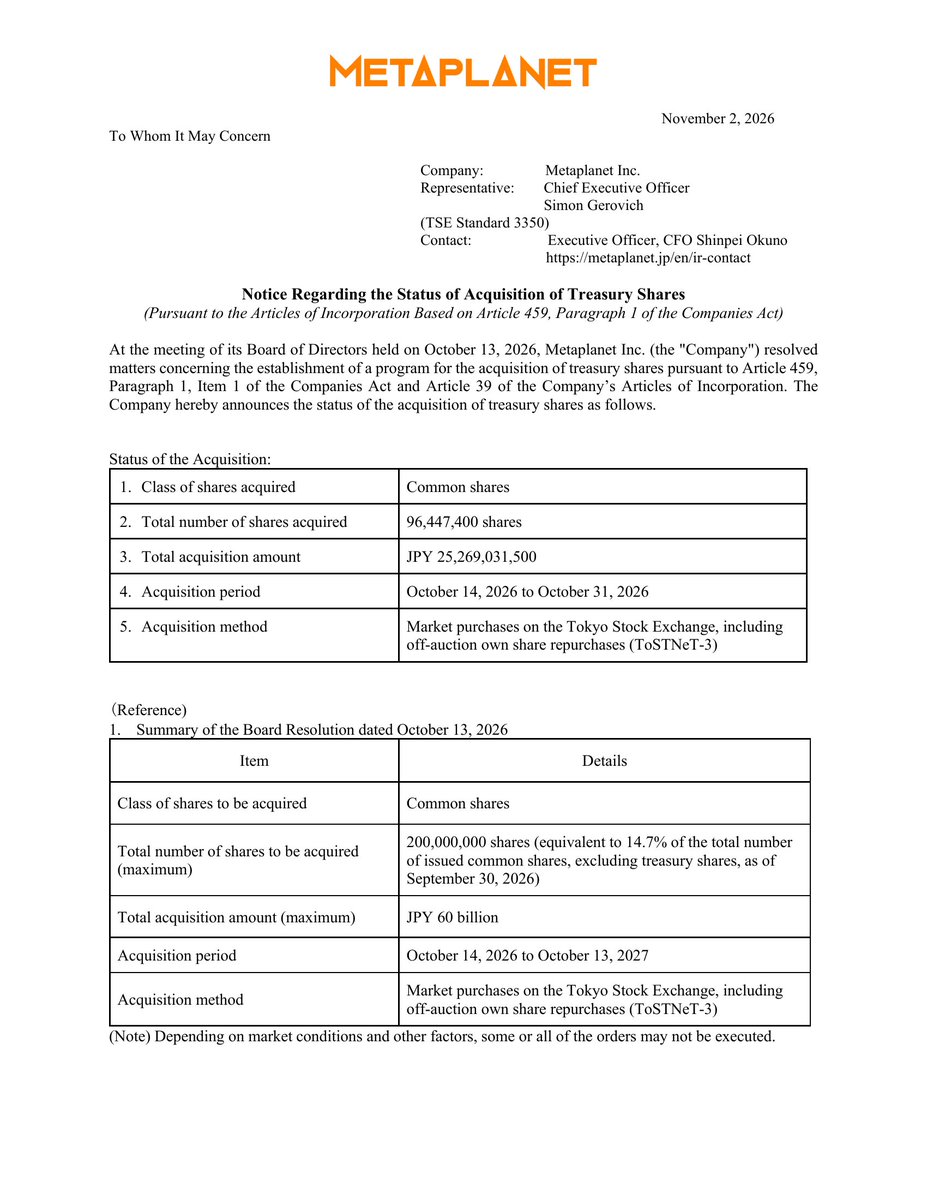
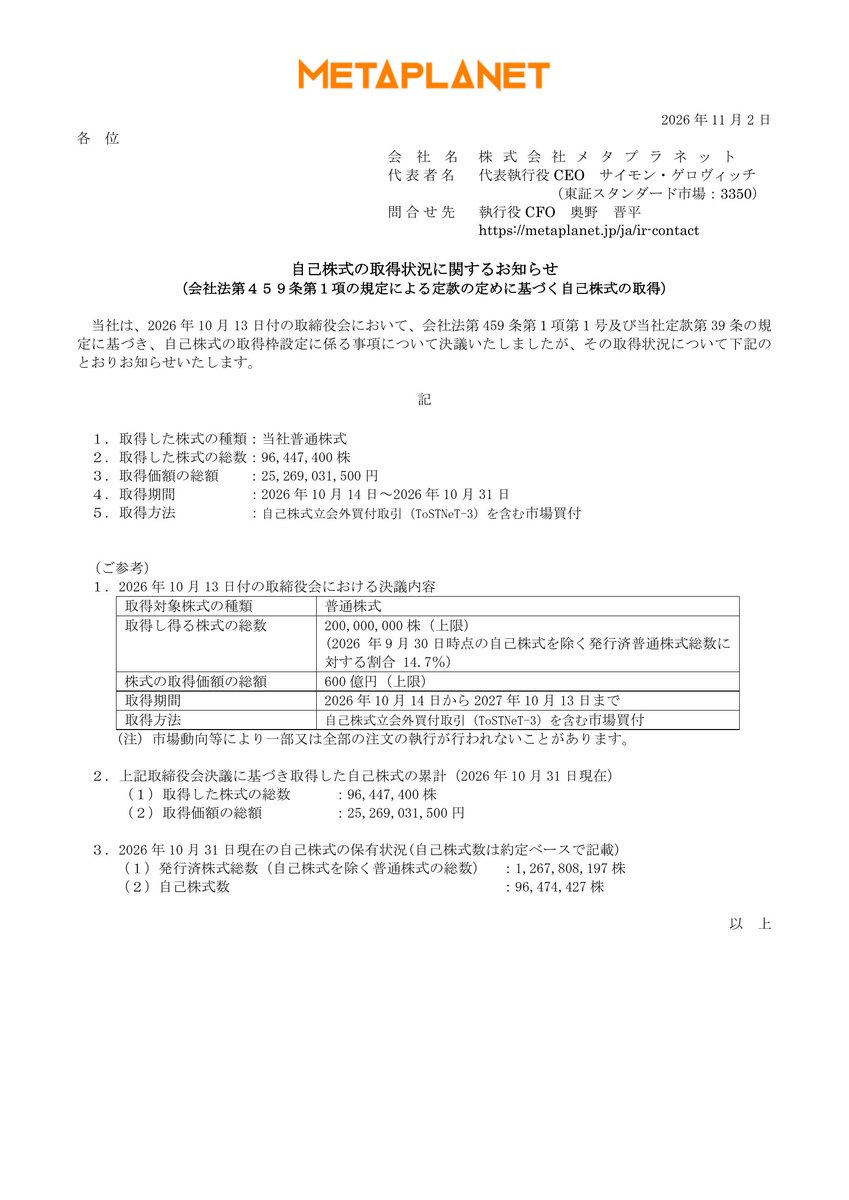
From October 14 to 31, we bought back 96,447,400 shares, about 7.1% of our total issued shares, for ¥25.27 billion.
We will continue to allocate capital with discipline, focused on maximizing bitcoin per share and taking into account our share price, mNAV and market conditions.
We stand with Binance and everyone working around the clock on this. As one member of this industry, we know moments like these are when we need to come together.
Bitcoin itself is unaffected. The network continues to run exactly as designed, as it has every block since 2009.
All of Metaplanet's bitcoin is held in cold storage with best-in-class regulated custodians.
Super League stockholders have approved every proposal at last week's annual meeting, including:
✅ Issuance of common stock and warrants to Metaplanet
✅ Name change to Superplanet, Inc. ($SLE -> $SUPA)
✅ Increase in authorized preferred shares from 10m to 100m
At closing, Metaplanet will contribute 2,100 BTC + $2.5m USD in exchange for 44.86m common shares, 100 shares of Strategic Alliance Preferred Stock, and common stock warrants representing up to ~$3.4b of potential equity capital.
Based on the ~3.0m Super League shares outstanding as of September 29, Metaplanet would own ~93.7% of Superplanet's common stock at closing. All shares to be held by Metaplanet are subject to a five-year lock-up.
The Strategic Alliance Preferred carries no preferred dividend or liquidation preference; its purpose is governance. While Metaplanet holds it, Metaplanet's consent is required for charter amendments, mergers or changes of control, and designation of a board majority.
As outlined in the proxy, Superplanet intends to grow BTC per share primarily by issuing senior, non-convertible perpetual preferred stock rather than debt.
Metaplanet will also hold a 24-month right to subscribe for up to $210m of unlisted Junior Liquidity Support Preferred Stock. If issued, it would pay SOFR + 4.00% and rank junior to any senior preferred Superplanet may issue, allowing Metaplanet to provide subordinated capital in support of the balance sheet.
A new chapter begins soon. 🇺🇸🪐
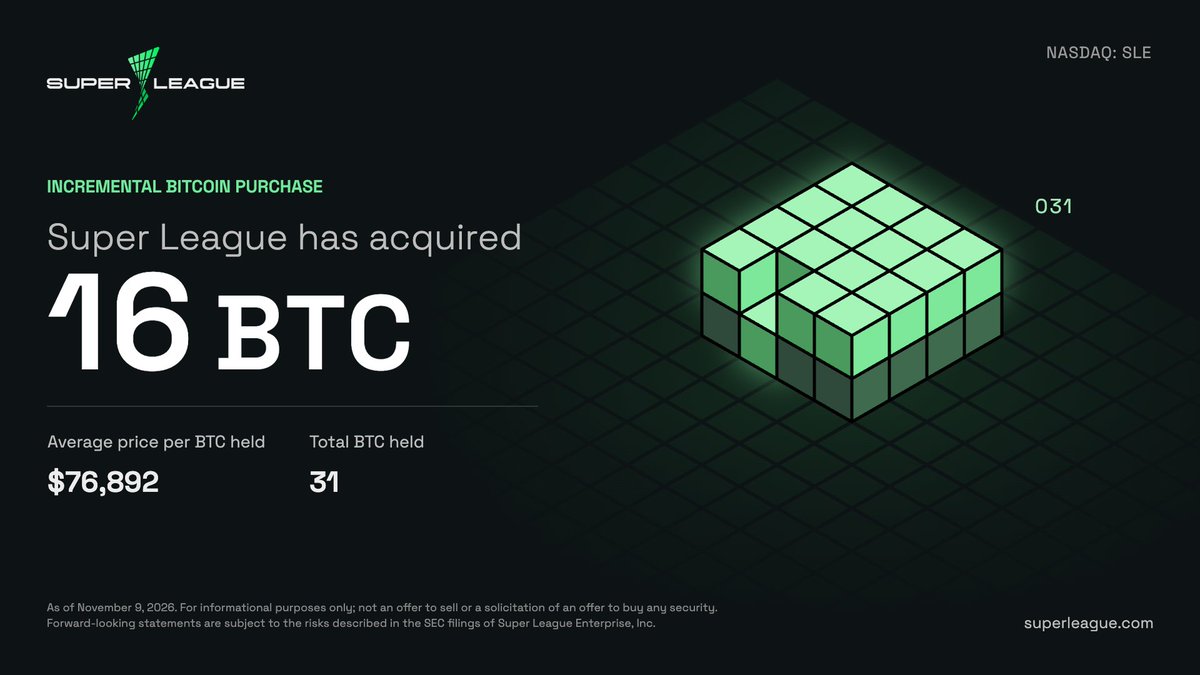
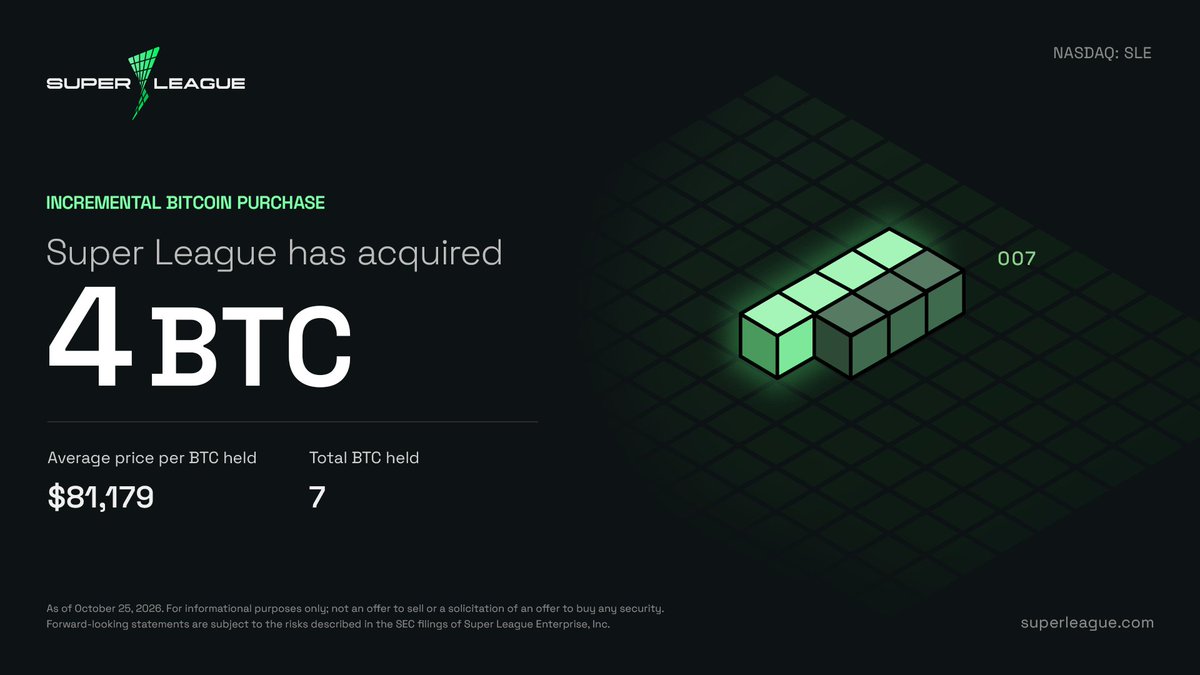
Super League has completed its second Bitcoin purchase.
We added 2 Bitcoin to our treasury, doubling the size of our inaugural purchase.
Following our Annual General Meeting of Stockholders on Friday Oct 16th, we find ourselves hungry for more!
We are pleased to note that Super League ($SLE) shareholders have voted to approve the proposed Metaplanet transaction, an important step in our transformation from a Bitcoin treasury company into a global Bitcoin-native financial platform.
Upon close, Superplanet will be our U.S.-listed Bitcoin treasury platform, providing direct access to U.S. capital markets and greater flexibility to opportunistically raise capital.
Together with Metaplanet Securities in Japan, we will have complementary platforms in two of the world’s most important capital markets, enabling us to raise and deploy capital internationally while advancing our ambitions across Bitcoin treasury, financing, financial products and asset management.
This is another exciting milestone as we build for the long term. Stay tuned for more as we move towards close.
Super League stockholders have approved every proposal at last week's annual meeting, including:
✅ Issuance of common stock and warrants to Metaplanet
✅ Name change to Superplanet, Inc. ($SLE -> $SUPA)
✅ Increase in authorized preferred shares from 10m to 100m
At closing, Metaplanet will contribute 2,100 BTC + $2.5m USD in exchange for 44.86m common shares, 100 shares of Strategic Alliance Preferred Stock, and common stock warrants representing up to ~$3.4b of potential equity capital.
Based on the ~3.0m Super League shares outstanding as of September 29, Metaplanet would own ~93.7% of Superplanet's common stock at closing. All shares to be held by Metaplanet are subject to a five-year lock-up.
The Strategic Alliance Preferred carries no preferred dividend or liquidation preference; its purpose is governance. While Metaplanet holds it, Metaplanet's consent is required for charter amendments, mergers or changes of control, and designation of a board majority.
As outlined in the proxy, Superplanet intends to grow BTC per share primarily by issuing senior, non-convertible perpetual preferred stock rather than debt.
Metaplanet will also hold a 24-month right to subscribe for up to $210m of unlisted Junior Liquidity Support Preferred Stock. If issued, it would pay SOFR + 4.00% and rank junior to any senior preferred Superplanet may issue, allowing Metaplanet to provide subordinated capital in support of the balance sheet.
A new chapter begins soon. 🇺🇸🪐
Metaplanet announced ¥52b of zero-coupon Euro-yen convertible bonds due 2031, together with a concurrent share repurchase. Terms are now final, and the initial repurchase was completed this morning.
The conversion price is ¥339, a ~30% premium to the reference share price and above 1.0x mNAV at launch.
Through ToSTNeT-3, we repurchased 73,981,400 shares at ¥261, a discount to NAV, for a total of ¥19.3b, or roughly 5.4% of shares outstanding.
A further ¥23.6b will partially repay our credit facility, releasing bitcoin currently pledged as collateral and giving us greater flexibility to execute on our upcoming strategic initiatives.
The remaining ~¥9bn allocated to repurchases can go toward further share buybacks in the market and/or additional facility repayment.
I think it’s important for me to address one pivotal piece of our convertible bond financing, which you will see noted in the full legal notice and in the presentation deck. I'm lending up to 55 million of my own shares to support the deal at 0.75%, which is well below the current market rate. I want to explain why, because there is a simple reason.
Convertible bonds are bought by institutional investors who carefully manage their risk. A convertible combines a bond with the right to convert debt into shares later at a set price. Many investors value that equity component but hold it on a balanced, market-neutral basis rather than betting on where the share price goes.
To do that, they need to be able to borrow shares. The more shares available at a competitive price, the lower the borrowing cost and the more investors are willing to pay Metaplanet for the bond. If you want to go deeper, ask any AI how stock borrowing costs affect convertible bond pricing.
Stock borrowing and lending are standard parts of convertible financing around the world and directly impact pricing. When borrowing shares is difficult or expensive, the issuer gets less favorable terms. When shares are readily available and cheap, terms improve. For Metaplanet that means a lower cost of capital and less dilution for existing shareholders.
That's why I'm lending shares from my own holdings below the market rate – to help Metaplanet secure the best terms available and to help make this financing a success. The lending arrangement was reviewed and approved by the independent directors of Metaplanet, with me recused from the decision.
Today Metaplanet announced that it will issue ¥52bn of zero-coupon Euro-yen convertible bonds due 2031, together with a concurrent share repurchase.
These initiatives are interconnected. The issuance funds the repurchase of our shares at a discount to net asset value, reduces secured borrowing, and releases bitcoin currently pledged as collateral – all with debt that carries no regular interest payments.
I need to limit my comments because, as the bonds are not being offered in the U.S., we are highly constrained in what we can communicate from a regulatory perspective.
But today’s announcement serves an important purpose at this time. Up to ¥28.3 billion of proceeds will be used to repurchase our shares as part of our ¥60bn repurchase program. Up to ¥25.3 billion of this will be executed through an off-auction block trade (ToSTNeT-3) this morning, up to 96,934,800 shares, or 7.1% of shares outstanding, with the balance through market purchases. With our shares trading below the value of our bitcoin holdings, buying them back at these prices captures that discount for shareholders.
Conducting the repurchase concurrently with the bond offering also helps absorb trading activity associated with convertible investors hedging their positions, supporting better pricing for the bonds. Any funds not used during the concurrent repurchase will be applied to subsequent share repurchases or to the repayment of our credit facility.
A further ¥23.6bn will be used to partially repay our credit facility, releasing bitcoin pledged as collateral. This gives us greater financial flexibility to acquire more bitcoin while advancing other strategic initiatives, including our Net Interest Income Strategy.
The initial conversion price is set at a premium to both the current share price and 1.0x mNAV at launch. So, we are buying back shares below the value of our bitcoin holdings, while new shares would only be issued upon conversion at a price above that value.
The bonds are yen-denominated, senior unsecured obligations being placed with international investors that are non-U.S. persons exclusively outside the United States, broadening our investor base. They are supported by our balance sheet and credit rather than specific collateral.
Our total debt will increase, but its composition will improve. Secured, interest-bearing borrowing is replaced with unsecured, non-interest-bearing debt. The result is lower interest costs, a longer tenor on our borrowings, a meaningful repurchase of outstanding shares at a discount, and greater credit capacity to execute our strategic initiatives.
Separately, as announced on August 18, our investment in Super League Enterprise (Nasdaq: SLE) is expected to close shortly, subject to SLE shareholder approval and other closing conditions, after which SLE will be renamed Superplanet, Inc. I will have more to say about that at closing.
For more information, see here the full legal notice in English: https://t.co/QaRchVIcG2 and a presentation deck that describes the issuance and repurchase succinctly: https://t.co/BoH7ShhEbD