Data analyst for 16 years. Quit my Silicon Valley job to build with AI once work became financially optional. Notes on spending, investing, and wealth. 👇🏾
I quit my cushy tech job after working as a Data Analyst for the past 16 years. I was able to do this, because I spent those years building a solid financial foundation and learnt how to make money work for me, so the job became optional.
I started from almost 0, ten years ago when I moved to the US from India.
If you want to learn how I did it and what I learnt, follow along.
@CJL5000 at 4% SGOV wins. So no point moving.
At 6% X money wins, and it makes sense to move assuming the limits work. However I dont have a direct deposit and paying $40 a month is not worth it for the amount I would move into it.
X Money pays 6% on your savings. Getting $200,000 (house down payment) back out can take 27 months.
I read the fine print so you don't have to.
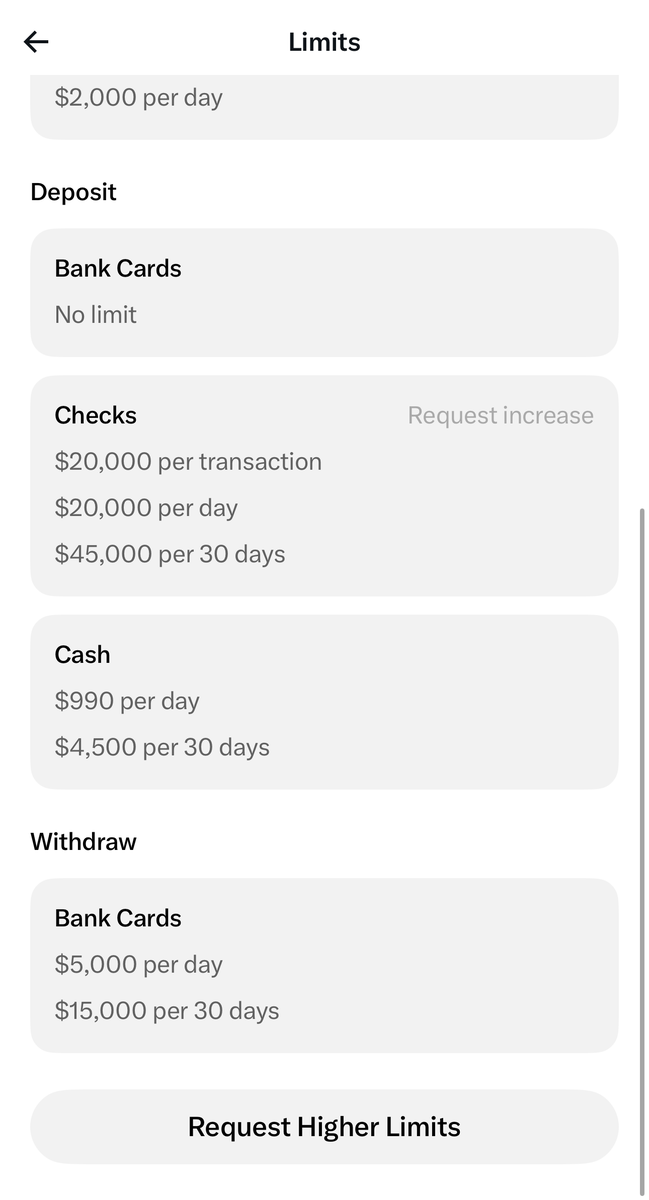
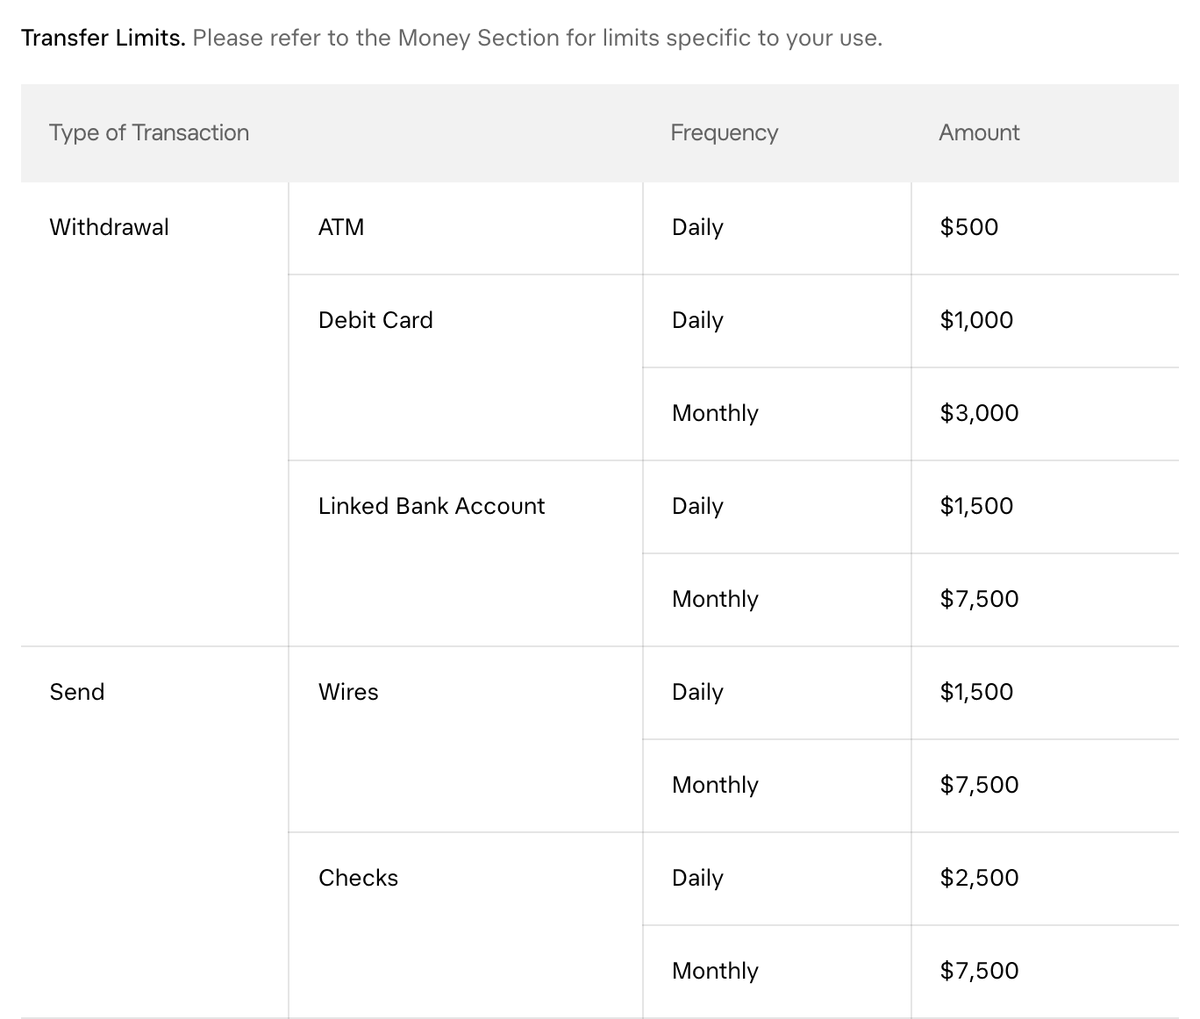
By default, X lets you move $1,500 a day and $7,500 a month back to your bank. That's the whole catch, and it matters more than the rate.
I looked because @ZackStacksKap were discussing whether X money is better than SGOV (where I keep my savings). 6% vs about 4% on money parked anyway? Hard to say no.
Then the strings:
• The $8 Premium plan doesn't get 6%. You need $1,000 of paychecks landing there in the past 34 days, or Premium+ at $40 a month.
• Moving your own savings in doesn't count.
• Paying for Premium+ just for the rate only wins above $27,000 to $75,000, depending on your state tax.
• Wires and checks are capped too. The fast way out is an instant transfer at 1.75%: $3,500 on $200,000. (erasing most of the benefit compared to SGOV)
• New York residents earn 0%.
Your limits may be higher than the defaults. Check the app before you move the money, not after.
Picking an emergency fund by the highest APY is a mistake. The first question is how fast you can get it back when you need it.
Would you (or have you) moved yours for 6%? Did you read the fine print?
I wrote about it in my essay below. 👇🏾
@cook449662 You should check your limit on X Money once you create the account. The limits are likely to be higher (their T&C is quite restrictive unnecessarily) @XMoney fyi
@ZackStacksKap@CJL5000 Friends, thank you for sharing your insights on this. I have now updated the essay to account for it and have tagged you in it for your contributions.
Thank you both!
I was considering using it. However, it is not applicable to me as moving money from one account to other doesnt count (I dont have a steady income stream given I left work). They require new money.
Curious, why they wont make it more clear in their terms that the amount someone can take out can be higher? As a new user, it deters them.
Also, why would you want to have to ‘work’ on activity to get higher limits?
Yes. I use YouTube for 3+ hours most days, between music while driving and watching videos.
Assuming a 30-second ad every 5 minutes, that's about 18 minutes of ads a day. Roughly 9 hours a month.
Would I pay $27 to skip 9 hours of ads?
Absolutely.
Also, btw I use Amex platinum so they cover $25 of youtube premium every month (which I anyway was paying). So it helps.
Reasons why I like Amex platinum in case you are interested: https://t.co/tGoM9Z7LS4
The limits are from the "Transfer Limits" section of X Money's own account agreement: https://t.co/zYihTeoOT3
Rates and who qualifies for 6%: https://t.co/Mfc5B0Xskz
@AboundWealth@Olympusperspect Really? I didnt think robinhood platinum was worth it. Specially because i already have other premium travel cards. Also upgrade isnt worth it. 3% on everyday is so good already
@drp825_ When you can cash flow your expenses through your investments, you are free. Everything else is just cushioning that to support your future generations.