Today, #AMRQ has been added to the FTSE Small Cap and FTSE All Share indices.
The auction to implement this is happening today, with the changes taking effect on Monday.
This is when tracker/index funds that need to hold AMRQ (because it's now in these indices) will buy in.
My best guess is that this auction could see volume of around 5% of Issued Share Capital, roughly 20-23 million shares; a potentially significant one day liquidity event, since none of the big tracker-fund managers (L&G, BlackRock etc) currently hold AMRQ and would need to buy from scratch rather than reallocate.
There is some confusion because there's a mix-up between this event and the FTSE 250.
AMRQ has not been added to the FTSE 250 - that's a separate, larger index with its own quarterly review cycle.
The next review decision point for FTSE 250 inclusion is December 2026, with the indicative review published 24 November 2026.
Basically, strap in. 🚀
#BRES Charles Archer (@that_stocks_guy) has published a strong recap of the Beehive maiden JORC and the step-change in scale to 64.3Mt, the only 22% modelled upside angle, & the relevance of downstream/offtake pathways.
Read his article below:
https://t.co/O1ufuwkuzt
So let’s look closer at #EPP EnergyPathways
Progressing and not reliant on the gas storage license:
World’s Largest CAES project (UK’s largest LDES): Based on the storage capacity, output duration and benefitting from massive curtailed wind energy, estimates for revenue pa are around £150m+ (may be higher with cavern expansion and government subsidy or cap and floor benefits)
The Irish Sea has two huge wind farms to come online in the shape of Mona and Morgan. So expansion of the salt caverns with Siemens Energy is likely. Also EPP own the IP for CAES tech.
The project lifespan is 25 years+ so LDES alone is a company maker.
Reliant on Gas Storage License:
Gas Production: Marram alone has 46BCF of gas, based on current spot pricing that’s worth £500m (this doesn’t include Knox or Lowry fields) the figure will be a little lower due to the provision of cushion gas needed to facilitate storage.
46BCF is just natural gas and doesn’t include nitrogen in the mix which will be utilised to create clean ammonia.
Gas Storage: Marram alone has the equivalent storage capacity of Centrica’s Rough Facility 50-60BCF
The revenue value of gas storage is based not just on gas in place, but the opportunity for volatility trading (fill with cheap summer gas to sell on winter peaks)
Based on Marram alone annual revenues are approx £400m+ (but based on the UK’s low gas storage capacity this is conservative)
Hydrogen/Ammonia: This is a harder market to asses as an emerging sector. So based on the initial projected feedstock of 20,000 tonnes let’s value it when it’s used to create Ammonia as that market is very real.
Production of 110,000 tonnes pa is projected. The last domestic UK ammonia producer closed in 2023 and as of 2027 there’ll be a border levy on imports so this will affect chemical & farming Industries. Annual revenues for ammonia, based on volatile pricing could be between £55-100m pa.
Graphite: High grade synthetic Graphite (circa 60,000 tonnes pa) is set to be refined (With Mitsui Japan) to create nuclear/military grade graphite, elevating the price dramatically. Company estimates revenues of £500m pa
EnergyPathways has a suite of revenue streams offering diversification through products and industries at a time where they’ll be the only domestic producer of graphite and ammonia, they’ll effectively be doubling the UK energy storage capacity at a time of critical need and urgent demand. And it requires little or no government funding (however GB Energy or National Wealth Fund may invest)
The offering is also diverse enough to be valuable to any government from Labour to Reform so it is in effect apolitical. (Is Reform going to turn down homegrown North Sea gas, domestic graphite for defence and Ammonia for Jeremy Clarkson and the farming community?)
The tier one partnerships with Siemens Energy, Wood & Costain give the project credibility in the eyes of the government, as does the fact the world’s and UK’s largest CAES/LDES facility is going ahead at pace and it makes the project very real.
MESH is proposed as the flagship project for EPP and Siemens and “one of many” projects that will target favourable geology/infrastructure in the North Sea Continental Shelf.
The risk was that the storage license wouldn’t be granted… But that is now a thing of the past 👏🏻
The second argument is that “it’s not operating until 2030, so why buy now”, the counter is that at £12m MCAP, when project level funding hits and now the GSL is granted and the government and media takes up the story this stops being worth £12m.
The project will no longer be a “retail” focussed stock and with projected yields for investors to be 25% per annum over a 25 year lifespan then pension funds, institutions and family offices take over the register, and they invest for significant and sustained future growth not a quick 10% slice.
So let’s look closer at #EPP EnergyPathways
Progressing and not reliant on the gas storage license:
World’s Largest CAES project (UK’s largest LDES): Based on the storage capacity, output duration and benefitting from massive curtailed wind energy, estimates for revenue pa are around £150m+ (may be higher with cavern expansion and government subsidy or cap and floor benefits)
The Irish Sea has two huge wind farms to come online in the shape of Mona and Morgan. So expansion of the salt caverns with Siemens Energy is likely. Also EPP own the IP for CAES tech.
The project lifespan is 25 years+ so LDES alone is a company maker.
Reliant on Gas Storage License:
Gas Production: Marram alone has 46BCF of gas, based on current spot pricing that’s worth £500m (this doesn’t include Knox or Lowry fields) the figure will be a little lower due to the provision of cushion gas needed to facilitate storage.
46BCF is just natural gas and doesn’t include nitrogen in the mix which will be utilised to create clean ammonia.
Gas Storage: Marram alone has the equivalent storage capacity of Centrica’s Rough Facility 50-60BCF
The revenue value of gas storage is based not just on gas in place, but the opportunity for volatility trading (fill with cheap summer gas to sell on winter peaks)
Based on Marram alone annual revenues are approx £400m+ (but based on the UK’s low gas storage capacity this is conservative)
Hydrogen/Ammonia: This is a harder market to asses as an emerging sector. So based on the initial projected feedstock of 20,000 tonnes let’s value it when it’s used to create Ammonia as that market is very real.
Production of 110,000 tonnes pa is projected. The last domestic UK ammonia producer closed in 2023 and as of 2027 there’ll be a border levy on imports so this will affect chemical & farming Industries. Annual revenues for ammonia, based on volatile pricing could be between £55-100m pa.
Graphite: High grade synthetic Graphite (circa 60,000 tonnes pa) is set to be refined (With Mitsui Japan) to create nuclear/military grade graphite, elevating the price dramatically. Company estimates revenues of £500m pa
EnergyPathways has a suite of revenue streams offering diversification through products and industries at a time where they’ll be the only domestic producer of graphite and ammonia, they’ll effectively be doubling the UK energy storage capacity at a time of critical need and urgent demand. And it requires little or no government funding (however GB Energy or National Wealth Fund may invest)
The offering is also diverse enough to be valuable to any government from Labour to Reform so it is in effect apolitical. (Is Reform going to turn down homegrown North Sea gas, domestic graphite for defence and Ammonia for Jeremy Clarkson and the farming community?)
The tier one partnerships with Siemens Energy, Wood & Costain give the project credibility in the eyes of the government, as does the fact the world’s and UK’s largest CAES/LDES facility is going ahead at pace and it makes the project very real.
MESH is proposed as the flagship project for EPP and Siemens and “one of many” projects that will target favourable geology/infrastructure in the North Sea Continental Shelf.
The risk is that the storage license won’t be granted… But that would require the government to decline something they critically need and requires little or no taxpayer subsidy. They’d have to have a damn good reason to decline.
The second argument is that “it’s not operating until 2030, so why buy now”, the counter is that at £12m MCAP, when project level funding hits and the GSL is granted and the government and media takes up the story this stops being worth £12m.
The project will no longer be a “retail” focussed stock and with projected yields for investors to be 25% per annum over a 25 year lifespan then pension funds, institutions and family offices take over the register, and they invest for significant and sustained future growth not a quick 10% slice.
@TheCryptoSquire I bought in via Coinsilium PLC set up
A Saft with yellow in April 2022 bought in at 0.004c and have 50 million tokens on balance sheet. They hold 182, BTC and the market cap is £15m trades in US on OTC $CINGF & #coin on Aquis in UK. That's well over 10x and it's not priced in 🔥
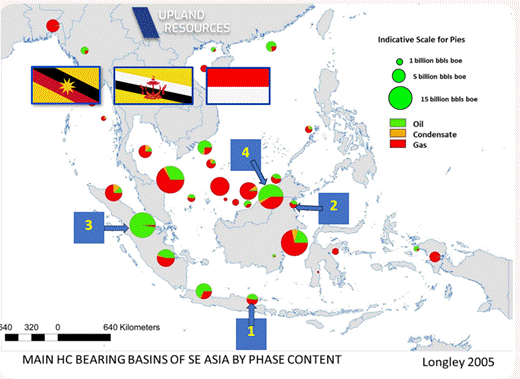
This will be huge: @Uplandtweets, Marc Bruner & @LostSoldierOilG
✅️ ~6Tcf Wild Mustang natural gas
✅️ >5bboe across Borneo & Indonesia
✅️ $13.8m bilateral investment
✅️ $100m drill funding
✅️ 30% project farm in
🔥"developments...years in the making"🔥
#UPL#UPLLF
Defence Holdings PLC were today delighted and honoured to have been invited to No10 by Jade Leung, Special Adviser on AI to the Prime Minister, where our CTO Andy McCartney discussed the future of AI in Defence and the importance of building sovereign UK capability.
#ALRT
#HEX#HELIUM
Helix has achieved first production.
I interview CEO Bo Sears, where it becomes clear - we're just getting started.
https://t.co/L5GwANdBjh
#ALK
Glencore offtake secured, owned site secured, another big offtake pending and a fight to fund it
Newsflow:
£200m funding
Big offtake in the pipeline
Gov support?
£1b+ lithium refinery in the UK largest and cheapest in the west and potentially the world
£40m cap 🤔 bod own 40% of the float
#PREM #KOD #ZNWD #EMH #GLEN
#HEX is now Montana’s first #Helium producer! 🇺🇸
Gas flowing from Linda, Weil & Darwin wells, with Inez to follow post-testing.
🔹Offtake talks progressing
🔹Scaling toward full capacity
🔹Transition to revenue underway
RNS: https://t.co/jfxShcIL7J
What a week for @Uplandtweets!
✅️ £2mil raised at a premium
✅️ £1.5mil to BoD & geologists
✅️ Direct & exclusive PSC negotiations
✅️ 9 billion boe YTF, >500mil 2C boe in place & >1.5 trillion 2C cubic feet gas
🔥THE most exciting oil & gas play for 2026🔥
#UPL
It really is exciting times for @Uplandtweets :
✅️ "Exclusive" SE Asia opportunities
✅️ Multi-year drilling programme preapred
✅️ Farm in & funding arrangements confirmed
✅️ Targeting: c.5 billon boe
🔥 "developments which have been years in the making"🔥
#UPL
#UPL
$100m funding secured!
Over 5Bn barrel prospect!
10 drills per year!
https://t.co/XuGSLjXefD
Not hust Elephant Fields but MEGA ELEPHANT sized fields. That's all Billionaire Marc Bruner ever does...
What makes 2026 the TRANSFORMATIONAL year for @Uplandtweets:
✅️ Lost Soldier first gas production 6Tcf
✅️ Profit share
✅️ Indonesia licene
✅️ Brunei licence
✅️ Sarawak licence
✅️ UBDS regional hub
🔥 "developments which have been years in the making"🔥
#UPL
#BRES Major new #Graphite deposit confirmed at Iyan. Deep-hole drilling delivers continuous mineralisation to ~100m, all holes end in graphite
🔹High-grade intercepts up to 13.9% TGC. Supports early 2026 JORC upgrade
🔹 Beehive deep holes + more Iyan to come
Read More Here: https://t.co/hbX83zDh32
#BRES Exceptional first deep hole at newly identified Iyan deposit confirms continuous high-grade graphite from surface to ~100m
Major new zone not in current JORC, strengthening Orom-Cross’ potential as a multi-decade supply source. 5 more deep holes + 186 assays pending
Read More👉https://t.co/a96jpXgeEw
🎙️#BRES CEO Mike Ralston with @proactive_x
🔹US$1.087Bn NPV & 96% IRR
🔹More drill results, JORC expansion & off-take updates to follow
🔹Presenting the DFS at Resourcing Tomorrow show🇬🇧
Next stop: New York & Washington for #CriticalMinerals meetings 🇺🇸