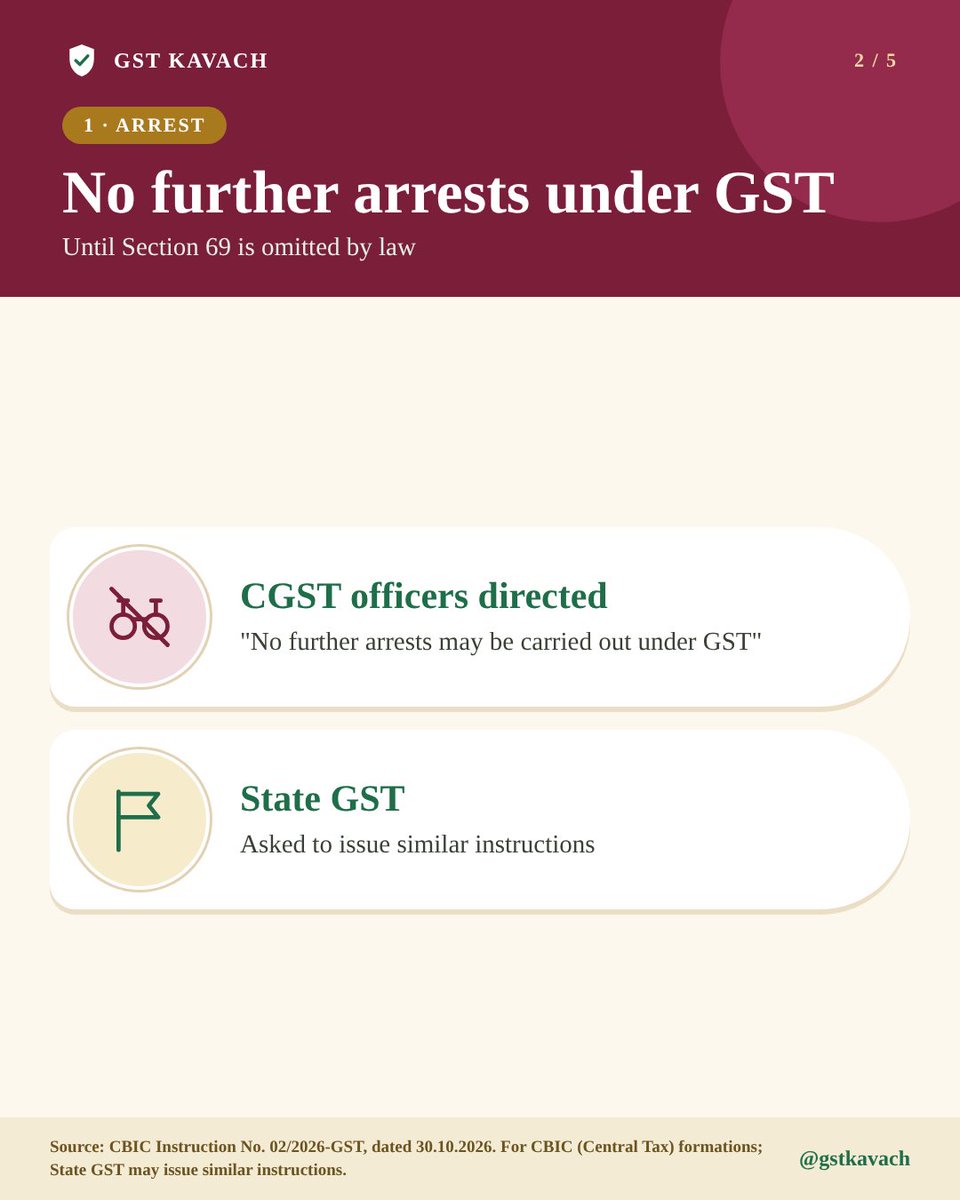
🚨 CBIC Instruction 02/2026-GST (30.10.2026), in force now:
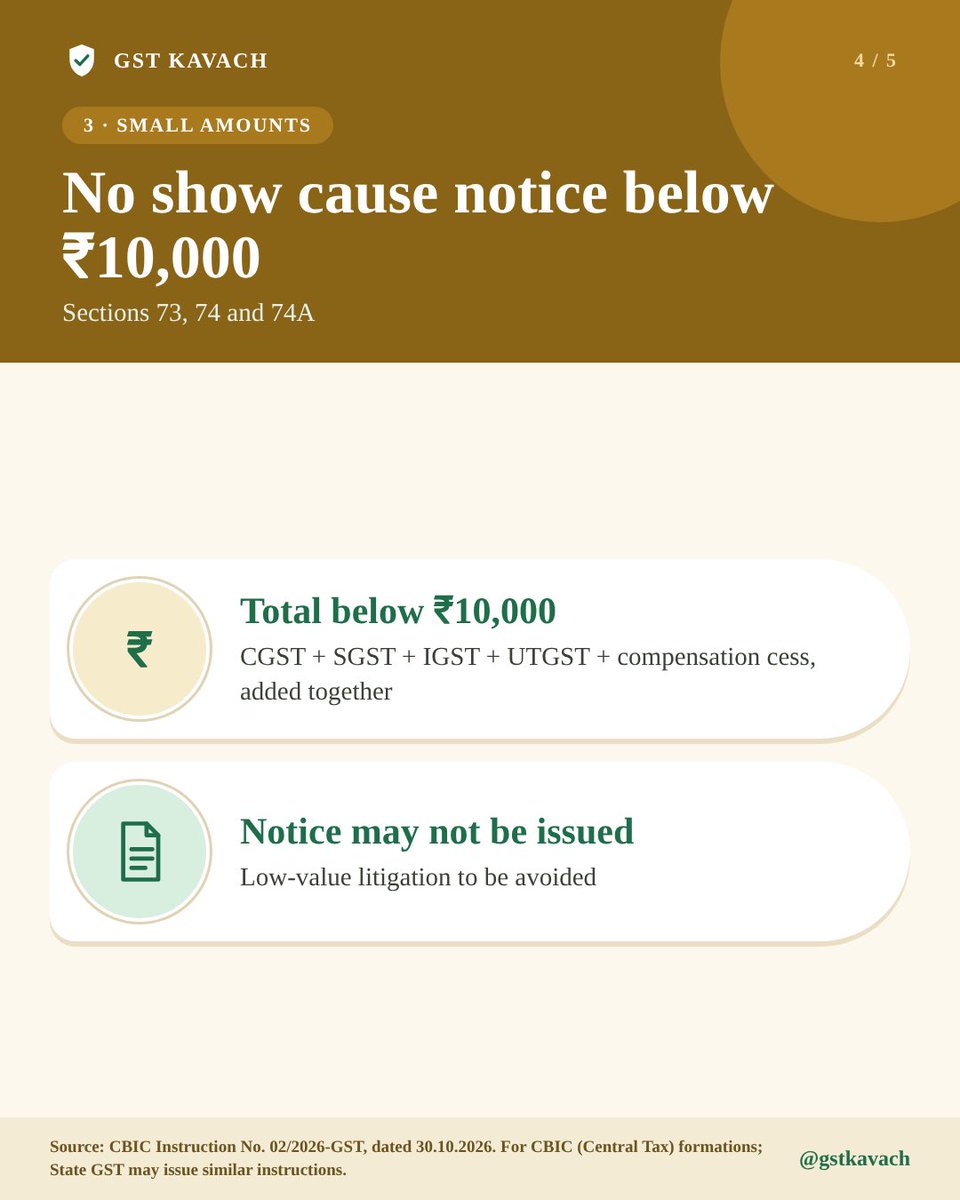
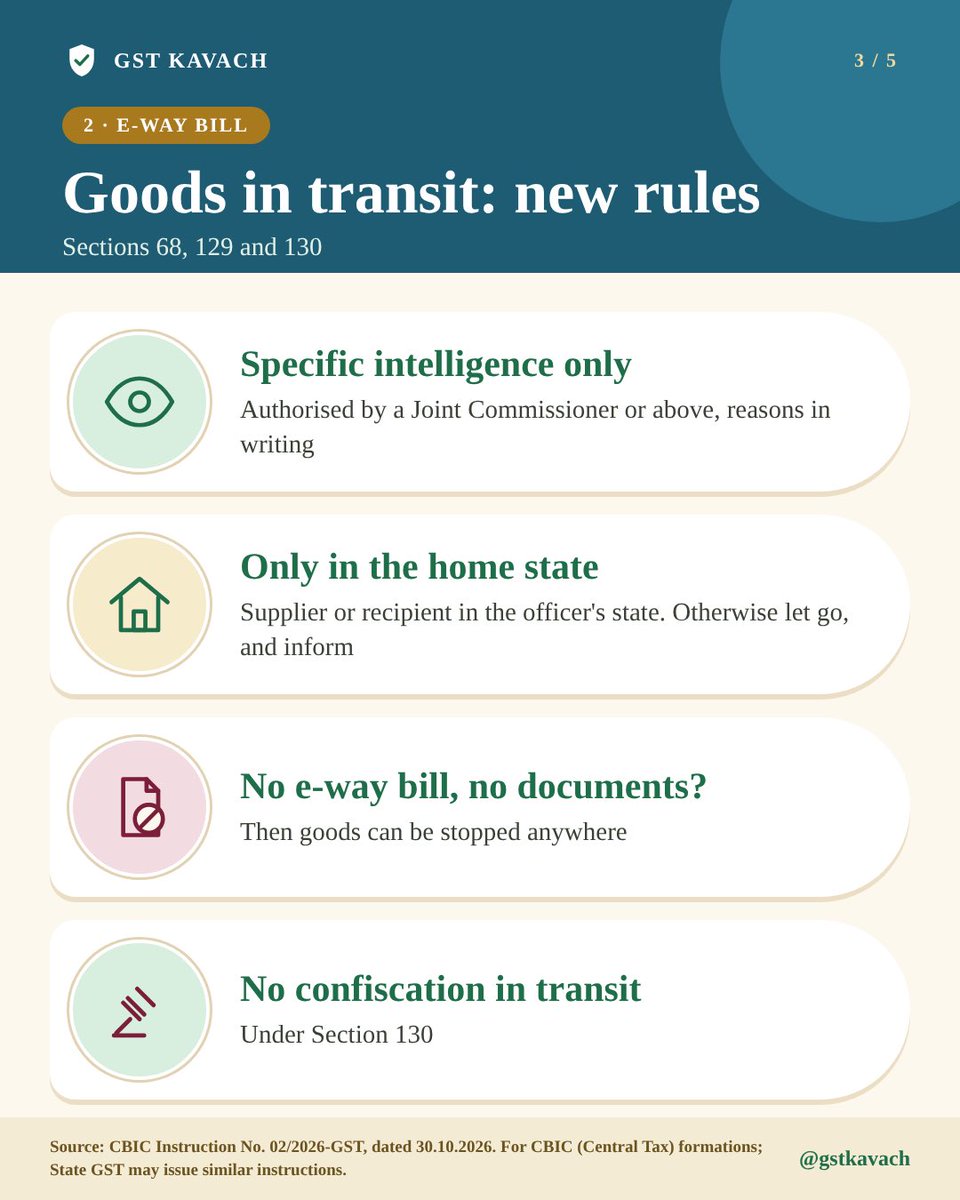
1️⃣ No further arrests under GST 2️⃣ E-way bill: goods stopped only on specific intelligence (JC+ approval) 3️⃣ No SCN if total tax is below ₹10,000
Notice mila?
https://t.co/MRx27GdQex
#GST#GSTArrest
🚨 CBIC Instruction 02/2026-GST (30.10.2026), in force now:
1️⃣ No further arrests under GST 2️⃣ E-way bill: goods stopped only on specific intelligence (JC+ approval) 3️⃣ No SCN if total tax is below ₹10,000
Notice mila?
https://t.co/MRx27GdQex
#GST#GSTArrest
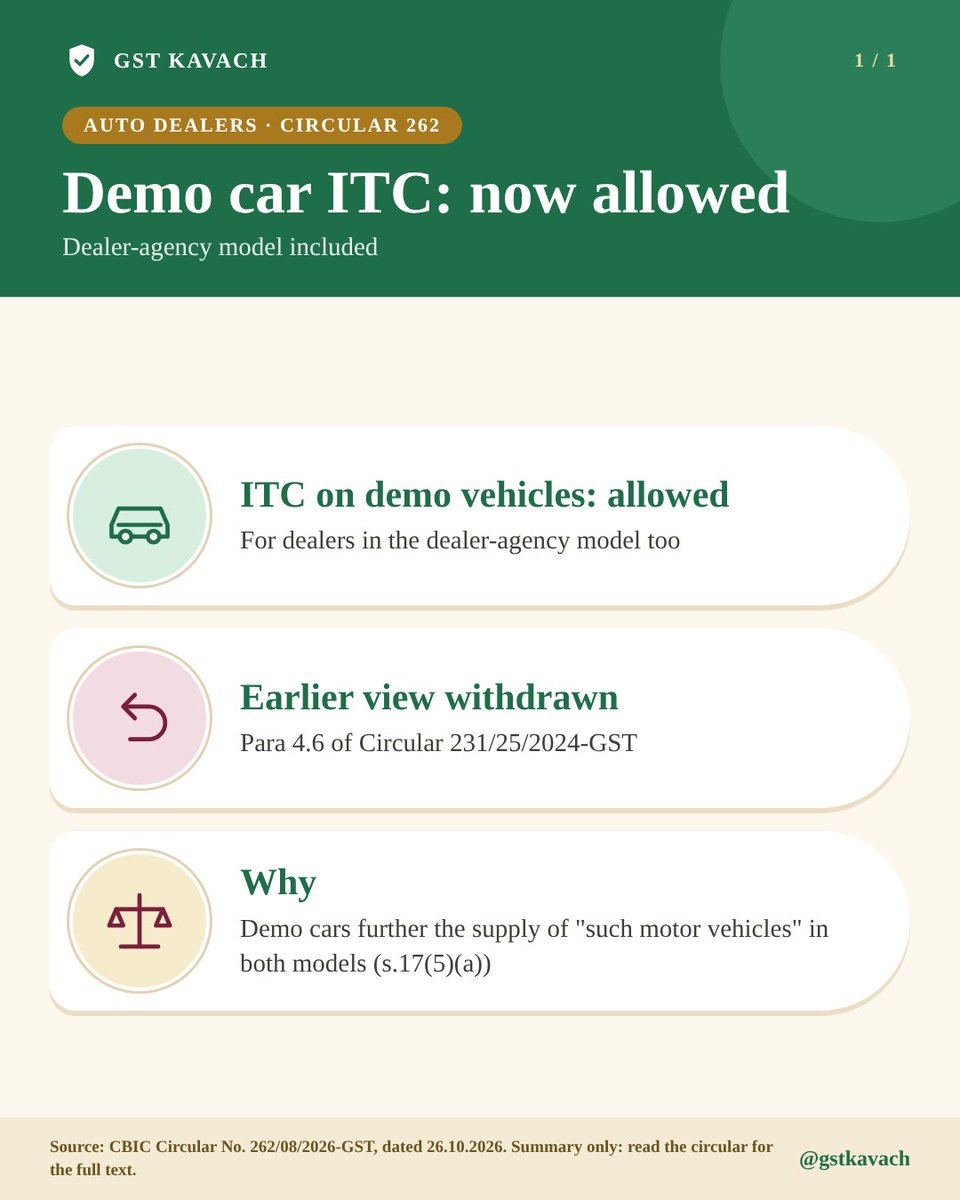
🚗 Auto dealers: ITC on demo vehicles is now allowed in the dealer-agency model too.
CBIC has withdrawn its earlier view (para 4.6, Circular 231/2024).
Source: Circular 262/08/2026-GST dated 26.10.2026
#GST#ITC#AutoDealers#GSTKavach
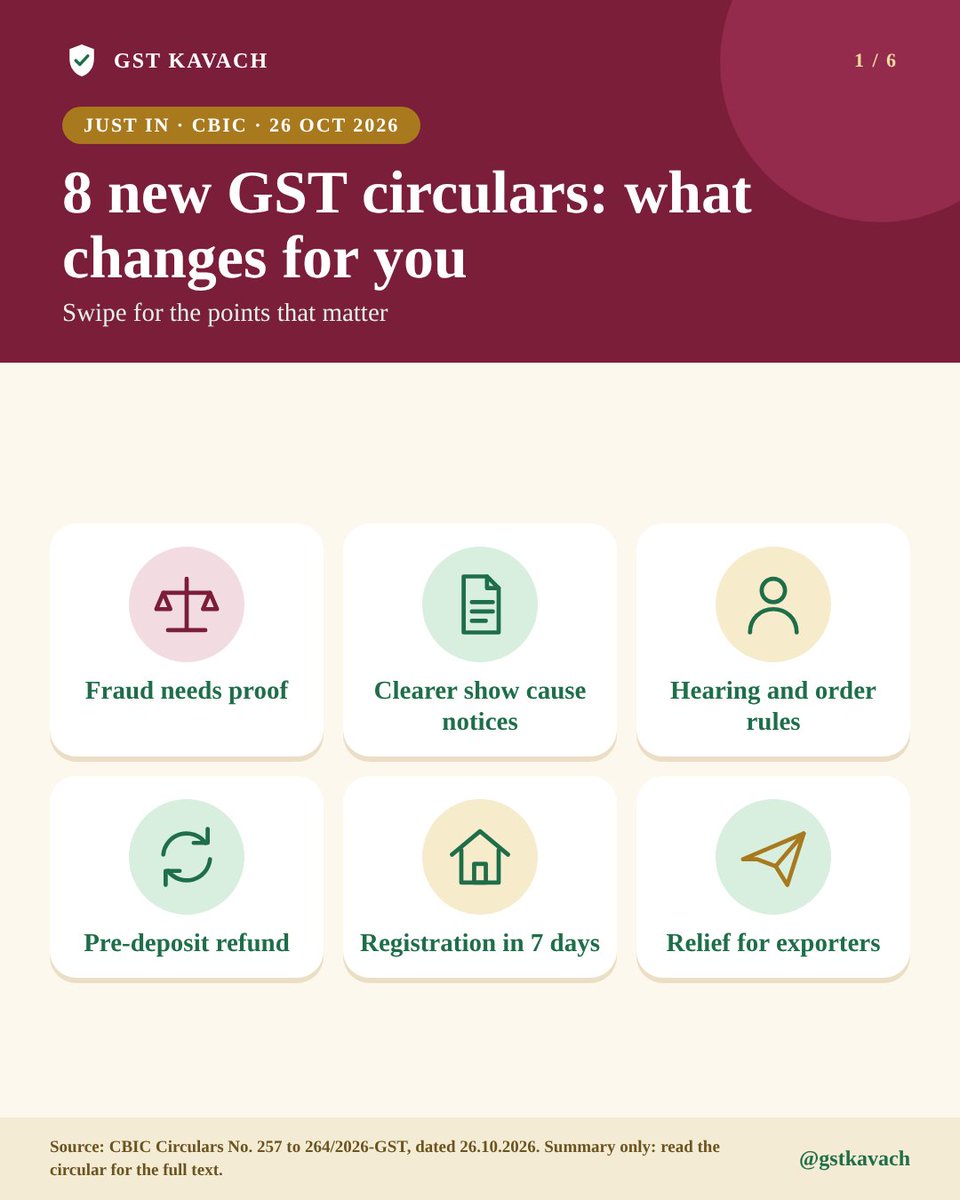
🚨 8 new GST circulars (26 Oct 2026):
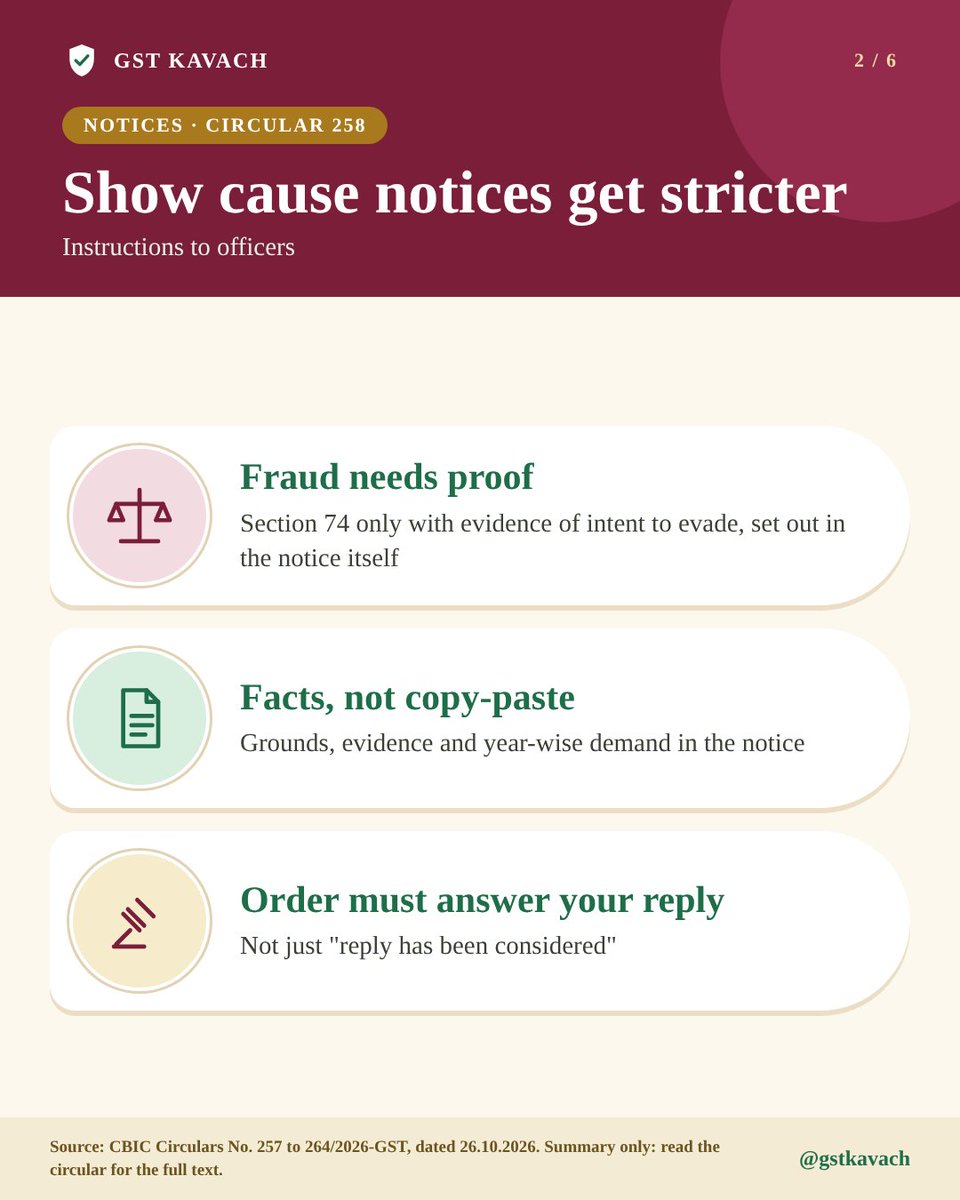
• Fraud (s.74) needs proof of intent in the SCN
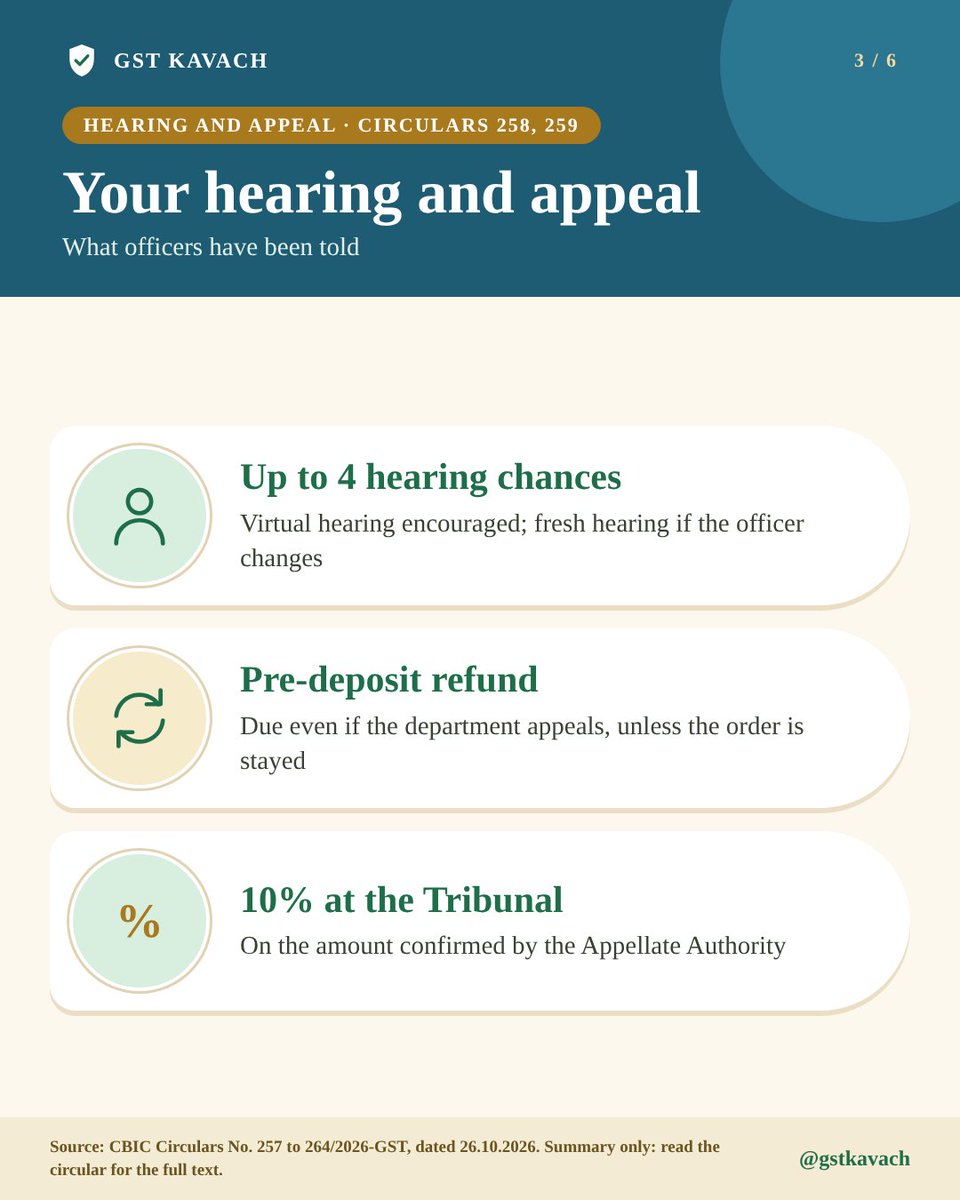
• Upto 4 hearing chances, virtual allowed
• Pre-deposit refund even if dept appeals
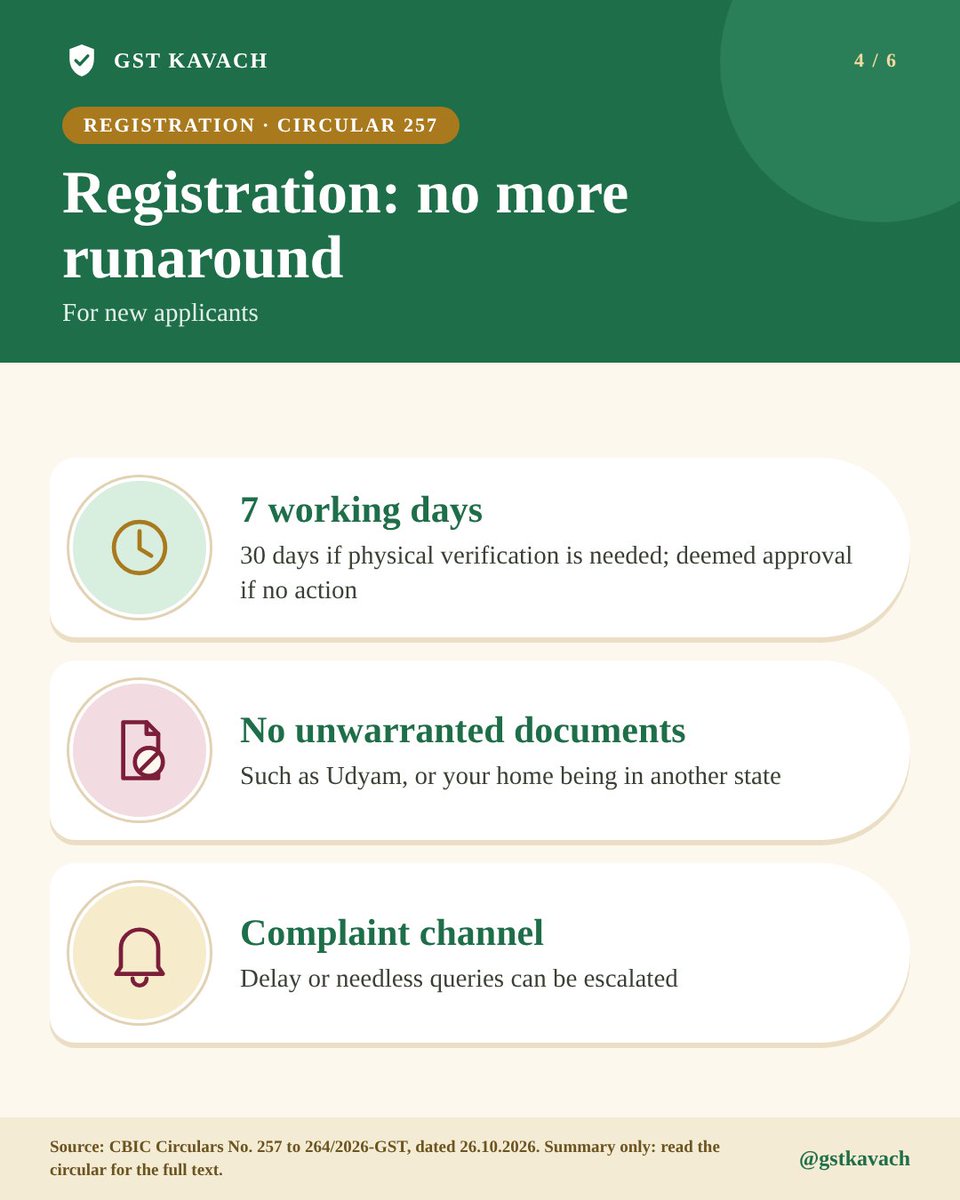
• Registration in 7 working days
• Rule 96(10) relief for pending cases.
#GST#GSTUpdate#GSTKavach
🚗 Auto dealers: ITC on demo vehicles is now allowed in the dealer-agency model too.
CBIC has withdrawn its earlier view (para 4.6, Circular 231/2024).
Source: Circular 262/08/2026-GST dated 26.10.2026
#GST#ITC#AutoDealers#GSTKavach
🚨 8 new GST circulars (26 Oct 2026):
• Fraud (s.74) needs proof of intent in the SCN
• Upto 4 hearing chances, virtual allowed
• Pre-deposit refund even if dept appeals
• Registration in 7 working days
• Rule 96(10) relief for pending cases.
#GST#GSTUpdate#GSTKavach
Missed the reply date on a GST notice?
• No order yet: reply now, with reasons for the delay
• Ask for a hearing in writing (s.75(4))
• Order passed: appeal within 3 months; +1 month only with sufficient cause (s.107)
#GST#GSTNotice#GSTKavach
Missed the reply date on a GST notice?
• No order yet: reply now, with reasons for the delay
• Ask for a hearing in writing (s.75(4))
• Order passed: appeal within 3 months; +1 month only with sufficient cause (s.107)
#GST#GSTNotice#GSTKavach
Your GST demand grows every day.
• 18% a year on tax paid late (s.50)
• Runs from the due date, not the notice date
• Wrong ITC availed and used also attracts interest (s.50(3)).
Got a demand notice? Check the numbers.
#GST#GSTNotice#GSTKavach
Your GST demand grows every day.
• 18% a year on tax paid late (s.50)
• Runs from the due date, not the notice date
• Wrong ITC availed and used also attracts interest (s.50(3)).
Got a demand notice? Check the numbers.
#GST#GSTNotice#GSTKavach
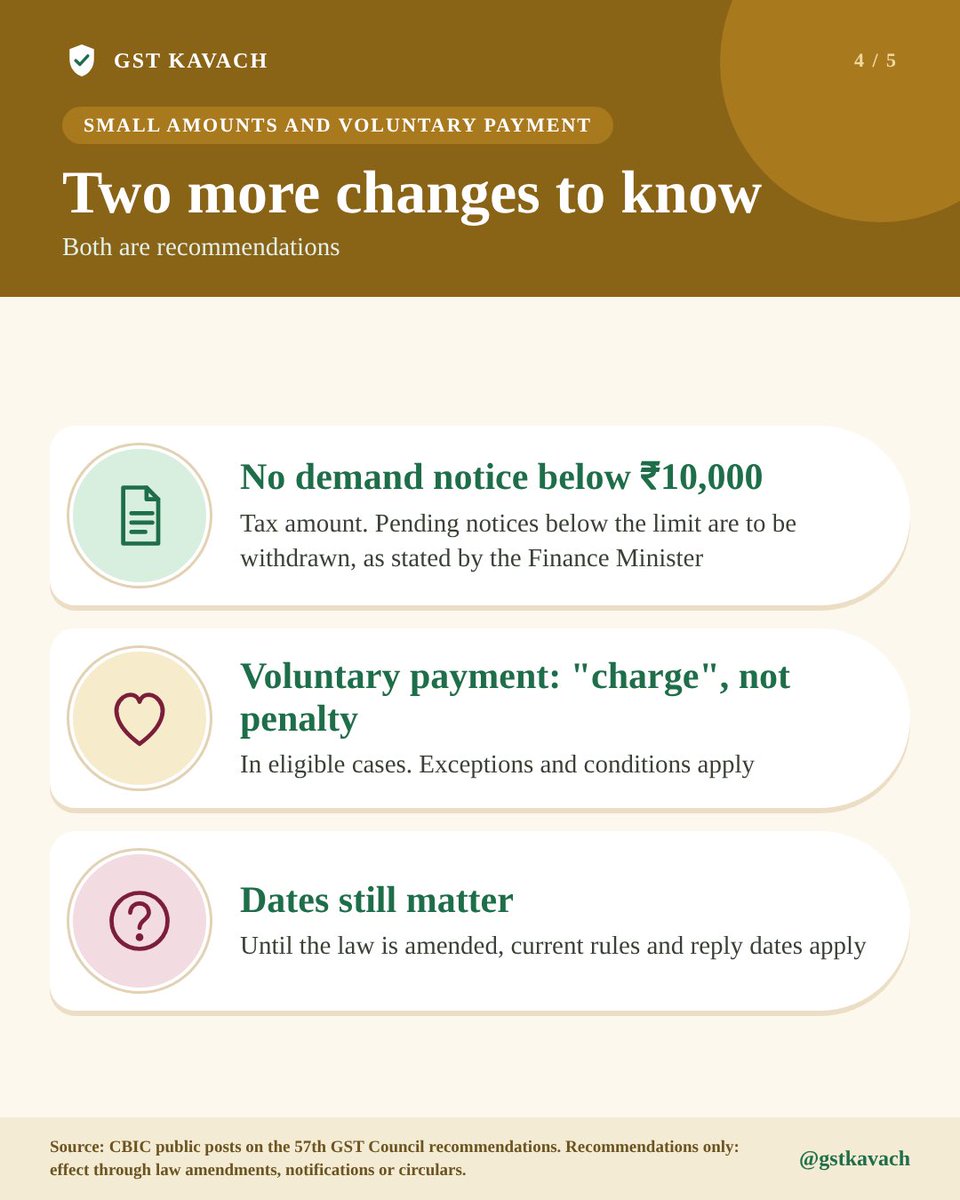
57th GST Council-Penalties may change
• General penalty ceiling ₹25,000 → ₹10,000 • 5% penalty in non-fraud cases if tax + interest paid within 30 days (s 73)/60 days (s 74A) • No demand notice below ₹10,000 • Voluntary payment: "charge", not penalty #GST#GSTCouncil
57th GST Council-Penalties may change
• General penalty ceiling ₹25,000 → ₹10,000 • 5% penalty in non-fraud cases if tax + interest paid within 30 days (s 73)/60 days (s 74A) • No demand notice below ₹10,000 • Voluntary payment: "charge", not penalty #GST#GSTCouncil