Welcome to my profile, where I break down the latest industry reports so you don’t have to.
If you’re looking to turn data into smart moves & actionable insights, stick around—you’ll find plenty to dive into.
Japan's VC activity shows steady growth, with Q2'24 deal value at $1.18B, though lower than Q2'21's peak of $1.97B, with 250+ deals consistently.
Part 18/19
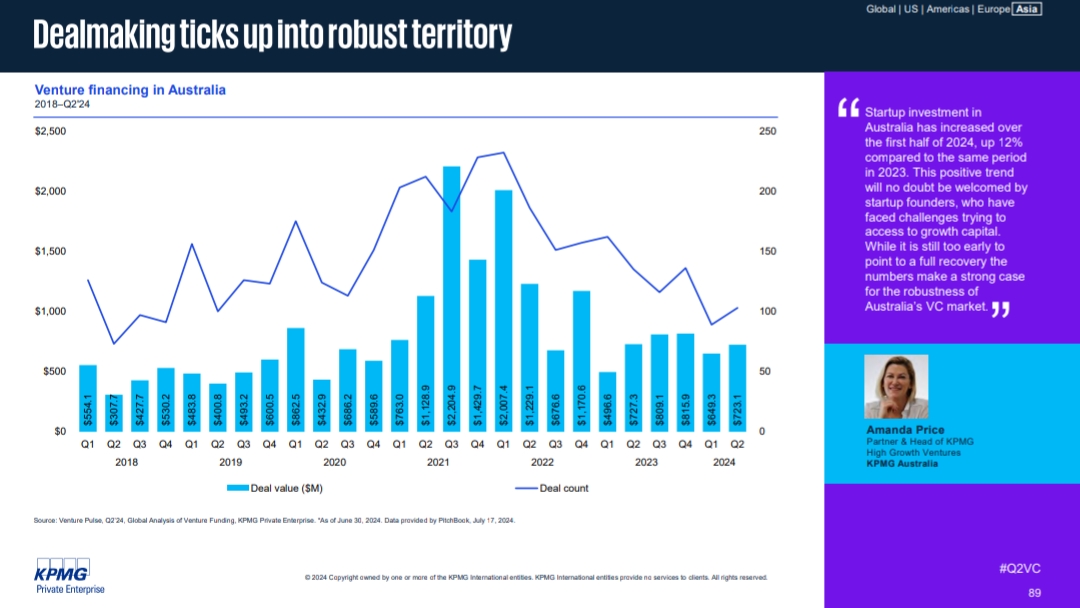
Venture financing in Australia has increased 12% in the first half of 2024 compared to 2023. This is a positive sign for the country's VC market, which has faced challenges in recent years.
Part 17/19
Venture financing in India has experienced a slight uptick in Q2 2024, following a similar increase in Q1. Deal value and count have both risen, with Q2 2024 seeing $4 billion raised and 52 deals closed.
Part 15/19
Asia's startup scene exploded in Q2'24, with 2,155 deals and $17.4B raised.
Check further parts for the complete breakdown.
If you find this helpful, don’t forget to like, comment, and follow for more insights!
Part 1/19
Midsized venture funds ($100M-$500M) have seen the largest fundraising increase in Asia from 2018 to 2024. First-time funds have grown, while follow-on funds have declined. Overall, venture fundraising has decreased in 2024.
Part 14/19
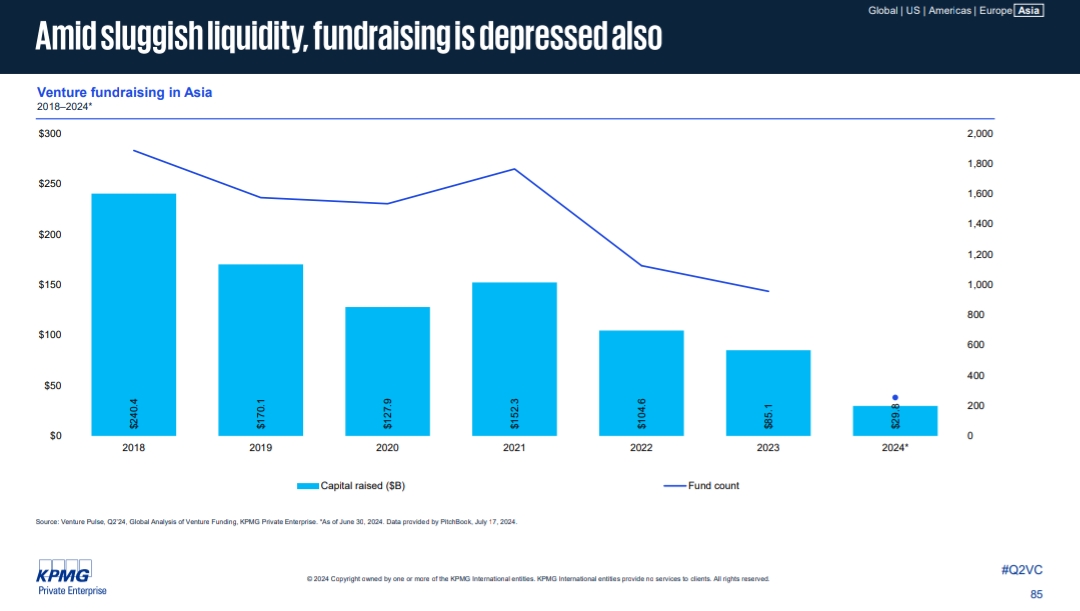
Venture fundraising in Asia has declined significantly since its peak in 2018. Capital raised and fund count have both decreased, with a more pronounced drop in 2024.
Part 13/19
IPOs have accounted for all venture-backed exit value in Asia in 2024, reaching $200 billion. While exit count has decreased, IPOs have increased significantly. Buyouts and acquisitions have declined.
Part 12/19
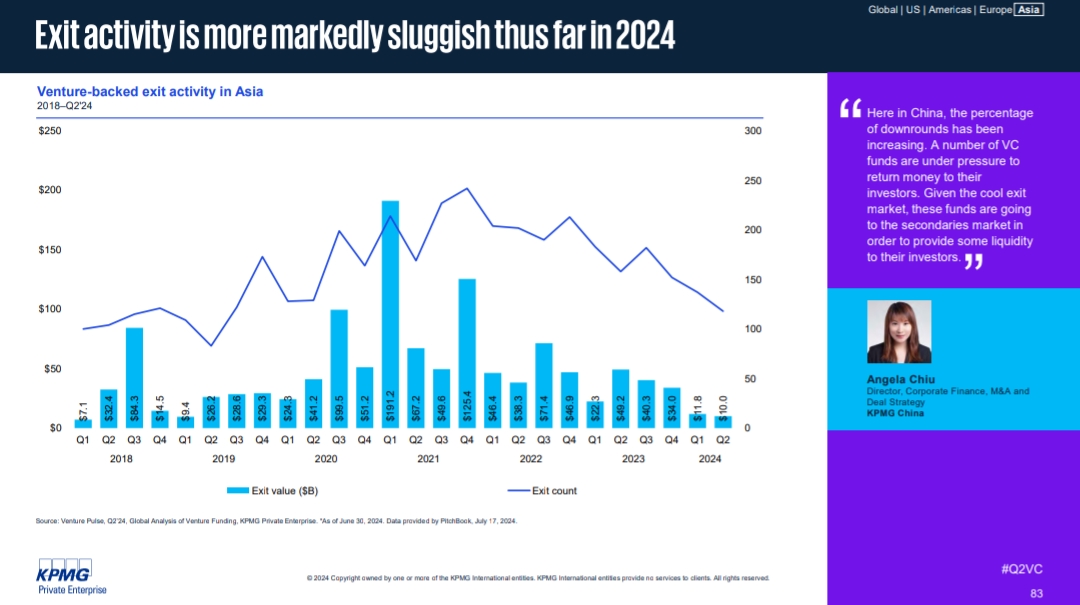
Venture-backed exit activity in Asia has declined significantly in 2024 compared to previous years. Exit value and count have dropped, with downrounds increasing. VC funds are facing pressure to return money to investors, leading to more secondary market activity.
Part 11/19
Corporate participation in venture deals in Asia declined in Q2'24. Deal value fell to $15.5B from $18.3B in Q1'24. Deal count also decreased to 134 from 175.
Part 10/19
Transportation, commercial products & services, consumer goods & services, software, and pharma & biotech remained key sectors for VC funding in Asia in Q2'24. Deal share for software and pharma & biotech increased, while others declined.
Part 9/19
Seed and Series A rounds remained dominant in Asia in Q2'24. Deal share for Seed and Series A slightly increased, while later-stage rounds declined.
Part 8/19
Median pre-money valuations in Asia rose in Q2'24. Pre-seed/seed rounds saw the biggest increase. Angel, Series A, and Series B rounds also saw moderate increases. Series C and D+ rounds declined.
Part 7/19
Median deal size for early- to mid-stage startups in Asia remained relatively stable in Q2'24. Pre-seed/seed rounds saw a slight increase. Angel, Series A, and Series B rounds remained relatively flat. Series C and D+ rounds declined.
Part 6/19
Median deal size in Asia plateaued in Q2'24. Up, flat, or down rounds have stabilized. Pre-seed/seed rounds saw a slight increase. Early VC and later VC rounds remained relatively flat. Venture growth rounds declined.
Part 5/19