

Top Tweets for #CGRAPHICS

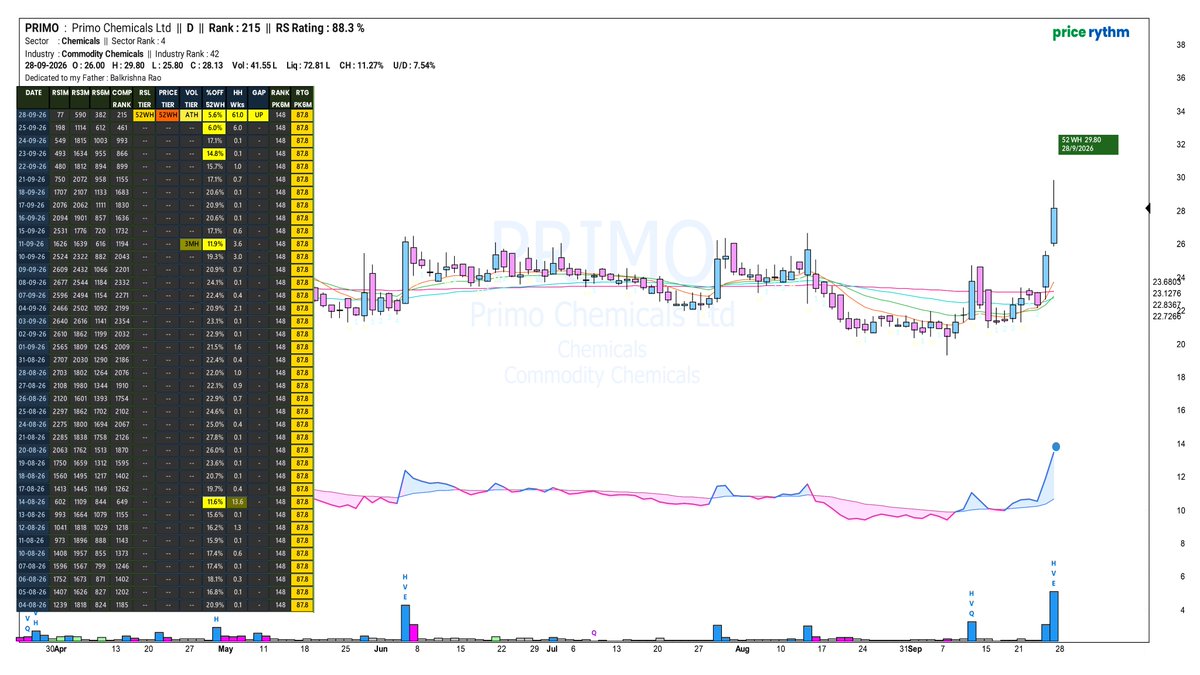
#PRIMO - Watchlist - $GAPUP $HVE $52WKH $RSL52WKH
#RETAIL #TNTELE #STARTECK #IWP #RSYSTEMS #REPRO #DAMCAPITAL #SMCGLOBAL #PRANIK #SSDL #SYNCOMF #MEDISTEP #CGRAPHICS #HINDCON #AVIENCE #CUBEXTUB #FLEXITUFF #GAYAHWS #DELPHIFX #SAMBHAAV #VIKASLIFE #RADAAN

Smart Money Radar | 07 Aug 2026 • 25 signals
NSE bulk deals: buyer/seller gross flow, named participants, net imbalance, HFT/ACCUM flags.
#AASTHA #ARIS #ARVSMART #ATALREAL #CGRAPHICS #CHAVDA #COMMITTED #COMSYN


#SME #CreativeGraphics #CGRAPHICS
Creative Graphics Solutions India H2FY26 Concall Highlights
👉 FY27 & Future Outlook
▫️Better optimism for FY27 with normalization of supply chains expected within 1-2 months
💠Q1-Q2 may see residual volatility but later on poised for sharp acceleration as new capacities (Alu-Alu, PVDC, Tandem, Bangalore Flexo) fully commercialize and contribute meaningfully
💠Installed capacity across businesses already supports 1000+ Cr annual turnover
💠Management’s long-term ambition remains doubling top-line every year (non-linear journey) — (reiterated as realistic given current order traction and capacity headroom)
▫️Warren (pharma packaging) to drive ~80% of target (Alu-Alu + PVDC + Tandem + blister); Flexo ~20%.
💠At optimal utilization: Warren gross margins targeted at 17-18%, EBITDA mid-teens (13-14%) — higher in exports and value-added products (holography, anti-counterfeit)
💠Margins bottomed in H2 FY26; sequential improvement expected from FY27 onward as front-loaded expansion costs are absorbed, supply volatility eases, and price hikes (already +30% on Alu-Alu, ~25% on PVDC) fully flow through
💠Exports (first order Feb 2026) to be key margin driver with better realizations; 20%+ export share targeted for Alu-Alu/PVDC business
💠Overall: FY27 viewed as “year of major action” as per management; to deliver meaningful step-up vs FY26’s consolidated revenue
👉 Current Order Book / Projects and Future Pipeline
▫️Domestic order book “full” and spilling over month-on-month
💠Unable to fulfill all orders due to raw material supply constraints (not demand)
💠Export order book: First order received Feb 2026; 100+ MT in hand (pipeline significantly higher); long-gestation but high-realization focus; targeting 20%+ of pharma packaging revenue from exports
💠Existing 8,000 MT Alu-Alu plant utilization ~80% in H2 FY26 despite March-May disruptions
▫️New capacities update:
💠12,000 MT Alu-Alu foil factory (Wahren): Machine installed, trial runs complete, on cusp of commercialization (well before original H1 FY27 guidance); expected to add significant volume in FY27
💠 PVC/PVDC line: Commercialized end-H2 FY26; small revenue in H2 (~₹0.5-0.6 Cr); targeting ~25% utilization in FY27; orders in hand but raw material shortages impacted ramp
💠Tandem extrusion machine: Commercialized April 2026; currently sampling stage; new product line for pharma
💠Bangalore Flexo factory: Already running; client acquisition & testing stage; strategic location for South India growth
💠Oman Flexo factory: Installation complete but delayed due to war-related supply/manpower issues; expected commercialization in next quarter
▫️Pipeline drivers:
💠Latent demand in PVDC/Tandem (import substitution + export potential); unmet demand in specialty products
💠Blister foil line newly started (machine acquired); consistent client + export demand
💠Pharma packaging market tailwinds: Alu-Alu ~5,000 tons/month (~₹500/kg avg.); blister market ~double; PVDC 3,000-4,000 tons/month
▫️Current India Alu-Alu market share ~8-10%; well-distributed across 400+ clients (no 80-20 concentration; top clients like Intas, Zydus, Cadilla, Torrent buying progressively higher volumes)
▫️Competitive edge vs incumbents: Broader product portfolio (Foil, blister, PVC/PVDC, tandem 3/4-layer)
💠Printing value-add from Creative legacy, faster capacity/capability build in 3.5 years
👉 Other Notable Points
▫️FY26 performance recap:
💠 Consolidated revenue ₹348 Cr (vs ₹256 Cr FY25)
💠PAT ₹18.76 Cr (vs ₹20.77 Cr FY25) — slight decline due to :
(1) Front-loaded expansion costs (employee +25%, finance +42%)
(2) ~₹5 Cr gross margin hit in H2 from Alu price/FX volatility + war-related supply disruptions
💠 H2 sales ₹172 Cr (vs H1 ₹177 Cr) impacted by pharma supply issues (esp. March) and softer Flexo macro
💠Standalone boosted by ~₹27 Cr internal Creative-to-Wahren sales
▫️Risk mitigation & financial preparedness:
💠Debtor insurance continued on all receivables
💠Added Citibank as second banker + first bill-discounting facility (₹3-4 Cr done in Mar’26, scalable); working capital limits enhanced to support growth
▫️Management additions:
💠New CEO (ex-DuPont, 30+ years flexo expertise) for Creative Graphics line
💠New plant head for Wahren; manpower increase primarily for new capacities
▫️Supply chain & hedging:
💠Still not fully out of woods but visibility improving
💠Significant aluminum inventory built as natural hedge; hedging enabled but not yet active (premiums high)
💠Price hikes fully passed on to clients (partnership model); no long-term contracts — monthly orders allow flexibility
▫️Client & market dynamics:
💠Pharma clients understand temporary supply issues (industry-wide); no demand drop; sticky business with high qualification barriers

👉Mainboard stocks often get all the attention but some of the most compelling businesses are hiding in plain sight — on the SME Platform.
👉Smaller. Less covered, though noisy at times. Yet occasionally, genuinely exceptional.
———
👉Introducing SME Gems — a new independent series on Hidden Champions of the SME Platform :
💠 OBSC Perfection
💠 Aimtron Electronics
💠 Yash Highvoltage
💠 CFF Fluid Control
💠 DSM Fresh Foods
💠 L.T. Elevator
💠 Monolithisch India
💠 GSM Foils
👉Across Different Sectors. One common place.
🔗 https://t.co/Sto1a1qHIQ
👉Stay tuned for more insights
———
⚠️ For educational purposes only. Not investment advice. Please DYODD.
#SMEGems #SMEPlatform #HiddenChampions #SME

📌 Creative Graphics Solutions India Limited informed the exchange about its approval for the financial results for the period ended March 31, 2026. #SME #CGRAPHICS 📄🧾


Arihant Bharat Connect Conference March '26:
👉Day 4:
💠Creative Graphics Solutions
💠Thaai Casting
💠Sadhav Shipping
💠Apex Ecotech
💠KVS Casting
#cgraphics #apex #thaaicasting #tcl #sadhav #sadhavshipping #kvscasting #kvs #apexecotech #creativegraphics #bharatconnectconference #arihantcapital


Arihant Bharat Connect Conference March '26:
👉Day 4:
💠Fredun Pharmaceuticals
💠Sugs Lloyd
💠Digilogic Systems
#digilogic #digilogicsystems #sugs #sugslloyd #fredun #fredunpharma #bharatconnectconference #arihantcapital


**SME News Bulletin 2026-02-09**
[Management Changes and Board Meeting Outcomes]
#CGRAPHICS - Creative Graphics Solutions India Limited Reports Management Change
#CGRAPHICS - Creative Graphics Solutions India Limited announces board meeting outcome on February 09, 2026
#CGRAPHICS - Creative Graphics Solutions India Limited announces new addition to management on February 09, 2026
#SADHAV - Sadhav Shipping Limited announces board meeting outcome on February 09, 2026
#SUPREMEPWR - Supreme Power Equipment Limited announces board meeting outcome on February 09, 2026
#PATTECH - Pattech Fitwell Tube Components Limited announces board meeting outcome on February 09, 2026
#SADHAV - Sadhav Shipping Limited reports financial results for period ending December 31, 2025
#KALYANI - Kalyani Commercials Limited reports financial results for period ending December 31, 2025
[New Appointments and Resignations]
#SADHAV - Sadhav Shipping Limited appoints Satish Athaley as Non-Executive Independent Director
#SADHAV - Sadhav Shipping Limited appoints Rajiv Pradhan as Non-Executive Independent Director
#DELAPLEX - Delaplex Limited appoints new APAC sales consultant
[Financial Results and Reports]
#SUPREMEPWR - Supreme Power Equipment Limited Reports Financial Results for Period Ending December 31, 2025
#ALPEXSOLAR - Alpex Solar Limited reports financial results for period ending December 31, 2025
#SONUINFRA - Sonu Infratech Limited Reports Financial Results for Q3 2025
[Contracts and Collaborations]
Sahana System Limited's Subsidiary Signs MOU with Bharat Electronics Limited for Defense & Digital Tech Collaboration
Presstonic Engineering receives prestigious order from L&T Construction Equipment Limited
Silicon Rental Solutions Receives Rs.4.61 Crores Purchase Order from Said Technologies Private Limited
[Investments and Subsidiaries]
Bondada Engineering Commissions 69.51 MWP Solar Projects Across Multiple Locations
Esconet Technologies in Talks for Third-Party Investment in Zeacloud Services
G M Polyplast Limited Incorporates Wholly Owned Subsidiary in India
[Regulatory Updates and Disclosures]
#KDL - Kore Digital Limited notifies exchange of regulation 29 (2) intimation
#MAGSON - Tarangkumar Manubhai Savaliya Submits Disclosures Under Regulation 29(1) to Exchange

Creative Graphics Solutions
#CGraphics
#CreativeGraphics
H1FY26 Concall pointers:
Very good concall with great clarity from management wrt business insights, future plans,new capacity ramp up and utilization targets
Expects H2 to be higher/stronger than H1 because multiple new lines are coming online in H2FY26
1.PVDC/PVC line commercialisation in H2
2.Tandem line commercialisation in H2
3.Bangalore flexo plant already up and running and ramping up well
4.Oman flexo plant expected in H2- Trial runs ongoing
Wahren (pharma packaging) will continue to grow much faster than the flexo plating business
Strong enquiries from multiple pharma companies
Known for quality and best pricing
Margins:
Expects current to sustain/improve over time because:
Raw material price increases are now being passed on
Shift in product mix to higher-value products (PVDC & Tandem have better gross and EBITDA margins)
Can go back to/ has good scope to exceed 8-9% PAT margins once scale up benifits and product mix change kicks in as operating leverage will start playing out
Capacities:
Alu-Alu
Current capacity
8,080 MT/annum
75% utilisation
New Italian machine (12,000 MT) delivered Oct 2025
Commercialisation in H1FY27
Total capacity post expansion:
20,080 MT/annum
Expects 75–80% utilization on existing capacities
30–40% on new machine in FY27 and 70% by FY28
PVDC/PVC coated line:
New capacity online from H2FY26 Commercialisation on track
Capacity of12,000 MT/annum
15%-20% utilization in H2FY26
Target 70–80% utilization by end of FY27
Significantly higher realizations vs Alu-Alu
Tandem line:
Commercialisation on track for
Better margins expected
Strong enquiries
Flexo Plate Business Expansion: Bangalore plant already started operations, ramping up well
Oman plant
Installation complete, solving teething issues
Commercialisation expected in H2FY26
Can ramp up well as demand is very strong
Exhibition participation and good response for the products
6 international + 6 domestic in last 12 months
Exports to be 20% of total revenues
4-5% higher margins here
Large pharma clients added (Aurobindo, Torrent Pharma, Sun Pharma in process)
Shift from small to A+++ clients now visible and focus would continue in that direction
Aluminium price spike impact largely absorbed
Almost 100% passthrough now possible on new orders
#SME #CGraphics #CreativeGraphicsSolutions
Creative Graphics Solutions H1 FY26 Concall Highlights:
👉FY 2026 & Future Outlook :
▫️Did not give explicit FY26 guidance but expects H2 to be higher than H1 because multiple new lines are coming online in H2
▫️New capacities contributing in H2 FY26:
💠PVDC/PVC line commercialisation in H2
💠Tandem line commercialisation in H2
💠Bangalore flexo plant already running and ramping
💠Oman flexo plant expected in H2
💠Wahren (pharma packaging) will continue to grow much faster than the flexo plate business.
▫️Margins: Expects current to sustain and improve over time because:
💠Raw material price increases are now being passed on
💠Mix shift to higher-value products (PVDC & Tandem have gross margins in high 30s and higher EBITDA than Alu-Alu
💠Initial discounting to large pharma clients will ease as volumes grow
💠Believes that they can go back to or exceed that ~8-9% PAT once scale benefits and product mix kick in
▫️Emphasis on complete product basket (Alu-Alu + PVDC + Tandem); ensures no dependence on one product and helps optimise customer wallet share
💠No diversification outside packaging planned; full focus on pharma packaging + flexo plates
👉Projects and pipeline:
▫️Alu-Alu (Cold Form Foil): Current capacity: 8,080 MT/annum → running at ~75% utilisation
💠New Italian machine (12,000 MT) delivered Oct 2025 → commercialisation now pushed to H1 FY27 (delay from vendor custom changes)
💠Total capacity post expansion: 20,000 MT/annum
💠Utilisation outlook: 75–80% on existing + 30–40% on new machine in FY27
💠Realisation: ₹370–430/kg
▫️PVDC/PVC coated line: Commercialisation on track for H2 FY26
💠Capacity: 12,000 MT/annum
💠Starting utilisation guidance: 10–15% in H2 FY26 (100–150 MT/month conservative)
💠Target: 70–80% by end FY27
💠Realisation: ₹240–350/kg → significantly higher % margin than Alu-Alu (lower absolute price but much lower raw material cost → leads to high gross margin)
▫️Tandem line: Commercialisation on track for H2 FY26
💠Not tonnage-based; multi-layer high-value structures (foil/paper/PET etc.)
💠Some structures give very high profitability → expected to be the highest-margin product in the basket
💠High inquiry backlog; claims that only one other player in India has similar capability
▫️Flexo Plate Business Expansion: Bangalore plant: installation complete → already started operations, ramping up
💠Oman plant: installation complete, solving teething issues → commercialisation expected in H2 FY26
💠Oman capacity: ~10 million sqcm/month
💠Overall flexo utilisation currently 65–70%; capacity is not a bottleneck → more about service reach; still 30% headroom + new plants
▫️Export Push (Wahren): Head of Export sales onboarded
💠Exhibition participation (6 international + 6 domestic in last 12 months)
💠Export orders expected to be 20%+ of revenue longer-term; margins +4–5% higher and better working-capital terms (advance/LC)
▫️Large pharma clients added (Aurobindo, Torrent, Sun Pharma in process, etc.) → shift from small to A+++ clients now visible
👉 Others :
💠Debtor insurance taken → allows pursuit of large pharma clients
💠Working capital cycle (now 100+ days) because of big pharma credit (90–120 days) → management comfortable; will use aggressive bill discounting + internal accruals; debt only for WC if needed
💠Cash flow from operations negative and will remain so until all facilities are online and sales momentum plateaus
💠No major capex planned for FY26/FY27 → only small reliability/spare capex; gross block largely done
💠No current plan to raise equity; will take debt if required
💠Other expenses dropped from ~11% to ~8% of sales because of operating leverage → expected to continue falling in % terms
💠Aluminium price spike impact largely absorbed; almost 100% pass-through now possible on new orders
💠Anti-dumping duty on Chinese clay caused one-off margin hit → now resolved
💠Flexo business align with EPR norms → gravure printing (toxic) being phased out globally; India penetration still only 9–12%
Creative Graphics
#CGraphics
#CreativeGraphics
Strong H1FY26
Highest ever revenue, EBITDA, PBT and PAT in comps history
2nd half should be more stronger due to new machines that would contribute in H2
H1FY26:
Rev at 176cr vs 113cr⏫56%
H1 at 138cr
EBITDA at 21cr vs 13cr⏫62%
H1 at 19cr
PVC/PVDC machine:
Tamdem machine:
On track to be commercialized in H2FY26
12000 Mt Alu Alu machine:
Delivered in Oct 2025
H1FY27 commercialization
Flexographic plates:
2 new factories to be launched in H2
Operational from Q2 -Bengaluru
Oman factory to commence in H2FY26
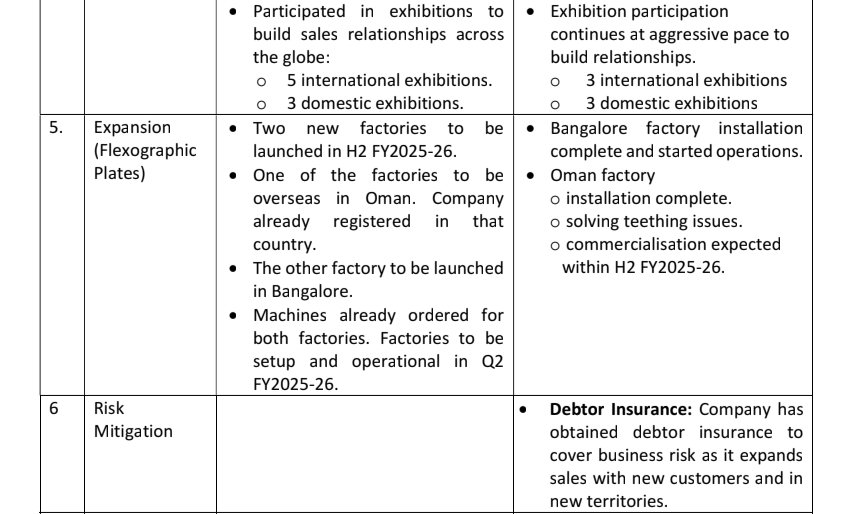


H1 exactly played out how it was expect, all capacities almost live this takes name plate capacity to 1000-1200cr.
H2 and FY27 can be very big, con call is going to be very interesting
Extreme transparency in the press release for a SME standard
#CGraphics #SME


Good#Q2FY26-14/11/25 post 9pm
Creative Graphics
#CGraphics
Good H1FY26
With new capacity in place H2 should scale up well
Rev at 176cr vs 113cr, H2 at 138cr
Good uptick vs H1FY25 and H2FY25
PBT at 16cr vs 9cr, H2 at 14cr
(adjusted for 3cr other income difference)
OCF at -13cr vs -22cr
Suba Hotels
#Suba
H2 heavy bysiusine
H2 forms 60% for hotels
Good H1FY26
Rev at 44cr vs 29cr
PBT at 6.2cr vs 4cr
PAT at 5.2cr vs 3.3cr
OCF at 0.3cr vs 3cr
UNIHEALTH Hospital
#UniHealth
Rev at 66cr vs 43cr, H2 at 56cr
PBT at 30cr vs 13cr, H2 at 18cr
PAT at 28cr vs 9cr, H2 at 18cr
Blockbuster H1FY26
OCF at -1cr vs 3cr
GK Energy
#GKEnergy
Good Q2FY26
Rev at 358cr vs 270cr, Q1 at 295cr
PBT at 62cr vs 48cr, Q1 at 50cr
PAT at 46cr vs 34cr, Q1 at 37cr
OCF at -235cr vs -97cr
Ganesh Infraworld
#GaneshInfra
Great pace of execution
Rev at 210cr vs 95cr, H2 at 180cr
PBT at 24cr vs 9cr, H2 at 19.5cr
PAT at 18cr vs 7cr, H2 at 14.6cr
OCF at -30cr vs -36cr
SKF India
#SKF
Rev at 1309cr vs 1244cr, Q1 at 1283cr
PBT at 166cr vs 127cr, Q1 at 160cr
OCF at 319cr vs 214cr
Balu Forge
#BaluForge
Rev at 299cr vs 222cr, Q1 at 223cr
PBT at 80cr vs 64cr, Q1 at 70cr
PAT at 65cr vs 48cr, Q1 at 57cr
OCF at 40cr vs 50cr
Sequent
#Sequent
Rev at 424cr vs 368cr, Q1 at 441cr
PBT at 27cr vs 8cr, Q1 at 25.5cr
PAT at 20cr vs 7cr, Q1 at 17.5cr
OCF at 45cr vs 24cr
Arihant Foundation
#ArihantFound
Rev at 89cr vs 48cr, Q2 at 43cr
PBT at 25cr vs 15cr, Q1 at 21cr
PAT at 20cr vs 11cr, Q1 at 16cr
OCF at -56cr vs -86cr
#Markolines
Rev at 78cr vs 55cr, Q1 at 73cr
PBT at 5.6cr vs 3.1cr, Q1 at 5.2cr
OCF at 22cr vs -18cr
#RMDrip
Rev at 31cr vs 17cr, Q1 at 30cr
PBT at 8cr vs 2.5cr, Q1 at 7.3cr
OCF at -6cr vs -16cr
#DSSL
Good Q2FY26
Rev at 352cr vs 306cr, Q1 at 329cr
PBT at 31cr vs 24cr, Q1 at 26cr
PAT at 22.5cr vs 18cr, Q1 at 19.6cr
OCF at 10cr vs 13cr
Prizor Viztech
#Prizor
Rev at 42cr vs 31cr, H2 at 40cr
PBT at 8cr vs 6cr H2 at 7.6cr
PAT at 6cr vs 4cr H2 at 6cr
OCF at 1.9cr vs -17cr
#ChandanHealth
Rev at 136cr vs 110cr, H2 at 120cr
PBT at 22cr vs 15cr, H2 at 16.6cr
PAT at 16.5cr vs 11.2cr, H2 at 12.2cr
#VGInfotech
Rev at 86cr, PBT at 31cr, PAT at 22cr
FY25 PBT was 45cr and PAT was 32cr
OCF at 16cr
#BAGConvergance
Rev at 22cr vs 13cr, H2 at 22cr
PBT at 8cr vs 5.7cr, H2 at 7cr
Arham Technologies
#Arham
H1FY26:
Rev at 46cr vs 32cr
PBT at 7.2cr vs 3.5cr
PAT at 5.9cr vs 2.6cr
CWD Ltd
#CWD
Rev at 40cr vs 6.5cr, H2 at 26cr
PBT at 6cr vs loss, H2 at 5cr
OCF at -42cr
Tejas Cargo
#TejasCargo
Rev at 302cr vs 252cr, H2 at 249cr
PBT at 16.8cr vs 11.6cr, H2 at 14cr
OCF at 28cr
Balaji Phosphate
#BalajiPhos
Rev at 84cr vs 62cr, H2 at 64cr
PBT at 11cr vs 5.7cr, H2 at 5cr
Solid uptick vs H1FY25 and H2FY25
PAT at 8cr vs 4.3cr, H2 at 3.5cr
Tunwal E Motors
#Tunwal
Good H1FY26, pleasant surprise
Rev at 144cr vs 74cr, H2 at 104cr
PBT at 11.4cr vs 7.2cr, H2 at 8cr
OCF at -6cr vs -53cr
Aesthetik Engineers
#Aesthetic
Rev at 30cr vs 24cr, H2 at 34cr
PBT at 3.3cr vs 0.7cr, H2 at 6cr
OCF at 0.2cr
Forcas Studio
#Forcas
Good H1FY26
Rev at 84cr vs 55cr, H2 at 87cr
PBT at 7.8cr vs 3.9cr, H2 at 7.7cr
OCF at -27cr vs -4cr
#AkankshaPower
Rev at 44cr vs 26cr, H2 at 52cr
PBT at 3.1cr vs 2.1cr, H2 at 4cr
OCF at 12cr
#K2Infra
Rev at 91cr vs 51cr, H2 at 95cr
PBT at 9.6cr vs 5.8cr, H2 at 9cr
OCF at -13cr vs -43cr
#ArabianPetro
Rev at 182cr vs 139cr, H2 at 146cr
PBT at 8cr vs 6cr, H2 at 6.6cr
OCF at -12cr vs 11cr
#Canarys
Solid H1FY26
Good uptick vs H1FY25 and H2FY25
Rev at 101cr vs 38cr, H2 at 51cr
PBT at 12cr vs 5.6cr, H2 at 5.8cr
PAT at 9cr vs 4cr, H2 at 4cr
OCF at -0.4cr
#Karnika
Rev down at 69cr vs 71cr
PBT at 12.7cr vs 9.7cr, H2 at 4cr
OCF at 4cr vs 3cr
#RBMInfra
Solid H1FY26
Rev at 284cr vs 103cr, H2 at 218cr
PBT at 36cr vs 13cr, H2 at 27cr
PAT at 27cr vs 10cr, H2 at 19.5cr
Big uptick vs H1FY25 and H2FY25
OCF at -11cr vs -7cr
#ViazTyres
Rev at 43cr vs 28cr, H2 at 29cr
PBT at 2.7cr vs 1.5cr, H2 at 2.9cr
OCF at -0.5cr
Decent:
#BahetiRecycling
#ForgeAuto
#PatelChem
#RajputanaBio
📌 Creative Graphics Solutions India Limited informed the exchange about its approval for the financial results for the period ended September 30, 2025. #SME #CGRAPHICS 📄🧾


Hello everyone I am sharing my detailed educational report on an ignored SME company guiding 100% CAGR for 2yrs called Creative Graphics Solutions India Ltd #CGRAPHICS a proxy on the Indian CDMO boom 🧵👇

#CGRAPHICS #CREATIVEGRAPHICS #CREATIVEGRAPHICSSOLUTIONS
Creative Graphics Solutions Business Analysis
https://t.co/KKAtnYL8uN
Tandem Extrusion Products - Detailed Explanation (New biz line for Creative Graphics)
https://t.co/b8u7eR9iqt
Creative Graphics Q4FY25 Earnings Call Summary
https://t.co/ybzl1HLlju
P.S.
1. Take it with bucket of salt as AI generated (not all information maybe correct, objective is to get high level view of the business)
2. Invested, Assume Biased & Vested Interest
3. Read disclaimer/disclosure in Pinned message on the profile
4. Not a recommendation to Buy/Sell (ignore the buy/sell thesis in the AI generated summary; it is not my view and AI generated automatically)
5. Do your own due diligence and consult your financial advisor


Creative graphics
#CGraphics
#CreativeGraphics
H2FY25 Concall snippets:
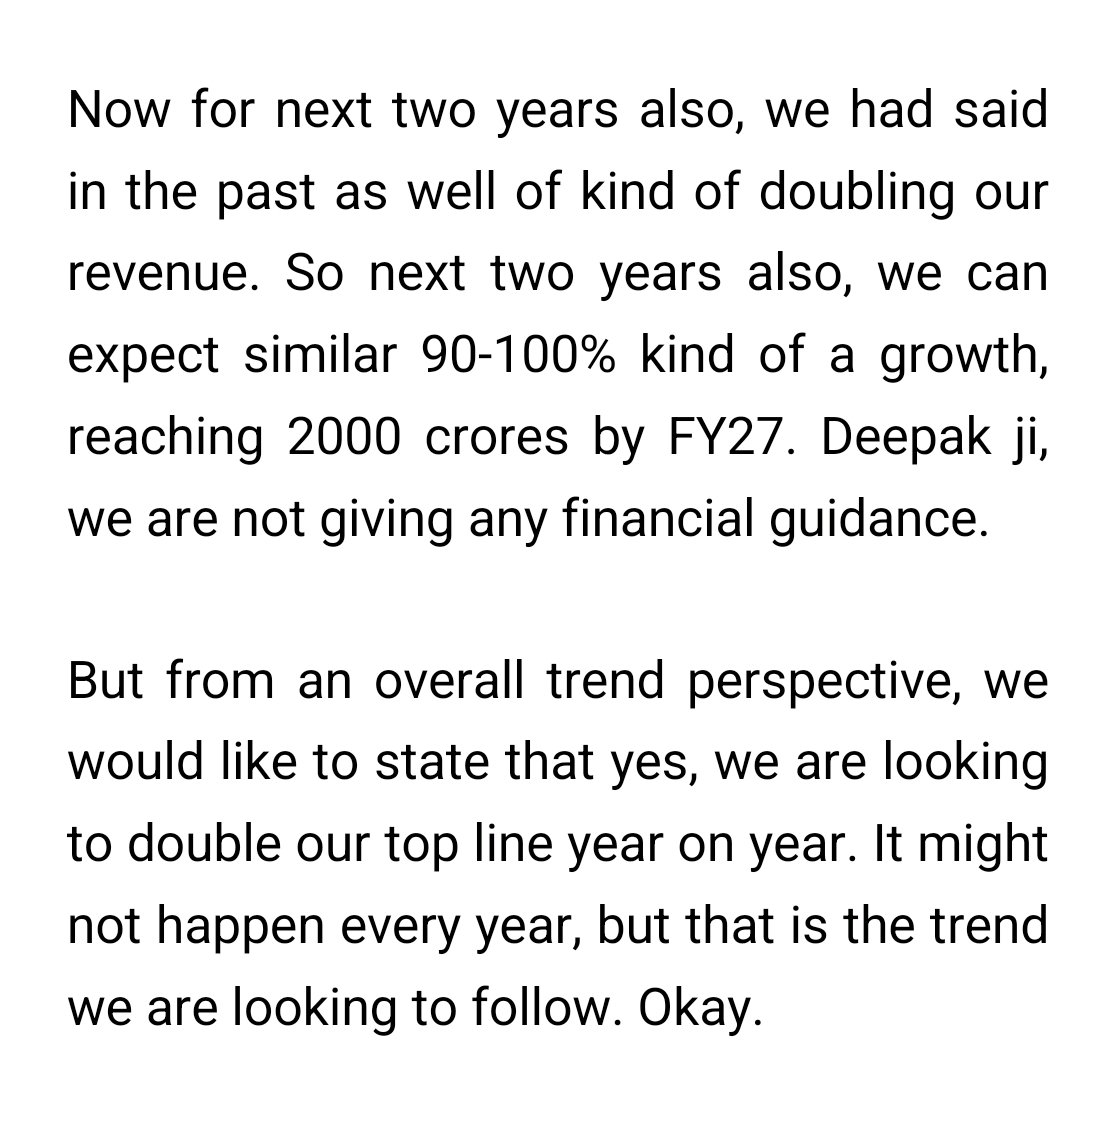
Target to double revenue every year for next 2-3 years
Margins to gradually improve with higher utilization
Average capacity utilisation of 50% now
No need of any fund raise
WAHREN utilization has improved from 25% at beginning of FY25 to 65-70% at the end of FY25
Further capacity increase
New machines- should have come online by Q1
But got delayed to Q2FY26
Q2 and H2 should show full impact of these additions
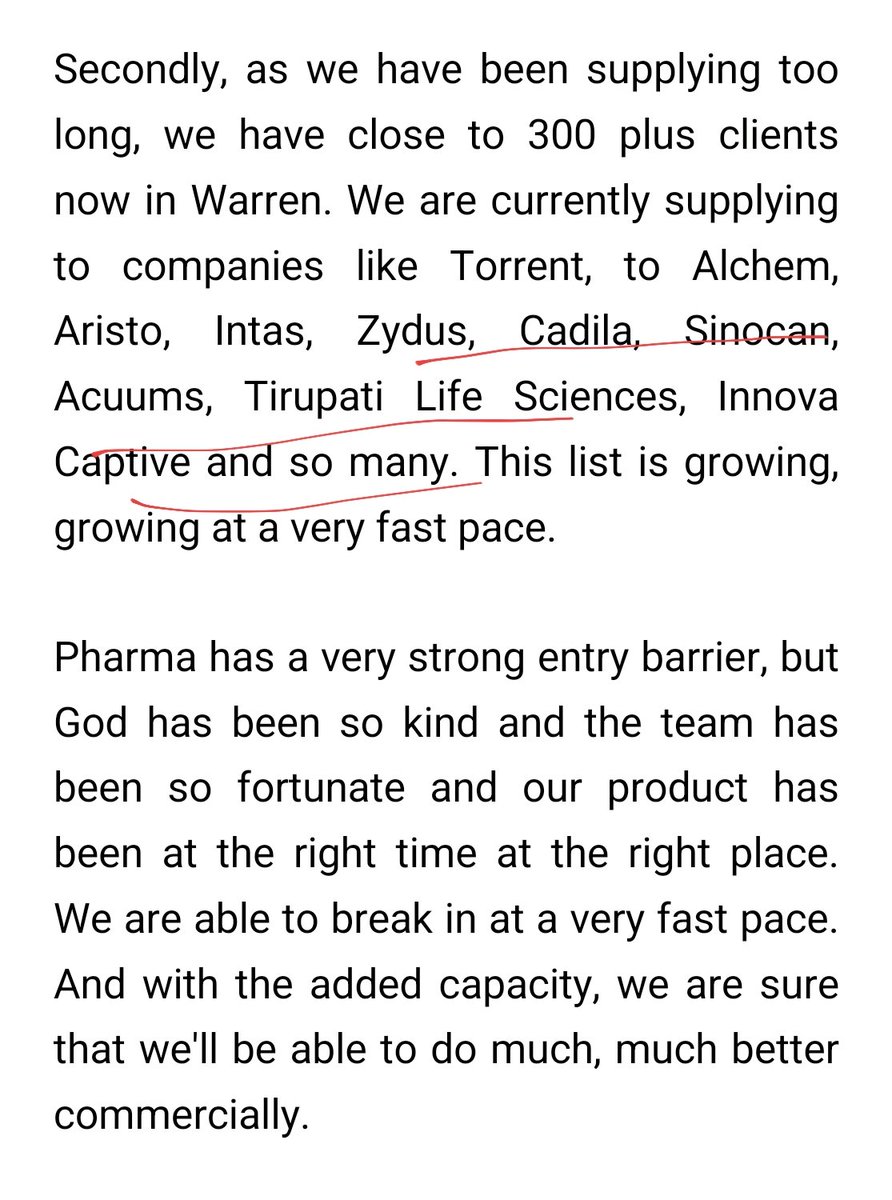
300+ clients in WAHREN
Scaling up well with new and reputed client additions
Clients like Torrent,Alkem,Intas,Zydus,Cadila, Akums, Innova Captab etc
WC days to improve in FY26

#CGraphics
Creative Graphics
H2FY25 Concall highlights:
The flexography business crossed ₹100 crores in topline for the first time.
Consol business crossed ₹250 crores in topline for the first time.
Capacity Expansion and New Initiatives:
•Flexography: They have eight factories across India. Two more factories have been recently announced and machines installed. These two new facilities are expected to be commercially workable in Q2. One of these new factories will be overseas, making the company no longer solely India-centric. They have significant existing capacity and are primarily focusing on geographical placement with new facilities to improve service, reduce turnaround time (TAT), and service clients closer to them. The current utilization level in Flexography is close to 60%.
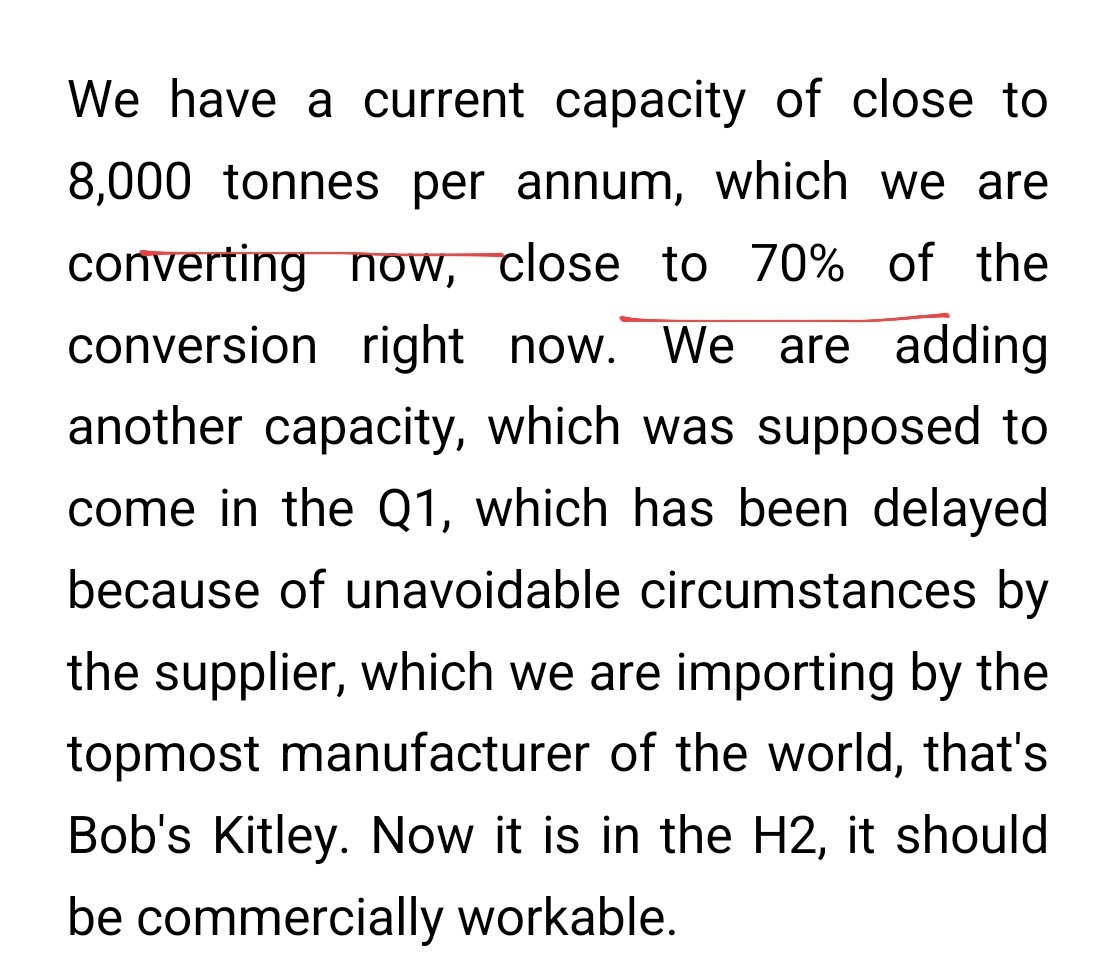
•Wahren: The average capacity utilization for the full year in the Wahren business was 50%. They are adding another capacity, which was expected in Q1 but has been delayed to H2 due to unavoidable circumstances by the supplier. This imported machine is from the topmost manufacturer in the world. The full impact of capacity utilization from the existing facility will be felt in FY25-26. They are targeting at least 80-80% capacity utilization in the existing Wahren facility due to strong demand and verification by big clients.
•New Product Lines (Acquired Assets): The company has procured two significant machines through NCLT from Radha Madhav Corporation limited at a significantly lower cost than new machinery (almost 10% of the cost).
oOne is a PVDC line. This is a four-stage packet run line, which is a very heavy investment if bought new. Commercial production is expected to start by Q2.
This line has a potential annual capacity of 12,000 tonnes. The average price is close to ₹250/kg. Full utilization of this capacity could potentially fetch ₹100-250 crores in revenue depending on the product mix. They are looking to utilize at least 40-50% of this capacity in the six months it will be live in FY26. There are certain approvals needed, and they are in the process of getting them.
PVDC has a very big export potential and should have high margins. Major competition in PVDC is largely ACG.
The second is a Tandem Exclusion machine. This machine is in the last stage of installation and should start commercial production by Q2. This line can make various products like different laminates.
Financials and Margins:
•Consolidated EBITDA margin was around 15% for the overall business.
•Creative Graphics (Flexography) had EBITDA margins of 18% plus, which is considered sustainable.
•Wahren business had EBITDA margins of 11% for the full year, but this was due to suboptimal utilization (average 50%). These margins are expected to improve as capacity utilization increases.
For the combined business, the expected sustainable EBITDA margin is in the mid-teens for the next two years.
The average margin will depend on the business mix, as Flexography is a high-teens margin business and Wahren is a low to mid-teens business. As capacity utilization increases, fixed costs are not expected to rise proportionally, which should lead to higher margins than the current second-half level.
Business Mix: The profile of the company is changing significantly. Until 15 months ago, it was 100% flexography. Now, Wahren business contributes 60% of the top line and 40% of the bottom line. This ratio is expected to continue increasing as they invest significantly in the Wahren side.
Growth Aspirations: The company stated they are looking to double their top line year on year. This might not happen every single year, but it is the desired trend. This aspiration includes potential contributions from the PVDC business. They aspire to become a major player in the packaging segment.
#SME #CGRAPHICS #CREATIVEGRAPHICS
Creative Graphics Solutions FY25 Concall Highlights:
👉FY 2026 & Future Outlook :
▫️ No specific guidance but expects to maintain similar growth YoY (FY25 vs FY24);
(Upcoming PVDC, higher Flexography & Alu-Alu utilization)
▫️Sustainable EBITDA ~14% (scope for increase to high teens with PVDC contribution)
👉Current projects and pipeline:
▫️Flexography utilization stable at ~60%. Potential scale-up in operations and utilization via new factories
▫️WAHREN (Alu-Alu) utilization increased from 50% in Sep'24 to ~70% and above , aided by Warehouse expansion
▫️Export orders for WAHREN already received and focus on key export markets of Africa, Qatar, Kuwait, Thailand etc to increase export revenue share to 10%+
▫️New client additions in Premedia as an added offering (3D graphics, animations, and mock-up designs; helping branding efforts for clients across industries)
▫️Pipeline:
💠PVDC (WAHREN) capacity is 12,000 tons/year, with 40-50% utilization expected in FY26 (starting Q3, ~Oct'25). Price realization at 250/kg generally, full utilization could yield revenues of 150cr+, though depends on market share and export pricing
💠Tandem Machine (WAHREN) already procured with commercial operations expected by H2 FY26
💠Alu-Alu (WAHREN) delivery of additional capacity machine delayed due to design changes. Dispatch expected (July'25); commercial operations by H2 FY26
💠Focus on expanding Flexography via 2 new factories (Domestic & overseas); expected commercial operations by Q2-Q3 FY26
👉 Others :
▫️Value of Noida plot undisclosed due to ongoing sale discussions; expected to fetch a “good premium.” Proceeds to be used for working capital / growth opportunities
▫️Standalone other current assets up 95% due to subsidiary investments post-IPO; on consolidated level due to net-off these look lower. (includes Supplier advances for expansion, GST receivables)
▫️Working capital funded by internal cash flows, IPO proceeds, and credit lines, avoiding significant debt
▫️No immediate Trump tariff / BIS norms cost impact; stock already built for volatility
▫️ Rough estimate market share in organized space : Flexography (60-70%), Alu-Alu (8-10%), PVDC (negligible)
▫️ Participated in exhibitions to build sales tie-ups and increase product awareness
▫️ Key competitors include SVAM TOYAL (Alu-Alu) & ACG / Caprihans (PVDC)
▫️ India / UK FTA remains an opportunity to be explored
Creative graphics
#CGraphics
Press release:
Business updates:
Solid growth in H2FY25 and FY25👏
FY25:
Rev at 256cr vs 135cr
PAT at 20.7cr vs 10.8cr
H2FY25:
Rev at 140cr vs 87cr
H1 at 117cr
PAT at 11.6cr vs 3.6cr
H1 at 9.1cr
PVC machine and Tandem machine:(WAHREN)
H2 commercialization
12000 MT Alu Alu machine:
Had to be delivered in March. Amow to be delivered by July 2025
H2 commissioning
Flexographic plates:
2 new factories to be launched in H2FY26
To be operational from Q2FY26


#Creative graphics
#CGraphics
Strong #Q4_2025 results 👇🏻
👉🏻Rev at 138cr vs 83cr, H1 at 113cr
👉🏻PAT at 12cr vs 4cr, H1 at 9cr
#stockmarketsindia
#MultiBagger

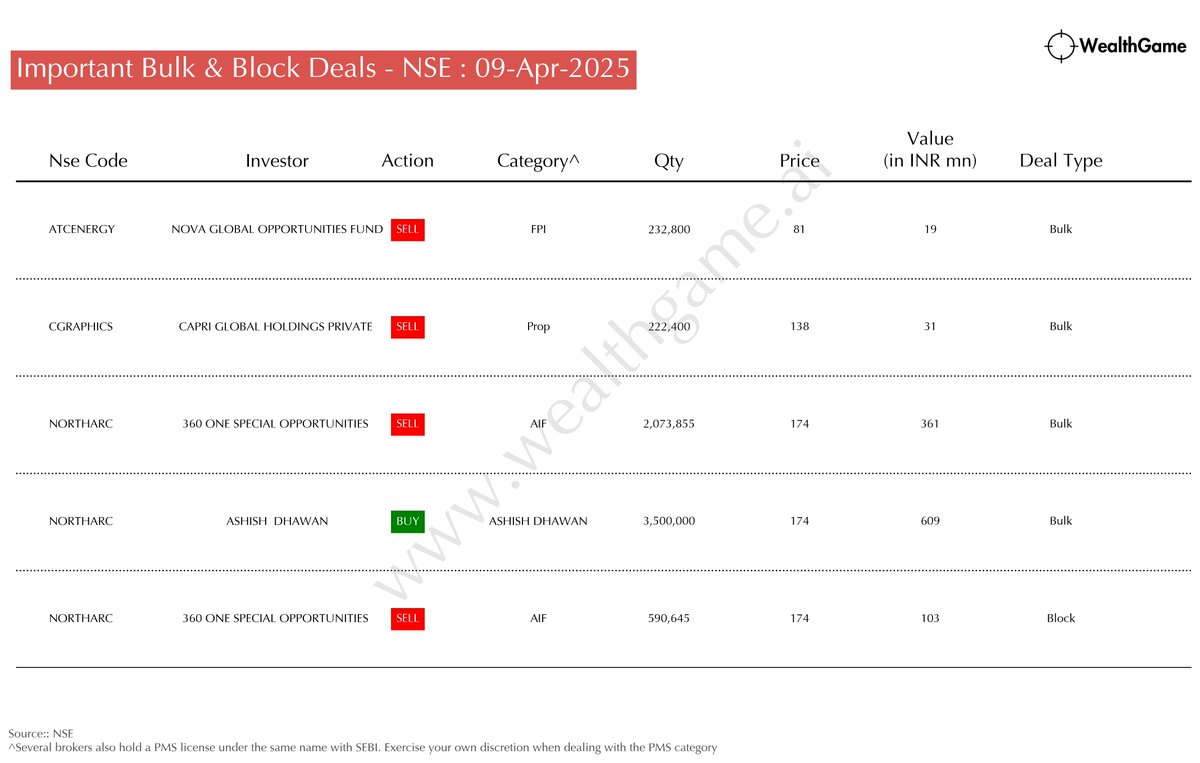
Significant Bulk/Block Deals on the NSE #NORTHARC #CGRAPHICS #ATCENERGY
For live corporate announcements, visit: https://t.co/CwHKSU2hEp
Last Seen Hashtags on Sotwe
Most Popular Users

Elon Musk 
@elonmusk
241.7M followers

Barack Obama
@barackobama
119M followers

Cristiano Ronaldo
@cristiano
114.5M followers

Donald J. Trump
@realdonaldtrump
111.9M followers

Narendra Modi
@narendramodi
107.2M followers

Rihanna
@rihanna
98.7M followers

NASA
@nasa
92.4M followers

Justin Bieber
@justinbieber
91.8M followers

KATY PERRY
@katyperry
90M followers

Taylor Swift
@taylorswift13
84M followers

Lady Gaga
@ladygaga
75.4M followers

Virat Kohli
@imvkohli
73.4M followers

Kim Kardashian
@kimkardashian
70.9M followers

YouTube
@youtube
68.8M followers

Neymar Jr
@neymarjr
66.4M followers

Bill Gates
@billgates
65.2M followers

Selena Gomez
@selenagomez
63.1M followers

The Ellen Show
@theellenshow
62.3M followers

CNN
@cnn
61.8M followers

X
@x
60.7M followers