

Top Tweets for #Capriglobal

#CapriGlobal
Shareholding Pattern -
Sep 2026
Promoter 59.92%
FII 13.00% (+4.79%)
DII 17.05% (-1.37%)
Public 10.03% (-3.43%)

#Good news 🗞️ :- FII's raise their stake by 2.59 % in #CapriGlobal
#StocksToBuy #MumbaiMeriJaan #GujaratiNews #StockMarketNews #Israël
Buy #CapriGlobal
* Cmp :- ₹251.63
* Looks #good at cmp
* I'm Expecting good 👍 Q2 results, above ₹260 stocks may show levels 🎚️ of ₹287 /297 /350 ++
* Keep any eye 👀
#StocksToBuy #StocksInFocus #TradingTips #StockMarketIndia #GujaratiNews #MumbaiSankalp2026
Buy #CapriGlobal
* Cmp :- ₹248
* Looks #good at cmp
* Above ₹260, stock may show levels 🎚️ of ₹287 / ₹297 / ₹350 ++
* Keep an eye 👀
#StocksToBuy #StocksInFocus #TradingTips #StockMarketIndia #GujaratiNews #MumbaiMeriJaan #ModiBhakt
Buy #CapriGlobal
* Cmp :- ₹246.75
* Looks #good at cmp
* Above ₹260, ₹287 / ₹297 / ₹350 possible
* Keep on radar
#StocksToBuy #Nifty #TradingTips #GujaratNews #MumbaiLocal

5 . Capri Global Capital Ltd 🔖
#capriglobal
🚀Change In FIIs Holding ~2.59%🚀
◉ Mar 2026~5.62% 🔥
◉ Jun 2026 ~8.21 % 💥


NSEIX Welcomes Capri Global Capital Ltd. on board.
Capri Global Ltd. has successfully listed USD 300 Mn, under the USD 1 Bn GMTN Programme
This marks another significant milestone in fostering sustainable finance and expanding global market opportunities.
#NSEIX #CapriGlobal #CapitalMarkets @balav901

3 . Capri Global
#capriglobal


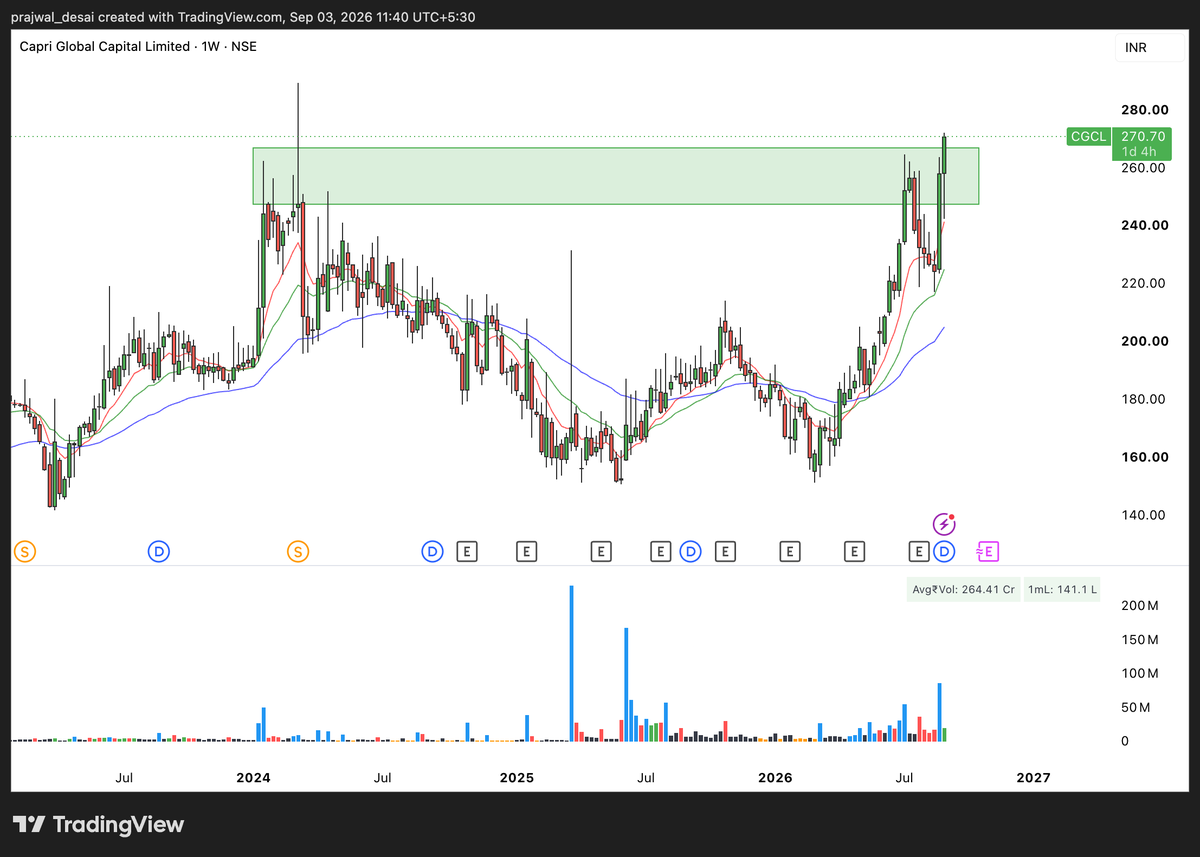
Capri global capital 📊
Study well
Coming out from a long consolidation along with good financials
Today’s closing is important
Must do study
Not a buy sell call
#Capriglobal #CGCL #Cgcl


On verge of breaking a long term base in #CGCL, market conditions arent great but going ahead with extremely low SL. Bought at 269 - Biased view.
#capriglobal #nse #stockstowatch

Capri Global Concludes Maiden $300M Dollar Bond Issue With 2.3x Oversubscription
https://t.co/1L6mkco6Mu
#CapriGlobal #CapriGlobalCapital #DollarBonds #BondIssuance #GMTNProgram #SeniorSecuredNotes #NBFC #DebtMarkets #OffshoreFunding #CapitalMarkets #StockMarket #IndianStocks


💰 #CapriGlobal taps the dollar #BondMarket for the first time.
📊 The #NBFC raised $300 million through its maiden US dollar bond issue, with the 2029 notes carrying a 7.55% coupon and attracting 2.3x subscription.
✍️ @anshul91_m reports.
https://t.co/LXBtyI58Qb
#OnCNBCTV18 | #CapriGlobal’s FY27 Outlook
MD, Rajesh Sharma To @CNBCTV18News
- Should be able to cross Rs 1 lakh AUM in the next 3 years
- Gold loan can be 50-55% of AUM in about 3 years
- May look at fund raise in next 2-4 quarters
@Reematendulkar @Nigel__Dsouza #CNBCTV18Market
WATCH:
https://t.co/CNcBQQqyxR

#CapriGlobal
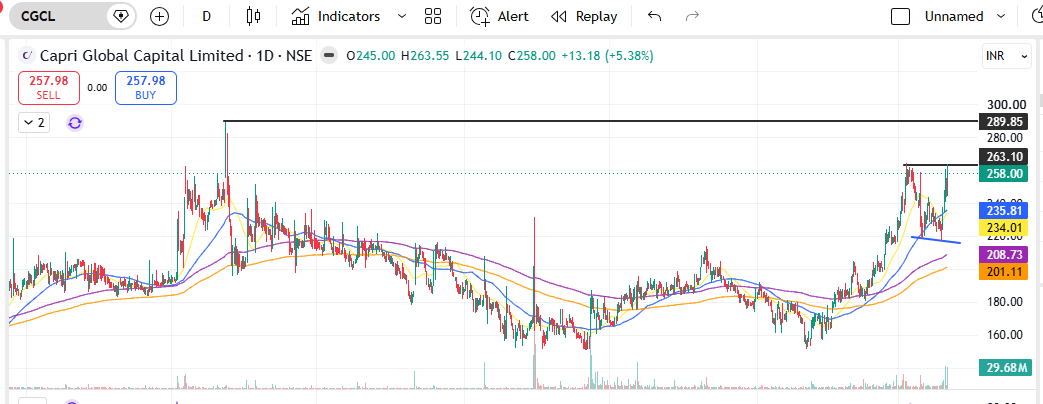
CGCL Above 260. Target 289/305
No Buy Sell Recommendation
D-Street Chatter | IT Stocks Gain In An Otherwise Lacklustre Day Of Trade
- Flows mixed with positive bias at FII desk
* #CapriGlobal #SPApparels #EPL #YatharthHospital #Emami buzzing in trade
@nimeshscnbc #CNBCTV18Market

🚀 CGCL — Potential Breakout Setup! 📈
CMP: 250
🛡️ SL: 225
🎯 Targets: 280 / 300 / 330 / 360
Price testing the major 250–260 resistance zone. Strong breakout and sustain above 260 could trigger further upside momentum. 🔥📈
#CGCL #capriglobal #SwingTrading #StockMarketIndia #IndianStocks #TechnicalAnalysis #StocksToWatch



Re-rating is ON!
#CapriGlobal

#StockToWatch 👉 #CapriGlobal
This ~₹15,600 Cr diversified NBFC has really tested patience of long-term holders over the last 30 months: stuck between ₹150-₹250 with zero wealth creation. If you bought this stock in August 2023 around ₹180-₹190, you are sitting on flat to slightly negative returns today at ₹165, watching your capital go nowhere for over two & half years. But here is what grabbed my attention after digging into the latest Q3 FY26 numbers:
This business is compounding profits at 33% over 3 yrs & 24% over 5 yrs, growing AUM at explosive 49% YoY to ₹30,406 crores, serving MSME, affordable housing, construction finance & gold loans : 4 resilient segments that feed off India's formalization story & credit-starved small businesses that banks struggle to underwrite profitably.
#CapriGlobal hit ₹232 in June 2024 & has corrected 30% to current ₹165, creating what could be a contrarian entry into a lender with 60% promoter holding (down from 70% due to QIP for growth capital), zero pledging, rapidly improving asset quality (gross NPA down from 2.3% to 1.28%, net NPA down to 0.74%), & financing margins expanding from 20% to 30%.
👉 My Thesis on this: For investors hunting mispriced growth in a market obsessed with momentum, this is not about chasing the next hot stock - this is about owning a diversified lending platform serving credit-starved segments (MSME avg ticket ₹25-30 lakhs, housing ₹10-15 lakhs, gold loans) that are compounding AUM at 46-50% while the market punishes it for past volatility & promoter dilution. Over the next 5-7 years, this ₹30,406 Cr AUM could realistically scale to ₹75,000-₹1,00,000 Cr as formalization, GST compliance & digital lending infrastructure unlock MSME credit demand across Tier 2, Tier 3 India.
👉 Why This Deserves Attention After 30 Months Of Going Nowhere:
Valuation Has Become Extremely Attractive After 30% Correction:
🏦 Stock at ₹165 trades at PE 18.5, massively below its 5-year average PE of 60.4 (yes, sixty!), which means you are getting this explosive grower at 70% discount to historical valuations after the market lost patience & dumped it from ₹232 peak just 8 months ago
🏦 PEG ratio 0.57 is where the screaming value sits - you are paying just ₹0.57 for every rupee of profit growth in a company compounding earnings at 33% over 3 years & delivering 99% profit growth YoY in Q3 FY26 (₹255 Cr vs ₹128 Cr), significantly cheaper than Bajaj Finance (0.92), Shriram Finance (0.44) or L&T Finance (0.53)
🏦 Price to book 2.34 on book value ₹69.4 looks incredibly reasonable when ROE is 11.8% & improving from 7-8% range in FY23-24 to current 12%, ROCE at 11.2%, generating solid returns on capital that justify premium valuations for a lender scaling AUM at 46-50% YoY
🏦 Dividend yield 0.12% is negligible because management is reinvesting almost every rupee into explosive AUM growth (46% TTM, 50% over 3 years), which is exactly what you want in a compounding story targeting ₹50,000-₹75,000 Cr AUM over next 5 years
🏦 Market cap ₹15,645 crores for TTM revenue ₹4,303 crores, trading at just 3.64 times sales versus peer median 4.06x, discount despite superior growth (46% sales CAGR TTM vs peer median 31%)
👉 The Business Is Firing On All Cylinders Despite Price Carnage:
⚙️ Sales CAGR 35% over 5 years, 50% over 3 years, 46% TTM, with profit CAGR accelerating from 24% (5-year) to 33% (3-year) to 120% TTM, showing the business has inflected into hypergrowth mode post-COVID as MSME lending, gold loans & construction finance scale rapidly
⚙️ Latest Q3 FY26 (Dec 2025) revenue ₹1,220 Cr (up 49% YoY), profit ₹255 Cr (up 99% YoY), EPS ₹2.65 (up 71% YoY), with financing margins exploding from 19% (Dec 2023) to 24% (Dec 2024) to 30% (Dec 2025), driven by shift toward higher-yielding MSME & gold loans (35-40% margins) away from lower-margin construction finance (15-18% margins)
⚙️ Gross NPA 1.28%, Net NPA 0.74% as of Sep 2025, down sharply from 2.32% gross / 1.65% net in Dec 2022, showing aggressive cleanup of legacy bad loans & underwriting discipline improvement after management overhaul & systems upgrade post-COVID
⚙️ FII holding jumped from 0.21% (Mar 2023) to 4.50% (Dec 2025) & DII holding surged from 13.62% to 20.11%, showing sophisticated institutional investors are accumulating aggressively while retail investors panic & sell, classic contrarian setup where smart money enters when sentiment is worst
⚙️ Diversified across four lending verticals - MSME (35-40% margin), affordable housing (25-30% margin), construction finance (15-18% margin), gold loans (40%+ margin), reducing concentration risk versus single-product NBFCs that get crushed when one segment turns
⚠️ Risks You Cannot Ignore:
30 months of wealth destruction (₹180 in Aug 2023 → ₹165 today, with peak of ₹232) has broken investor confidence completely, & there is no guarantee the sideways drift ends anytime soon - markets punish illiquid NBFCs with past governance concerns (promoter dilution from 70% to 60%) regardless of improving fundamentals. Low interest coverage 1.7x means any spike in funding costs or NPA provisioning could wipe out profitability quickly. Promoter holding declined 10% over 2 years due to repeated QIP dilutions for growth capital, raising questions about future equity raises at lower valuations. MSME & construction finance segments carry inherent concentration risk - if India's capex cycle stalls or GST formalization slows, the AUM growth story could decelerate sharply & NPAs could spike from current ultra-low 1.28% levels.
👉 Meri Conclusive Soch:
The risks are absolutely real & the 30-month sideways torture (₹180 → ₹232 → ₹165) may continue for another 12-18 months because markets reward momentum & punish illiquidity, especially in NBFCs where past governance concerns create skepticism regardless of improving fundamentals. But for contrarian investors building wealth over 5-10 years, this is exactly the kind of mispriced growth story that compounds wealth - a diversified lender serving four resilient segments, compounding AUM at 46-50%, profits at 33%, improving asset quality (NPA down from 2.3% to 1.28%), & run by promoters who are diluting themselves to fund growth rather than extracting dividends, showing long-term commitment.
Capri Global at PE 18.5 with PEG 0.57, you are paying just ₹0.57 for every rupee of profit growth in a company delivering 99% profit growth YoY, with FIIs & DIIs aggressively accumulating while retail investors capitulate after 30 months of frustration. This is not about timing a breakout - this is about owning infrastructure that serves India's ₹25-30 lakh crore MSME credit gap, formalization story, & affordable housing demand across Tier 2, Tier 3 cities, building wealth steadily as this ₹30,406 Cr AUM scales to ₹75,000-₹1,00,000 Cr over the next 5-7 years while everyone else chases momentum stocks trading at 40-50 PE.
👉The margin of safety sits in the valuation collapse (70% below 5-year average PE), improving fundamentals (margins 20% → 30%, NPA 2.3% → 1.28%), & institutional accumulation providing downside support. This needs extreme patience & tolerance for continued volatility, but for families saving for the next decade, the risk-reward at current ₹165 levels looks asymmetric - limited downside (₹140-150 worst case), significant upside (₹250-300 over 3-5 years) as the market eventually recognizes what is already visible in the numbers.
◾️Disclaimer: Not investment advice. Do your own research & consult a financial advisor. I do not currently hold this stock but am researching it for potential addition to my portfolio & may be biased. #InvestingInIndia #NBFC #ContrarianInvesting #ValueInvesting

Last Seen Hashtags on Sotwe
Most Popular Users

Elon Musk 
@elonmusk
241.7M followers

Barack Obama
@barackobama
119M followers

Cristiano Ronaldo
@cristiano
114.5M followers

Donald J. Trump
@realdonaldtrump
111.9M followers

Narendra Modi
@narendramodi
107.2M followers

Rihanna
@rihanna
98.7M followers

NASA
@nasa
92.4M followers

Justin Bieber
@justinbieber
91.8M followers

KATY PERRY
@katyperry
90M followers

Taylor Swift
@taylorswift13
84M followers

Lady Gaga
@ladygaga
75.5M followers

Virat Kohli
@imvkohli
73.5M followers

Kim Kardashian
@kimkardashian
70.9M followers

YouTube
@youtube
68.8M followers

Neymar Jr
@neymarjr
66.5M followers

Bill Gates
@billgates
65.2M followers

Selena Gomez
@selenagomez
63.1M followers

The Ellen Show
@theellenshow
62.3M followers

CNN
@cnn
61.8M followers

X
@x
60.7M followers