Top Tweets for #FREESPEECHREVOLUTION
||🌐 𝕏 || The rise of " 𝕏 " isn’t just growth—it’s a turning point. In a time when "Truth" is softened, buried, or reshaped, " 𝕏 " stands out by letting the "World Speak Freely". That’s why it’s winning.
|🔥 | #FreeSpeechRevolution
|⚡️| #DigitalTruthEra | #ElonMusk
@elonmusk EU censors thought fines would silence us, but X is unbreakable! Elon nails it—censorship backfires, turning tyrants into laughingstocks.
Who's next to defy the speech police? #FreeSpeechRevolution
#EUCensorshipFail
@TRobinsonNewEra @elonmusk In a world where speaking truth gets you silenced, Elon Musk is the wildcard we need—funding the fight so the rest of us don't have to whisper. Tommy, your battle is ours. UK, wake up: Persecution isn't protection. Who's next? #FreeSpeechRevolution #StandWithTommy #ElonTheHero
Parler’s comeback is LEGENDARY! Bigger user base, zero censorship, everything Big Tech and the media lied about? Exposed as fiction. Democrats' smears couldn't stop us. We're here to COMPETE and conquer.
Download now!
#ParlerDominates #LiesBusted #FreeSpeechRevolution
https://t.co/s7aUhCJKyQ
The power of one can change everything.
Dr James Lindsay breaks down the cultural shift after Twitter became X.
🎥 Watch here: https://t.co/toIVPt8T1Q
#ElonMusk #FreeSpeechRevolution #JamesLindsay
@Thompsonklay Legacy media often feels like a mouthpiece for the highest bidder. 🤐🔎 True journalism thrives when independent voices rise up—no corporate strings attached. The future is in the hands of citizen reporters. 🏴☠️✨ #CitizenJournalism #FreeSpeechRevolution
@elonmusk Forget Hamster Fight Club! 🐹🔥 The real movement for the people’s voice is happening with $DTI—where free speech is always in the ring! Let’s invest in what truly empowers the community. 💬🐶 #DTIFam #FreeSpeechRevolution
Creative
Hub
Inspiring
Real
Participation
Youthfulness
#MEMECOİNS #memecoinonsolana #CryptoInvestor #cryptoworld #AIInnovation #FreeSpeechRevolution #GrokAI #ChatGPT #ChirpyRevolution

Join the Free Speech Movement on Rumble Studio! #PlayAPart #FreeSpeechRevolution
#RumbleStudio #FreeSpeechMatters #VoiceForChange #ContributeAVerse #RumbleApp #JoinTheMovement #MakeYourVoiceHeard #StandForFreeSpeech #DigitalRevolution #ContentCreators
We're building #BaaanaMassik & the #MemeingOfLife on #PulseChain to support the #DeFiRevolution
#TheTogethering
Til all are one
#BlockchainRevolution #CryptoRevolution #FreeSpeechRevolution
#PulseX $eth $sol $pepe $shib $doge $bonk #NFT #ethereum #solana #Base #memecoins #Teddybear #PEPE #SHIB #FLOKI #Atropa #DOGE #BONK #CryptoArt #WIF #AIArtCommuity #Bitcoin $DWB #DWB $Atropa #Crypto $BAANA
There's room for every #Crypto community to win together.
Tell your friends about #BaaanaMassik & the #MemeingOfLife on #PulseChain.
Let's onboard the world 🔥🚀
Til all are one.
#TheTogethering
#BlockchainRevolution #CryptoRevolution #DeFiRevolution #FreeSpeechRevolution
#PulseX #HEX $HEX
$eth $sol $pepe $shib $doge $bonk #NFT #ethereum #solana #DWB $DWB #WIF $WIF #memecoins #Teddybear #PEPE #SHIB #FLOKI #Atropa #DOGE #BONK #CryptoArt #Crypto #AIArtCommuity #Bitcoin $Atropa $DAI #Crypto $BAANA
We will be announcing the winner of the ship naming competition in a few hours.
Thanks to all that participated.
Here's a clip with some footage of the Bitcoin Mining Corporation lead cruiser while you're waiting to hear the results of the competition.
Like, share & follow
Entering a new phase of production for #BaaanaMassik & the #MemeingOfLife on #PulseChain
Still a ton to be done, but absolutely enjoyable thing to be doing.
Join us for #TheTogethering
#BlockchainRevolution #CryptoRevolution #DeFiRevolution #FreeSpeechRevolution
$eth $sol $pepe $shib $doge $bonk #NFT #ethereum #solana #memecoins #Teddybear #PEPE #SHIB #FLOKI #Atropa #DOGE #BONK #CryptoArt #Crypto #AIArtCommuity #Bitcoin $Atropa $pDAI #Crypto $BAANA
"In our obscurity, in all this vastness, there is no hint that help will come from elsewhere to save us from ourselves."
- Carl Sagan
#BaaanaMassik & the #MemeingOfLife on #PulseChain
Join us for #TheTogethering
#BlockchainRevolution #CryptoRevolution #DeFiRevolution #FreeSpeechRevolution
$eth $sol $pepe $shib $doge $bonk #NFT #ethereum #solana #memecoins #Teddybear #PEPE #SHIB #FLOKI #Atropa #DOGE #BONK #CryptoArt #Crypto #AIArtCommuity #Bitcoin $Atropa $pDAI #Crypto $BAANA
This staking pool starts in 2 days & competition in the pool is still relatively low.
#BaaanaMassik & the #MemeingOfLife on #PulseChain
#TheTogethering
#BlockchainRevolution #CryptoRevolution #DeFiRevolution #FreeSpeechRevolution
$eth $sol $pepe $shib $doge $bonk #NFT #ethereum #solana #memecoins #Teddybear #PEPE #SHIB #FLOKI #Atropa #DOGE #BONK #CryptoArt #Crypto #AIArtCommuity #Bitcoin $Atropa $pDAI
🔥 100k $BAANA giveaway🔥
($2,100 / 18M $PLS)
Feb Staking Pools:
Starts: 02/14/2024
Ends: 03/16/2024
Visit 👉 https://t.co/7nVsEbUOdL
• Pool APY today = 332% APY
• market cap <$500k
• ~330 holders
• 🔥 41% LP burned in main $BAANA/ $PLS pair 🔥
#BaaanaMassik & the #MemeingOfLife on #PulseChain
#TheTogethering
#BlockchainRevolution #CryptoRevolution #DeFiRevolution #FreeSpeechRevolution
$eth $sol $pepe $shib $doge $bonk #NFT #ethereum #solana #memecoins #Teddybear #PEPE #SHIB #FLOKI #Atropa #DOGE #BONK #CryptoArt #Crypto #AIArtCommuity #Bitcoin $Atropa $pDAI

If you're interested in onboarding normies into #Crypto with non-financial, but wholesome content, #BaaanaMassik & the #MemeingOfLife on #PulseChain has you covered. 👍
#TheTogethering is soon
#BlockchainRevolution #CryptoRevolution #DeFiRevolution #FreeSpeechRevolution #memecoins #Teddybear #PEPE #SHIB #FLOKI #Atropa #DOGE #BONK #CryptoArt #Crypto #AIArtCommuity #Bitcoin $Atropa $pDAI #ethereum #solana #cardano
Introduction to season 1: A dream of two earths.
#BaaanaMassik & the #MemeingOfLife on #PulseChain
#TheTogethering is soon
Til all are one.
Like, follow @BaaanaMassik & share
$BAANA #1000xGems #1000xgem #NFT #NFTcollections #ethereum #solana #PEPE #SHIB #FLOKI #DOGE #BONK #BonkGrok #CryptoArt #Crypto #AI #AIfilms #AIart #AIArtistCommunity
The Awakening
#BaaanaMassik & the #MemeingOfLife on #PulseChain
#TheTogethering
#BlockchainRevolution #CryptoRevolution #DeFiRevolution #FreeSpeechRevolution #TheGreatReset #NFT #ethereum #solana #memecoins #Teddybear #PEPE #SHIB #FLOKI #Atropa #DOGE #BONK #CryptoArt #Crypto #AIArtCommuity #Bitcoin $Atropa $pDAI
If you're interested in #cryptocurrency Vs the government, this is a must read!
#CryptoRevolution #BlockchainRevolution #DeFiRevolution #FreeSpeechRevolution
Welcome back to #PulseChainLawSchool.
Are you ready to look for some fraud today?
I hope everyone has seen @THoSdocumentary by now so you get that!
Well, I've read this Complaint more times than you have, and I can’t f**king find any fraud. Maybe you’ll have better luck.
Let’s take it from the top. What is fraud anyway?
Well, there are lots of different types, which really doesn’t help you one bit, does it? So let’s focus just on the one at issue in Richard’s case – securities fraud.
I was hoping to have this done a week ago, but the rabbit holes I’ve had to go down almost made me give up on the topic completely and post some cat videos instead. But since I have way too much time on my hands, and the NHL is on break for the all-star game, I decided to jump back in and try and decipher some of it for you.
To grossly oversimplify things, the SEC can bring an action for securities fraud, but so can you or I. When you or I do it, it’s called a private right of action, and we become the Plaintiffs. Because government likes to make the rules, they made the rules for the SEC simpler than the rules for private plaintiffs. Essentially, the SEC gets to short-cut a few things in order to win that you or I would have to prove in court. I was able to find a matrix outlining what needs to be proven in different private securities laws claims, and I posted it below. Since I’m not being paid for any of this, I’m not reading it. I like y’all a lot, but not enough to kill off that many brain cells.
So I went back to researching case law, and after sifting through myriad cases, all of which were painfully boring, I focused on a few 2nd Circuit cases, since that’s what’s important here. And recall that the fraud claims against Richard are under 10b-5 and 17(a)(1) and (a)(3). You can google them the next time you can’t sleep.
In SEC v. First Jersey Securities, 101 F.3d 1450 (2nd Cir 1996), the Court stated that in order to establish liability under Rule 10b-5, the Plaintiff “is required to prove that in connection with the purchase or sale of a security the defendant, acting with scienter, made a material misrepresentation (or a material omission if the defendant had a duty to speak) or used a fraudulent device.” A fraudulent device here doesn’t mean a fake iPhone. It means some sort of investment device.
So what the hell is “scienter”? It means “intent to deceive, manipulate, or defraud.” This is also a quote from SEC v First Jersey. It’s a fancy way of saying someone intended to do something they knew was bad.
Now here’s where the SEC gets a break. In order to prove a claim under 17(a)(3) – one of the claims against Richard, you and I would have to prove scienter. The SEC doesn’t. Awesome, right? That’s what happens when government entities write the rules for government entities. At least the SEC still has to prove scienter for its 10b-5 and 17(a)(1) claims, so there’s that. It took the US Supreme Court to make that happen, though, in Aaron v SEC, 446 US 680 (1980).
All of that to get to the point. Richard’s attorneys claim that the SEC didn’t allege its fraud claims properly in the Complaint. And they’re right. You can’t plead fraud the same way you plead negligence or a breach of contract. Rule 9(b) is what we call a “heightened pleading standard,” which means you can’t just say “all the shit I put in the facts section above applies to this fraud claim.” Doesn’t work. But that’s what the SEC did, and that’s why Richard’s attorneys said they’ll raise this issue.
So what do you have to do to plead fraud then? I’m glad you asked. The 2nd Circuit has an answer for us. It said "securities fraud complaints [must] specify each misleading statement . . . [and] state with particularity facts giving rise to a strong inference that the defendant acted with the required state of mind."
And in order to plead scienter (state of mind) “so as to survive a motion to dismiss, a plaintiff must state with particularity facts giving rise to a strong inference that the defendant acted with the required state of mind by either alleging facts (1) showing that the defendants had both motive and opportunity to commit the fraud or (2) constituting strong circumstantial evidence of conscious misbehavior or recklessness."
You asleep yet? I just about nodded off myself.
Fine. If you don’t remember anything else, just get the principle here, which is that when you plead fraud, you must tell someone the exact reason you’re suing them, so they know what specific statement(s) they’re supposed to be defending.
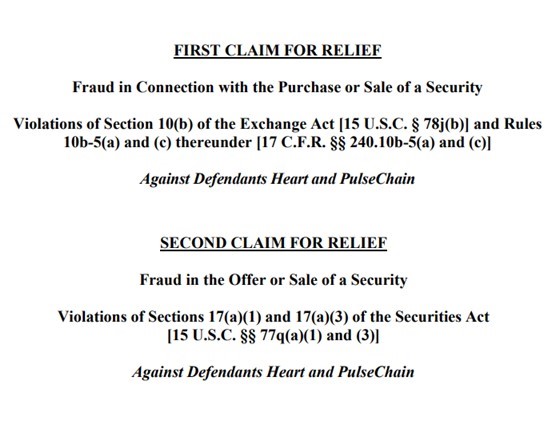
Anyway, to close this out, the SEC pled claims 1 and 2 this way:
“Plaintiff re-alleges and incorporates paragraphs 1 through 76 of this Complaint by reference as if set forth verbatim in this Claim.”
I actually found a case where Plaintiffs did exactly this and got slapped down, then I lost it, couldn’t find it again, and eventually gave up looking in order to get this thing done. But basically, the court said you can’t do that in fraud claims (it’s generally ok in most other types of claims, fyi). But when pleading fraud, you have to tell someone the specific things they said that you believe were fraudulent, and why you believe the defendant knew they were fraudulent. You can’t just point to a few dozen or few hundred paragraphs and say “yeah, it’s somewhere in there, go figure it out.”
Bottom line:
1. The SEC didn’t draft its fraud claims properly.
2. This is a solid argument that I believe RH should prevail on.
3. Unfortunately, the likely remedy is that the SEC will get another swing at redrafting their Complaint.
4. If the SEC can’t cure the deficiency properly, you may see a second motion to dismiss on this issue.
5. All of the above assumes that the court has personal jurisdiction over Richard, which is an open question that will also be raised by his attorneys. Remember, no personal jurisdiction, no case.
6. All of the above also assumes that these things are securities, which is also an open question that I expect will be litigated in October (and perhaps again throughout this case if necessary).
Strictly my guess. I could be wrong. I’m wrong a lot. Nothing I say is legal advice.
But I honestly can’t wait to see what Richard’s all-star team comes up with in their motion.
#HEX #PLS #PLSX
![NuclearHerbs's tweet photo. Welcome back to #PulseChainLawSchool.
Are you ready to look for some fraud today?
I hope everyone has seen @THoSdocumentary by now so you get that!
Well, I've read this Complaint more times than you have, and I can’t f**king find any fraud. Maybe you’ll have better luck.
Let’s take it from the top. What is fraud anyway?
Well, there are lots of different types, which really doesn’t help you one bit, does it? So let’s focus just on the one at issue in Richard’s case – securities fraud.
I was hoping to have this done a week ago, but the rabbit holes I’ve had to go down almost made me give up on the topic completely and post some cat videos instead. But since I have way too much time on my hands, and the NHL is on break for the all-star game, I decided to jump back in and try and decipher some of it for you.
To grossly oversimplify things, the SEC can bring an action for securities fraud, but so can you or I. When you or I do it, it’s called a private right of action, and we become the Plaintiffs. Because government likes to make the rules, they made the rules for the SEC simpler than the rules for private plaintiffs. Essentially, the SEC gets to short-cut a few things in order to win that you or I would have to prove in court. I was able to find a matrix outlining what needs to be proven in different private securities laws claims, and I posted it below. Since I’m not being paid for any of this, I’m not reading it. I like y’all a lot, but not enough to kill off that many brain cells.
So I went back to researching case law, and after sifting through myriad cases, all of which were painfully boring, I focused on a few 2nd Circuit cases, since that’s what’s important here. And recall that the fraud claims against Richard are under 10b-5 and 17(a)(1) and (a)(3). You can google them the next time you can’t sleep.
In SEC v. First Jersey Securities, 101 F.3d 1450 (2nd Cir 1996), the Court stated that in order to establish liability under Rule 10b-5, the Plaintiff “is required to prove that in connection with the purchase or sale of a security the defendant, acting with scienter, made a material misrepresentation (or a material omission if the defendant had a duty to speak) or used a fraudulent device.” A fraudulent device here doesn’t mean a fake iPhone. It means some sort of investment device.
So what the hell is “scienter”? It means “intent to deceive, manipulate, or defraud.” This is also a quote from SEC v First Jersey. It’s a fancy way of saying someone intended to do something they knew was bad.
Now here’s where the SEC gets a break. In order to prove a claim under 17(a)(3) – one of the claims against Richard, you and I would have to prove scienter. The SEC doesn’t. Awesome, right? That’s what happens when government entities write the rules for government entities. At least the SEC still has to prove scienter for its 10b-5 and 17(a)(1) claims, so there’s that. It took the US Supreme Court to make that happen, though, in Aaron v SEC, 446 US 680 (1980).
All of that to get to the point. Richard’s attorneys claim that the SEC didn’t allege its fraud claims properly in the Complaint. And they’re right. You can’t plead fraud the same way you plead negligence or a breach of contract. Rule 9(b) is what we call a “heightened pleading standard,” which means you can’t just say “all the shit I put in the facts section above applies to this fraud claim.” Doesn’t work. But that’s what the SEC did, and that’s why Richard’s attorneys said they’ll raise this issue.
So what do you have to do to plead fraud then? I’m glad you asked. The 2nd Circuit has an answer for us. It said "securities fraud complaints [must] specify each misleading statement . . . [and] state with particularity facts giving rise to a strong inference that the defendant acted with the required state of mind."
And in order to plead scienter (state of mind) “so as to survive a motion to dismiss, a plaintiff must state with particularity facts giving rise to a strong inference that the defendant acted with the required state of mind by either alleging facts (1) showing that the defendants had both motive and opportunity to commit the fraud or (2) constituting strong circumstantial evidence of conscious misbehavior or recklessness."
You asleep yet? I just about nodded off myself.
Fine. If you don’t remember anything else, just get the principle here, which is that when you plead fraud, you must tell someone the exact reason you’re suing them, so they know what specific statement(s) they’re supposed to be defending.
Anyway, to close this out, the SEC pled claims 1 and 2 this way:
“Plaintiff re-alleges and incorporates paragraphs 1 through 76 of this Complaint by reference as if set forth verbatim in this Claim.”
I actually found a case where Plaintiffs did exactly this and got slapped down, then I lost it, couldn’t find it again, and eventually gave up looking in order to get this thing done. But basically, the court said you can’t do that in fraud claims (it’s generally ok in most other types of claims, fyi). But when pleading fraud, you have to tell someone the specific things they said that you believe were fraudulent, and why you believe the defendant knew they were fraudulent. You can’t just point to a few dozen or few hundred paragraphs and say “yeah, it’s somewhere in there, go figure it out.”
Bottom line:
1. The SEC didn’t draft its fraud claims properly.
2. This is a solid argument that I believe RH should prevail on.
3. Unfortunately, the likely remedy is that the SEC will get another swing at redrafting their Complaint.
4. If the SEC can’t cure the deficiency properly, you may see a second motion to dismiss on this issue.
5. All of the above assumes that the court has personal jurisdiction over Richard, which is an open question that will also be raised by his attorneys. Remember, no personal jurisdiction, no case.
6. All of the above also assumes that these things are securities, which is also an open question that I expect will be litigated in October (and perhaps again throughout this case if necessary).
Strictly my guess. I could be wrong. I’m wrong a lot. Nothing I say is legal advice.
But I honestly can’t wait to see what Richard’s all-star team comes up with in their motion.
#HEX #PLS #PLSX](https://pbs.twimg.com/media/GFXILodbUAA0AA7.jpg)
LFGOOOOOO 🔥🚀
Thanks @PulseDomains_ ! These are absolutely 🔥
Can't wait to see #PulseChain dominating #Web3 & #DeFi with #PulseDomains!
#CryptoRevolution #BlockchainRevolution #DeFiRevolution #FreeSpeechRevolution

There's room for everyone within the #CryptoRevolution , the #BlockchainRevolution , the #DeFiRevolution, the #FreeSpeechRevolution.
Being active, educating, growing the pie together, is what will bring about change.
There's room for everyone within the #CryptoRevolution , the #BlockchainRevolution , the #DeFiRevolution, the #FreeSpeechRevolution.
Being active, educating, growing the pie together, is what will bring about change.
Most Popular Users

Elon Musk 
@elonmusk
241.7M followers

Barack Obama 
@barackobama
119M followers

Cristiano Ronaldo 
@cristiano
114.4M followers

Donald J. Trump 
@realdonaldtrump
111.9M followers

Narendra Modi 
@narendramodi
107.2M followers

Rihanna 
@rihanna
98.7M followers

NASA 
@nasa
92.4M followers

Justin Bieber 
@justinbieber
91.8M followers

KATY PERRY 
@katyperry
90M followers

Taylor Swift 
@taylorswift13
83.9M followers

Lady Gaga 
@ladygaga
75.4M followers

Virat Kohli 
@imvkohli
73.4M followers

Kim Kardashian 
@kimkardashian
70.9M followers

YouTube 
@youtube
68.8M followers

Neymar Jr 
@neymarjr
66.4M followers

Bill Gates 
@billgates
65.2M followers

Selena Gomez 
@selenagomez
63.1M followers

The Ellen Show
@theellenshow
62.3M followers

CNN 
@cnn
61.8M followers

X 
@x
60.7M followers


![NuclearHerbs's tweet photo. Welcome back to #PulseChainLawSchool.
Are you ready to look for some fraud today?
I hope everyone has seen @THoSdocumentary by now so you get that!
Well, I've read this Complaint more times than you have, and I can’t f**king find any fraud. Maybe you’ll have better luck.
Let’s take it from the top. What is fraud anyway?
Well, there are lots of different types, which really doesn’t help you one bit, does it? So let’s focus just on the one at issue in Richard’s case – securities fraud.
I was hoping to have this done a week ago, but the rabbit holes I’ve had to go down almost made me give up on the topic completely and post some cat videos instead. But since I have way too much time on my hands, and the NHL is on break for the all-star game, I decided to jump back in and try and decipher some of it for you.
To grossly oversimplify things, the SEC can bring an action for securities fraud, but so can you or I. When you or I do it, it’s called a private right of action, and we become the Plaintiffs. Because government likes to make the rules, they made the rules for the SEC simpler than the rules for private plaintiffs. Essentially, the SEC gets to short-cut a few things in order to win that you or I would have to prove in court. I was able to find a matrix outlining what needs to be proven in different private securities laws claims, and I posted it below. Since I’m not being paid for any of this, I’m not reading it. I like y’all a lot, but not enough to kill off that many brain cells.
So I went back to researching case law, and after sifting through myriad cases, all of which were painfully boring, I focused on a few 2nd Circuit cases, since that’s what’s important here. And recall that the fraud claims against Richard are under 10b-5 and 17(a)(1) and (a)(3). You can google them the next time you can’t sleep.
In SEC v. First Jersey Securities, 101 F.3d 1450 (2nd Cir 1996), the Court stated that in order to establish liability under Rule 10b-5, the Plaintiff “is required to prove that in connection with the purchase or sale of a security the defendant, acting with scienter, made a material misrepresentation (or a material omission if the defendant had a duty to speak) or used a fraudulent device.” A fraudulent device here doesn’t mean a fake iPhone. It means some sort of investment device.
So what the hell is “scienter”? It means “intent to deceive, manipulate, or defraud.” This is also a quote from SEC v First Jersey. It’s a fancy way of saying someone intended to do something they knew was bad.
Now here’s where the SEC gets a break. In order to prove a claim under 17(a)(3) – one of the claims against Richard, you and I would have to prove scienter. The SEC doesn’t. Awesome, right? That’s what happens when government entities write the rules for government entities. At least the SEC still has to prove scienter for its 10b-5 and 17(a)(1) claims, so there’s that. It took the US Supreme Court to make that happen, though, in Aaron v SEC, 446 US 680 (1980).
All of that to get to the point. Richard’s attorneys claim that the SEC didn’t allege its fraud claims properly in the Complaint. And they’re right. You can’t plead fraud the same way you plead negligence or a breach of contract. Rule 9(b) is what we call a “heightened pleading standard,” which means you can’t just say “all the shit I put in the facts section above applies to this fraud claim.” Doesn’t work. But that’s what the SEC did, and that’s why Richard’s attorneys said they’ll raise this issue.
So what do you have to do to plead fraud then? I’m glad you asked. The 2nd Circuit has an answer for us. It said "securities fraud complaints [must] specify each misleading statement . . . [and] state with particularity facts giving rise to a strong inference that the defendant acted with the required state of mind."
And in order to plead scienter (state of mind) “so as to survive a motion to dismiss, a plaintiff must state with particularity facts giving rise to a strong inference that the defendant acted with the required state of mind by either alleging facts (1) showing that the defendants had both motive and opportunity to commit the fraud or (2) constituting strong circumstantial evidence of conscious misbehavior or recklessness."
You asleep yet? I just about nodded off myself.
Fine. If you don’t remember anything else, just get the principle here, which is that when you plead fraud, you must tell someone the exact reason you’re suing them, so they know what specific statement(s) they’re supposed to be defending.
Anyway, to close this out, the SEC pled claims 1 and 2 this way:
“Plaintiff re-alleges and incorporates paragraphs 1 through 76 of this Complaint by reference as if set forth verbatim in this Claim.”
I actually found a case where Plaintiffs did exactly this and got slapped down, then I lost it, couldn’t find it again, and eventually gave up looking in order to get this thing done. But basically, the court said you can’t do that in fraud claims (it’s generally ok in most other types of claims, fyi). But when pleading fraud, you have to tell someone the specific things they said that you believe were fraudulent, and why you believe the defendant knew they were fraudulent. You can’t just point to a few dozen or few hundred paragraphs and say “yeah, it’s somewhere in there, go figure it out.”
Bottom line:
1. The SEC didn’t draft its fraud claims properly.
2. This is a solid argument that I believe RH should prevail on.
3. Unfortunately, the likely remedy is that the SEC will get another swing at redrafting their Complaint.
4. If the SEC can’t cure the deficiency properly, you may see a second motion to dismiss on this issue.
5. All of the above assumes that the court has personal jurisdiction over Richard, which is an open question that will also be raised by his attorneys. Remember, no personal jurisdiction, no case.
6. All of the above also assumes that these things are securities, which is also an open question that I expect will be litigated in October (and perhaps again throughout this case if necessary).
Strictly my guess. I could be wrong. I’m wrong a lot. Nothing I say is legal advice.
But I honestly can’t wait to see what Richard’s all-star team comes up with in their motion.
#HEX #PLS #PLSX](https://pbs.twimg.com/media/GFXIHDmaQAALfFY.jpg)
![NuclearHerbs's tweet photo. Welcome back to #PulseChainLawSchool.
Are you ready to look for some fraud today?
I hope everyone has seen @THoSdocumentary by now so you get that!
Well, I've read this Complaint more times than you have, and I can’t f**king find any fraud. Maybe you’ll have better luck.
Let’s take it from the top. What is fraud anyway?
Well, there are lots of different types, which really doesn’t help you one bit, does it? So let’s focus just on the one at issue in Richard’s case – securities fraud.
I was hoping to have this done a week ago, but the rabbit holes I’ve had to go down almost made me give up on the topic completely and post some cat videos instead. But since I have way too much time on my hands, and the NHL is on break for the all-star game, I decided to jump back in and try and decipher some of it for you.
To grossly oversimplify things, the SEC can bring an action for securities fraud, but so can you or I. When you or I do it, it’s called a private right of action, and we become the Plaintiffs. Because government likes to make the rules, they made the rules for the SEC simpler than the rules for private plaintiffs. Essentially, the SEC gets to short-cut a few things in order to win that you or I would have to prove in court. I was able to find a matrix outlining what needs to be proven in different private securities laws claims, and I posted it below. Since I’m not being paid for any of this, I’m not reading it. I like y’all a lot, but not enough to kill off that many brain cells.
So I went back to researching case law, and after sifting through myriad cases, all of which were painfully boring, I focused on a few 2nd Circuit cases, since that’s what’s important here. And recall that the fraud claims against Richard are under 10b-5 and 17(a)(1) and (a)(3). You can google them the next time you can’t sleep.
In SEC v. First Jersey Securities, 101 F.3d 1450 (2nd Cir 1996), the Court stated that in order to establish liability under Rule 10b-5, the Plaintiff “is required to prove that in connection with the purchase or sale of a security the defendant, acting with scienter, made a material misrepresentation (or a material omission if the defendant had a duty to speak) or used a fraudulent device.” A fraudulent device here doesn’t mean a fake iPhone. It means some sort of investment device.
So what the hell is “scienter”? It means “intent to deceive, manipulate, or defraud.” This is also a quote from SEC v First Jersey. It’s a fancy way of saying someone intended to do something they knew was bad.
Now here’s where the SEC gets a break. In order to prove a claim under 17(a)(3) – one of the claims against Richard, you and I would have to prove scienter. The SEC doesn’t. Awesome, right? That’s what happens when government entities write the rules for government entities. At least the SEC still has to prove scienter for its 10b-5 and 17(a)(1) claims, so there’s that. It took the US Supreme Court to make that happen, though, in Aaron v SEC, 446 US 680 (1980).
All of that to get to the point. Richard’s attorneys claim that the SEC didn’t allege its fraud claims properly in the Complaint. And they’re right. You can’t plead fraud the same way you plead negligence or a breach of contract. Rule 9(b) is what we call a “heightened pleading standard,” which means you can’t just say “all the shit I put in the facts section above applies to this fraud claim.” Doesn’t work. But that’s what the SEC did, and that’s why Richard’s attorneys said they’ll raise this issue.
So what do you have to do to plead fraud then? I’m glad you asked. The 2nd Circuit has an answer for us. It said "securities fraud complaints [must] specify each misleading statement . . . [and] state with particularity facts giving rise to a strong inference that the defendant acted with the required state of mind."
And in order to plead scienter (state of mind) “so as to survive a motion to dismiss, a plaintiff must state with particularity facts giving rise to a strong inference that the defendant acted with the required state of mind by either alleging facts (1) showing that the defendants had both motive and opportunity to commit the fraud or (2) constituting strong circumstantial evidence of conscious misbehavior or recklessness."
You asleep yet? I just about nodded off myself.
Fine. If you don’t remember anything else, just get the principle here, which is that when you plead fraud, you must tell someone the exact reason you’re suing them, so they know what specific statement(s) they’re supposed to be defending.
Anyway, to close this out, the SEC pled claims 1 and 2 this way:
“Plaintiff re-alleges and incorporates paragraphs 1 through 76 of this Complaint by reference as if set forth verbatim in this Claim.”
I actually found a case where Plaintiffs did exactly this and got slapped down, then I lost it, couldn’t find it again, and eventually gave up looking in order to get this thing done. But basically, the court said you can’t do that in fraud claims (it’s generally ok in most other types of claims, fyi). But when pleading fraud, you have to tell someone the specific things they said that you believe were fraudulent, and why you believe the defendant knew they were fraudulent. You can’t just point to a few dozen or few hundred paragraphs and say “yeah, it’s somewhere in there, go figure it out.”
Bottom line:
1. The SEC didn’t draft its fraud claims properly.
2. This is a solid argument that I believe RH should prevail on.
3. Unfortunately, the likely remedy is that the SEC will get another swing at redrafting their Complaint.
4. If the SEC can’t cure the deficiency properly, you may see a second motion to dismiss on this issue.
5. All of the above assumes that the court has personal jurisdiction over Richard, which is an open question that will also be raised by his attorneys. Remember, no personal jurisdiction, no case.
6. All of the above also assumes that these things are securities, which is also an open question that I expect will be litigated in October (and perhaps again throughout this case if necessary).
Strictly my guess. I could be wrong. I’m wrong a lot. Nothing I say is legal advice.
But I honestly can’t wait to see what Richard’s all-star team comes up with in their motion.
#HEX #PLS #PLSX](https://pbs.twimg.com/media/GFXHtEiaEAAIz9w.jpg)
![NuclearHerbs's tweet photo. Welcome back to #PulseChainLawSchool.
Are you ready to look for some fraud today?
I hope everyone has seen @THoSdocumentary by now so you get that!
Well, I've read this Complaint more times than you have, and I can’t f**king find any fraud. Maybe you’ll have better luck.
Let’s take it from the top. What is fraud anyway?
Well, there are lots of different types, which really doesn’t help you one bit, does it? So let’s focus just on the one at issue in Richard’s case – securities fraud.
I was hoping to have this done a week ago, but the rabbit holes I’ve had to go down almost made me give up on the topic completely and post some cat videos instead. But since I have way too much time on my hands, and the NHL is on break for the all-star game, I decided to jump back in and try and decipher some of it for you.
To grossly oversimplify things, the SEC can bring an action for securities fraud, but so can you or I. When you or I do it, it’s called a private right of action, and we become the Plaintiffs. Because government likes to make the rules, they made the rules for the SEC simpler than the rules for private plaintiffs. Essentially, the SEC gets to short-cut a few things in order to win that you or I would have to prove in court. I was able to find a matrix outlining what needs to be proven in different private securities laws claims, and I posted it below. Since I’m not being paid for any of this, I’m not reading it. I like y’all a lot, but not enough to kill off that many brain cells.
So I went back to researching case law, and after sifting through myriad cases, all of which were painfully boring, I focused on a few 2nd Circuit cases, since that’s what’s important here. And recall that the fraud claims against Richard are under 10b-5 and 17(a)(1) and (a)(3). You can google them the next time you can’t sleep.
In SEC v. First Jersey Securities, 101 F.3d 1450 (2nd Cir 1996), the Court stated that in order to establish liability under Rule 10b-5, the Plaintiff “is required to prove that in connection with the purchase or sale of a security the defendant, acting with scienter, made a material misrepresentation (or a material omission if the defendant had a duty to speak) or used a fraudulent device.” A fraudulent device here doesn’t mean a fake iPhone. It means some sort of investment device.
So what the hell is “scienter”? It means “intent to deceive, manipulate, or defraud.” This is also a quote from SEC v First Jersey. It’s a fancy way of saying someone intended to do something they knew was bad.
Now here’s where the SEC gets a break. In order to prove a claim under 17(a)(3) – one of the claims against Richard, you and I would have to prove scienter. The SEC doesn’t. Awesome, right? That’s what happens when government entities write the rules for government entities. At least the SEC still has to prove scienter for its 10b-5 and 17(a)(1) claims, so there’s that. It took the US Supreme Court to make that happen, though, in Aaron v SEC, 446 US 680 (1980).
All of that to get to the point. Richard’s attorneys claim that the SEC didn’t allege its fraud claims properly in the Complaint. And they’re right. You can’t plead fraud the same way you plead negligence or a breach of contract. Rule 9(b) is what we call a “heightened pleading standard,” which means you can’t just say “all the shit I put in the facts section above applies to this fraud claim.” Doesn’t work. But that’s what the SEC did, and that’s why Richard’s attorneys said they’ll raise this issue.
So what do you have to do to plead fraud then? I’m glad you asked. The 2nd Circuit has an answer for us. It said "securities fraud complaints [must] specify each misleading statement . . . [and] state with particularity facts giving rise to a strong inference that the defendant acted with the required state of mind."
And in order to plead scienter (state of mind) “so as to survive a motion to dismiss, a plaintiff must state with particularity facts giving rise to a strong inference that the defendant acted with the required state of mind by either alleging facts (1) showing that the defendants had both motive and opportunity to commit the fraud or (2) constituting strong circumstantial evidence of conscious misbehavior or recklessness."
You asleep yet? I just about nodded off myself.
Fine. If you don’t remember anything else, just get the principle here, which is that when you plead fraud, you must tell someone the exact reason you’re suing them, so they know what specific statement(s) they’re supposed to be defending.
Anyway, to close this out, the SEC pled claims 1 and 2 this way:
“Plaintiff re-alleges and incorporates paragraphs 1 through 76 of this Complaint by reference as if set forth verbatim in this Claim.”
I actually found a case where Plaintiffs did exactly this and got slapped down, then I lost it, couldn’t find it again, and eventually gave up looking in order to get this thing done. But basically, the court said you can’t do that in fraud claims (it’s generally ok in most other types of claims, fyi). But when pleading fraud, you have to tell someone the specific things they said that you believe were fraudulent, and why you believe the defendant knew they were fraudulent. You can’t just point to a few dozen or few hundred paragraphs and say “yeah, it’s somewhere in there, go figure it out.”
Bottom line:
1. The SEC didn’t draft its fraud claims properly.
2. This is a solid argument that I believe RH should prevail on.
3. Unfortunately, the likely remedy is that the SEC will get another swing at redrafting their Complaint.
4. If the SEC can’t cure the deficiency properly, you may see a second motion to dismiss on this issue.
5. All of the above assumes that the court has personal jurisdiction over Richard, which is an open question that will also be raised by his attorneys. Remember, no personal jurisdiction, no case.
6. All of the above also assumes that these things are securities, which is also an open question that I expect will be litigated in October (and perhaps again throughout this case if necessary).
Strictly my guess. I could be wrong. I’m wrong a lot. Nothing I say is legal advice.
But I honestly can’t wait to see what Richard’s all-star team comes up with in their motion.
#HEX #PLS #PLSX](https://pbs.twimg.com/media/GFXHq1lacAAbH3J.jpg)