

Top Tweets for #HimalayanSolar

#HimalayanSolar Ltd Created a New Low of ₹80.65 on #NSE Today
#StockToWatch
#StockInNews
#StockInFocus
#StockMarket
#Nifty #NSE #Nifty50 #Sensex


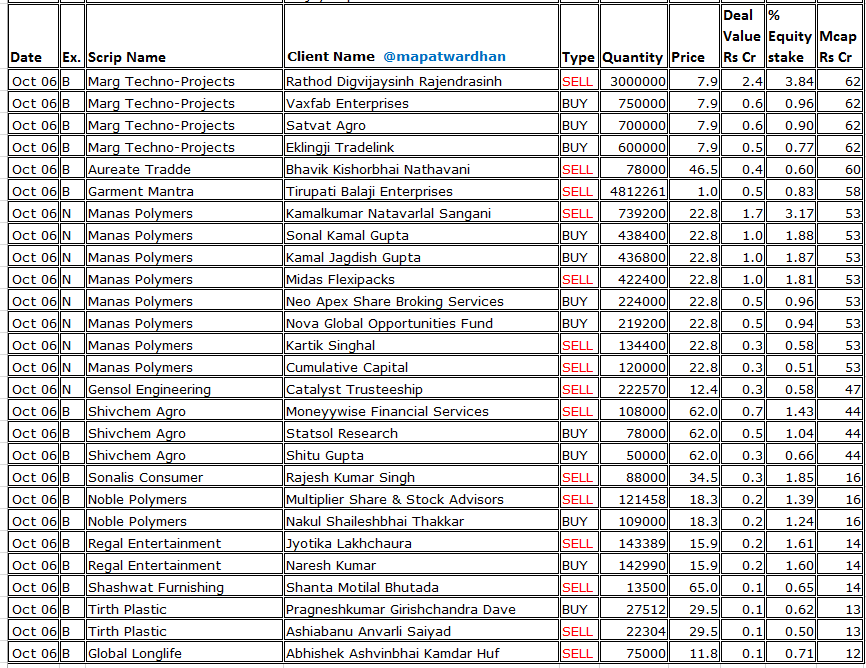
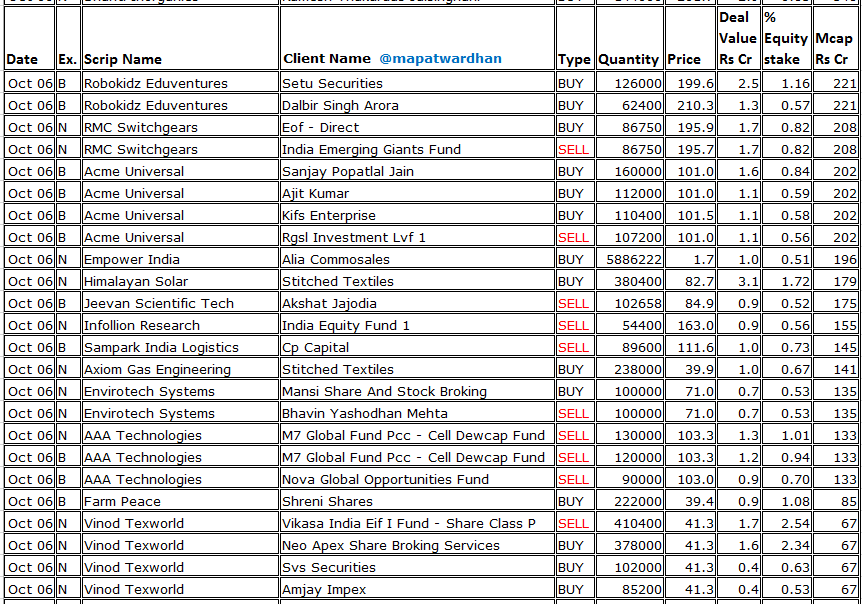
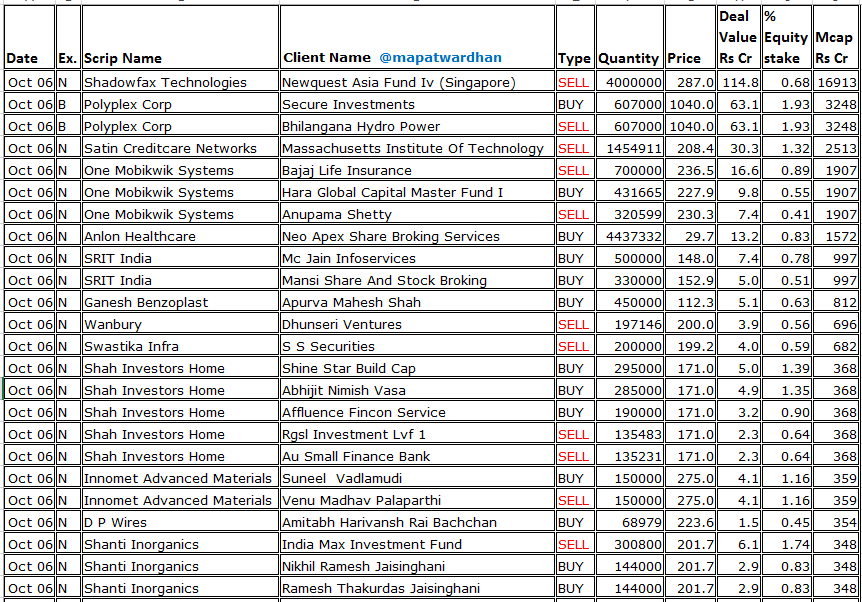
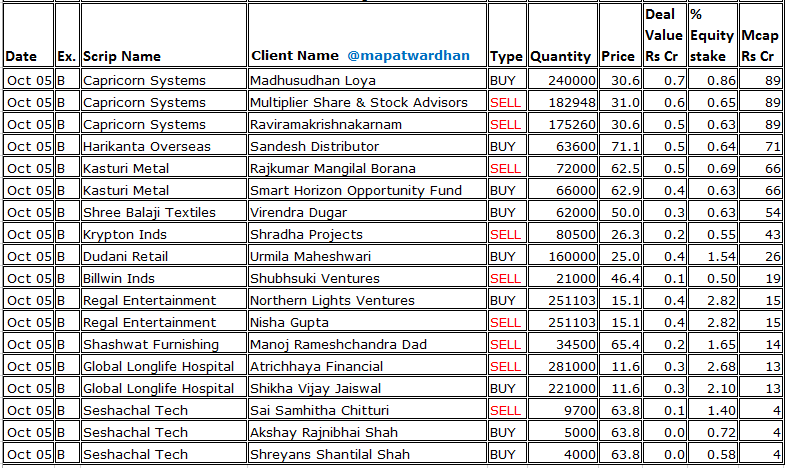
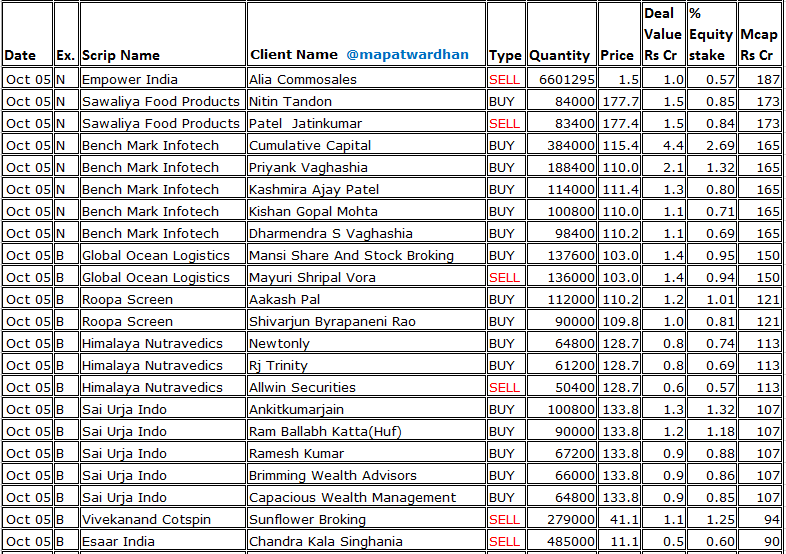
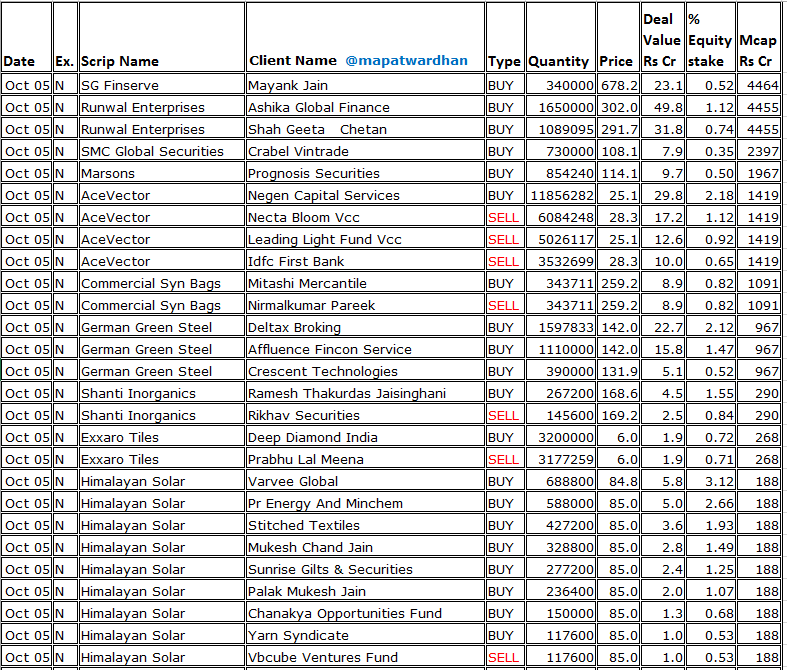
#HimalayanSolar Ltd's #NSESME IPO Listed with Discount on #NSE Today
🔶🔶🔶🔶🔶🔶🔶🔶🔶🔶🔶🔶🔶
🔽🔽🔽🔽🔽🔽🔽🔽🔽🔽🔽🔽🔽
IPO Price - ₹103.00
IPO Size - ₹68.03 Crores
IPO Lot Size -1200 Shares
Opening Price -₹85.00
Today's High -₹86.00
Today's Low -₹81.00
Closing Price -₹84.85
#NSE #SME
#IPOAlert #IPO #StockInNews #StockInFocus #StockToWatch

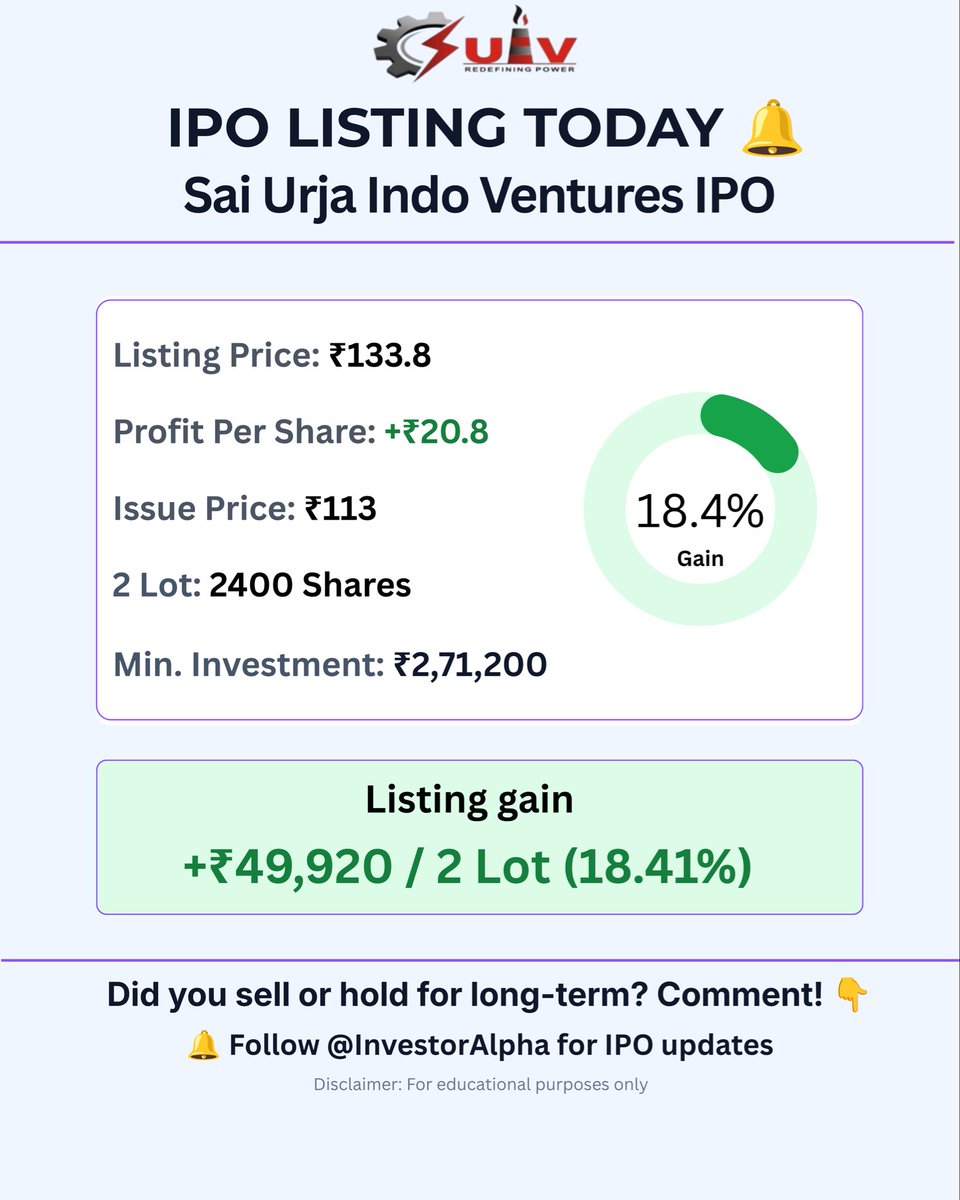
SME IPO LISTINGS TODAY 📊
• Sai Urja Indo: +18.41% Gain (+₹49,920 / 2 Lots)
• Himalayan Solar: -17.48% Loss (-₹43,200 / 2 Lots)
Profit book kiya ya hold kar rahe ho? Comment below!
#ipolisting #saiurjaindo #himalayansolar #smeipo #investoralpha

SME IPO LISTINGS TODAY 📊
• Sai Urja Indo: +18.41% Gain (+₹49,920 / 2 Lots)
• Himalayan Solar: -17.48% Loss (-₹43,200 / 2 Lots)
Profit book kiya ya hold kar rahe ho? Comment below!
#ipolisting #saiurjaindo #himalayansolar #smeipo #InvestorAlpha
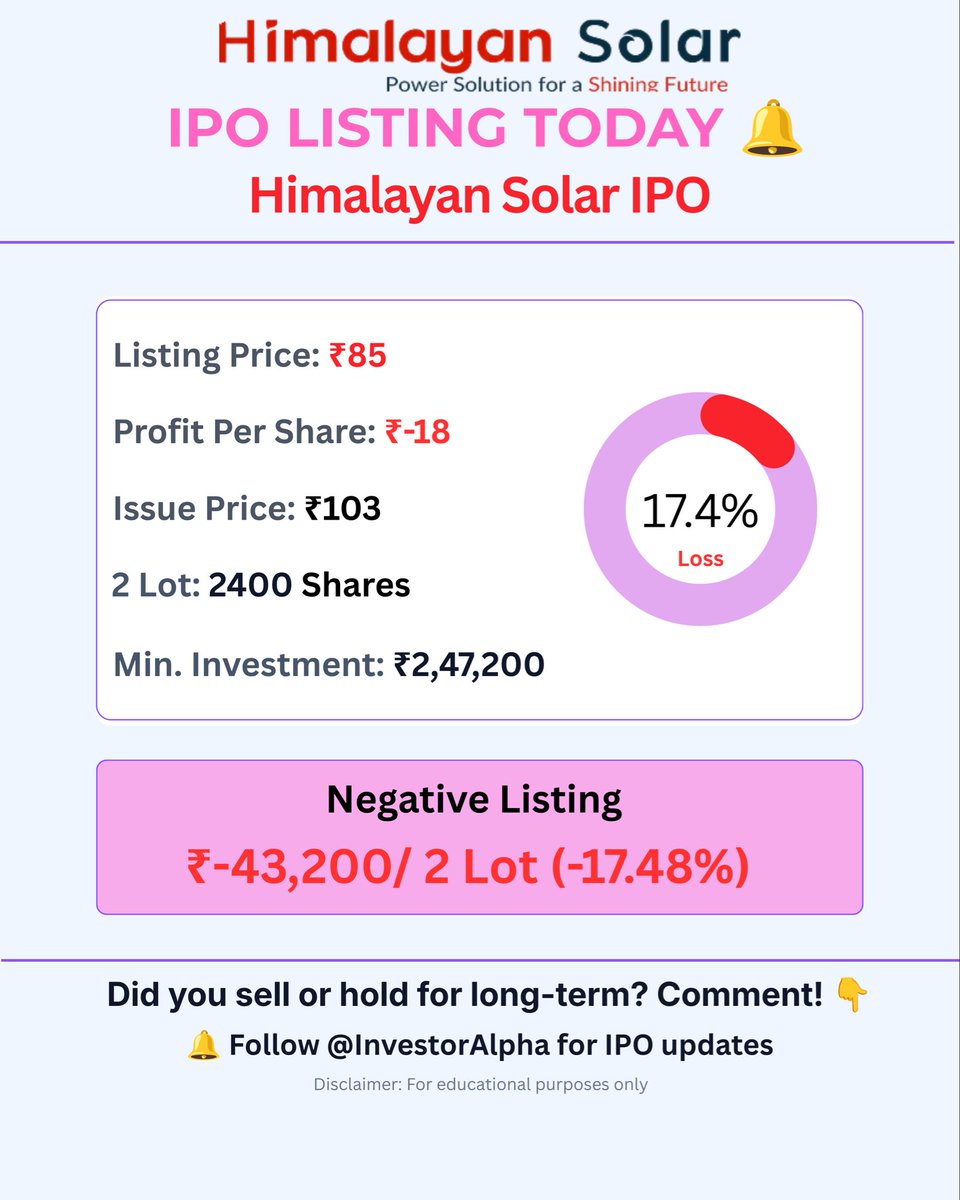

#HimalayanSolar
SME IPO Listed 👇
Listed at Rs 85 against the offer price of Rs 103 at Discount of
🔻-17.48%
#HimalayanSolar Ltd's #NSESME IPO Listing Tomorrow
🔶🔶🔶🔶🔶🔶🔶🔶🔶🔶🔶🔶🔶
🟢🟢🟢🟢🟢🟢🟢🟢🟢🟢🟢🟢🟢
IPO Price - ₹103.00
IPO Size - ₹68.03 Crores
IPO Lot Size -1200 Shares
Subscribed -1.19X
Date of Listing -5th October
#NSE #SME
#IPOAlert #IPO #StockInNews #StockInFocus #StockToWatch

🚨 Himalayan Solar IPO
Allotment is now OUT
Check here 🔽
https://t.co/CdgFGRFBvK
#himalayansolar #solar #ipo #allotment #sme #stocks #market #nse #india #shares #shreekaram
🚨 Government-Focused Solar Water Pumping + EPC Player With 85,000+ HP Execution Experience going public with SME IPO
Himalayan Solar Limited
♾ IPO
🔹 NSE Emerge SME IPO
🔹 100% book-built issue
🔹 Price band: ₹98 – ₹103
🔹 Face value: ₹10/share
🔹 Total shares: 66,04,800
🔹 Anchor: Sep 24
🔹 Bidding: Sep 25 - 29
🔹 Allotment: Sep 30
🔹 Listing: Oct 5
🔹 BRLM: Finshore Management Services
🔹 Registrar: Maashitla Securities
🔹 Market maker: Anant Securities
♾ Company
🔹 Incorporated in 2015, Haryana-based integrated solar-energy solutions company
🔹 Core business:
• Design
• Manufacturing
• Supply
• Installation
• Commissioning
🔹 Primary focus: Solar Water Pumping Systems
Also operates across:
• Solar PV modules
• Solar rooftop systems
• Solar inverter charger systems
• Other turnkey solar solutions
🔹 Has implemented more than 85,000 HP capacity of Solar Water Pumping Systems under government projects across India
🔹 Empanelled for government solar programmes including PM-KUSUM-related projects
🔹 FY26 govt-sector rev: ₹165.56 cr
🔹 Govt contribution: 97.19% of FY26 rev
🔸 Business is dependent on govt-backed solar projects rather than private-sector demand
♾ Manufacturing transition
Himalayan Solar previously operated:
🔹 40 MW Polycrystalline Solar PV module facility in Panchkula
Historical utilisation:
🔹 FY23: 18.54%
🔹 FY24: 22.98%
🔹 Production at old facility was stopped from Aug 2024 after government tender requirements shifted towards higher-efficiency monocrystalline modules
Company then established:
🔹 60 MW Mono-PERC 16BB module line in Karnal
🔹 Approx annual capacity:
• ~1,07,500 Mono-PERC modules
🔹 Commercial operations started: Mar 2026
🔸 New 60 MW line has only recently begun operations, so there is not yet a meaningful full-year utilisation history for this facility
♾ Capacity expansion
🔹 Existing new capacity: 60 MW
🔹 Additional planned: 100 MW
🔹 Planned total: 160 MW
🔹 Capacity increase: ~167% over current 60 MW line
New equipment to support:
• Mono-PERC
• TOPCon Bifacial modules
• Glass-to-Glass technology
• Up to 20 Busbar modules
• Expandable towards 25 Busbar
• Automatic bussing
• Automatic glass loading
• Automatic framing
Implementation target:
🔹 Machinery order: Oct 2026
🔹 Delivery: Jan 2027
🔹 Installation: Feb 2027
🔹 Trial run: Mar 2027
🔹 Commercial operations: Apr 2027
⚠️ Company had not placed firm machinery orders at latest disclosed stage
🔸 Pricing, delivery, installation and commissioning therefore still carry execution risk
♾ Order book
As of Jul 31, 2026:
🔹 Unexecuted order book: ₹140.22 cr
🔹 FY26 rev from operations: ₹170.34 cr
🔹 Order book / FY26 rev: ~0.82x
🔹 Order book comprises mainly government projects
🔸 Provides near-term revenue visibility but is not exceptionally large relative to current annual revenue
🔸 Govt orders could face implementation delays, scope changes, payment delays or cancellation
♾ Customer concentration
Top customer contribution:
🔹 FY24: 88.48%
🔹 FY25: 85.15%
🔹 FY26: 50.00%
🔹 Largest cust has historically been HAREDA / Haryana renewable-energy authorities
🔹 Dependence on largest cust has reduced sharply
But FY26:
🔹 Top 1: 50.00%
🔹 Top 5: 99.54%
🔹 Top 10: 100%
🔸 Almost entire FY26 rev came from only a handful of customers
🔸 Losing, delaying or receiving fewer orders from even one large government customer can materially affect revenue + cash flow
♾ Geography
FY26 revenue:
🔹 Haryana: ₹89.96 cr / 52.81%
🔹 Maharashtra: ₹77.54 cr / 45.52%
🔸 Punjab: ₹2.84 cr / 1.67%
For comparison, Haryana contributed:
🔹 FY24: 88.93%
🔹 FY25: 86.15%
🔹 FY26: 52.81%
♾ Supplier concentration
FY26 purchases:
🔹 Largest: 29.02%
🔹 Top 5: 90.20%
🔹 Top 10: 98.00%
For comparison Top supplier:
🔹 FY24: 56.00%
🔹 FY25: 36.91%
🔹 FY26: 29.02%
♾ IPO money
Fresh issue at upper band: ~₹60.68 cr
🔹 ₹29.50 Cr - Incremental working capital requirements
🔹 ₹12.98 Cr - Expansion + upgradation of manufacturing facility
🔹 ₹2.12 Cr - Repayment of machinery loan
🔹 Balance - GCP + applicable issue requirements
🔹 Manufacturing capex ~21.4%
♾ Working-capital requirement
Gap:
🔹 FY24: ₹24.97 cr
🔹 FY25: ₹39.42 cr
🔹 FY26: ₹65.11 cr
Estimated:
🔹 FY27: ₹102.08 cr
🔹 FY28: ₹140.06 cr
🔸 Working-capital gap projected to more than double bw FY26 and FY28
🔸 Even after IPO funding, business will continue requiring substantial internal accruals + external financing
♾ Receivables
Trade receivables:
🔹 FY24: ₹40.45 cr
🔹 FY25: ₹66.32 cr
🔹 FY26: ₹125.34 cr
🔹 FY26 receivables up ~89% YoY
🔹 Receivables equal ~73.6% of FY26 annual rev
🔸 Rev grew ~20% in FY26 while receivables increased almost 89%
🔸 This divergence important numbers in this IPO
🔸 Govt-project payment milestones can create long collection cycles and significant cash tied up outside business
♾ Financials
Revenue from operations:
🔹 FY24: ₹138.32 cr
🔹 FY25: ₹142.44 cr
🔹 FY26: ₹170.34 cr
EBITDA:
🔹 FY24: ₹7.83 cr
🔹 FY25: ₹23.58 cr
🔹 FY26: ₹29.04 cr
PAT:
🔹 FY24: ₹4.95 cr
🔹 FY25: ₹16.43 cr
🔹 FY26: ₹20.67 cr
Net worth:
🔹 FY24: ₹10.33 cr
🔹 FY25: ₹26.46 cr
🔹 FY26: ₹46.93 cr
Total borrowings:
🔹 FY24: ₹23.54 cr
🔹 FY25: ₹26.95 cr
🔹 FY26: ₹36.12 cr
🔹 FY26 revenue growth: ~19.6%
🔹 FY26 PAT growth: ~25.8%
🔹 FY24-FY26 revenue CAGR: ~11%
♾ Margins increase
EBITDA margin:
🔹 FY24: 5.66%
🔹 FY25: 16.55%
🔹 FY26: 17.05%
PAT margin:
🔹 FY24: 3.58%
🔹 FY25: 11.54%
🔹 FY26: 12.13%
🔹 Major margin improvement occurred in FY25.
Drivers:
• Shift away from older low-margin EESL orders
• Higher-margin SECI + state govt PM-KUSUM projects
• Better project pricing
• Improved procurement terms
• Lower input costs
🛠️ Sustainability of ~17% EBITDA margin as business expands into new orders is more important than historical PAT growth percentage
♾ Returns
FY26:
🔹 RoNW: 44.04%
🔹 ROCE: 35.84%
FY25:
🔹 RoNW: 62.11%
🔹 ROCE: 44.32%
♾ Cash flow
Operating cash flow:
🔹 FY24: -₹5.52 cr
🔹 FY25: +₹3.90 cr
🔹 FY26: -₹2.07 cr
PAT:
🔹 FY24: ₹4.95 cr
🔹 FY25: ₹16.43 cr
🔹 FY26: ₹20.67 cr
⚠️ FY26 ₹20.67 cr profit but operating cash flow was negative ₹2.07 cr
🛠️ Collection of ₹125+ cr receivables is post-listing metrics to track
♾ Debt
Total borrowings:
🔹 FY24: ₹23.54 cr
🔹 FY25: ₹26.95 cr
🔹 FY26: ₹36.12 cr
Debt/equity:
🔹 FY24: 2.28x
🔹 FY25: 1.02x
🔹 FY26: 0.77x
🔹 Debt/equity improved significantly
🔹 Company also availed additional working-capital term loans after Mar 2026
🔸 FY26 year-end borrowings should therefore not be treated as maximum/latest debt exposure
♾ Contingent liabilities
As of Mar 31, 2026:
🔹 Bank guarantees: ₹29.18 cr ~62% of FY26 net worth
🔸 Bank guarantees are common in govt-project businesses but highlight scale of contractual commitments relative to company's balance sheet
♾ Promoters
🔹 Manjeet Singh
🔹 Karthyayini M
🔹 Himanshu Dalal
🔹 Mehtab Singh
🔹 Anita Kumari
Pre-IPO promoter holding ~100%
Post-IPO ~70.13%
🔸 Only one Promoter Karthyayini M is selling through OFS
♾ Valuation
Price band:₹98–₹103
FY26 EPS: ₹12.74
FY26 EPS P/E at ₹103: ~8.08x
Simple FY26 dilution-adjusted EPS at unchanged PAT ~₹9.35
Post-issue P/E at ₹103: ~11.02x
Post-issue mcap at ₹103: ~₹227.7 cr
Price/sales on FY26 rev ~1.34x
♾ Peer context
🔹 Ganesh Green Bharat P/E: ~7.11x
🔹 Solarium Green P/E: ~14.99x
🔹 Australian Premium P/E: ~8.34x
Peer average: ~11.05x
🔸 Himalayan Solar's post-issue dilution-adj P/E of ~11.02x sits close to peer average
🔸 Historical EPS-based P/E of ~8.08x does not reflect dilution from newly issued shares
♾ Governance + compliance
🔹 Disclosed historical delays in multiple corporate/statutory filings
🔹 Also instances where private-placement money was not kept in required separate bank account
🔹 Related adjudication proceedings were still pending
♾ Strengths
🔹 ₹140.22 cr order book
🔹 FY26 revenue: ₹170.34 cr
🔹 FY26 PAT: ₹20.67 cr
🔹 ROCE: 35.84%
🔹 RoNW: 44.04%
🔹 More than 85,000 HP solar-water-pumping implementation experience
🔹 EBITDA margin expanded from 5.66% in FY24 to 17.05% in FY26
🔹 PAT margin expanded from 3.58% to 12.13%
🔹 Cust dependence reduced from 88.48% in FY24 to 50% in FY26
🔹 Haryana rev concentration reduced materially as Maharashtra business expanded
🔹 Debt/equity improved from 2.28x to 0.77x
🔹 Fresh IPO capital supports working capital + transition towards higher-efficiency Mono-PERC/TOPCon manufacturing
♾ Watch-outs
🔹 Top cust: 50% of FY26 rev
🔸 Single-cust dependency remains very high
🔹 Top 5 cust: 99.54%
🔸 Almost entire rev depends on handful of cust
🔹 Govt projects: 97.19% of FY26 rev
🔸 Policy, tender, budget + payment-cycle dependence is extremely high
🔹 Haryana + Maharashtra: ~98.3% of FY26 revenue
🔸 Geographic diversification remains limited
🔹 Top 5 suppliers: 90.20%
🔸 Procurement concentration remains high
🔹 Trade receivables: ₹125.34 cr
🔸 Equal to ~74% of annual rev
🔹 FY26 OCF: -₹2.07 cr despite ₹20.67 cr PAT
🔸 Cash conversion is major weakness
🔹 Working-capital gap projected to rise to ~₹140 cr by FY28
🔸 Business may continue requiring substantial external funding
🔹 Borrowings increased to ₹36.12 cr
🔸 Absolute debt increased even though debt/equity improved
🔹 Old 40 MW plant had low historical utilisation
🔸 New 60 MW line has only just begun operations
🔹 Plans expansion from 60 MW to 160 MW
🔸 Demand + utilisation must scale significantly to justify new fixed capacity
🔹 Firm machinery orders for 100 MW expansion were still pending
🔸 Capex execution + commissioning timeline remain open risks
🔹 Bank guarantees: ₹29.18 cr
🔸 Significant relative to current net worth
♾ Final
🔹 Himalayan Solar combines govt-focused solar EPC execution with an emerging solar module manufacturing business and has already built ₹170+ cr annual rev + ₹140 cr order book
🔹 Financial profitability improved sharply, with EBITDA margin rising from 5.66% to 17.05% in two years and FY26 PAT reaching ₹20.67 cr
🔸 Cash flow: FY26 operating cash flow was negative while trade receivables jumped to ₹125.34 cr, making collections + working capital key numbers to watch
🔸 Cust concentration is high with top 5 contributing 99.54% and govt projects contributing 97.19% of rev
🔸 Manufacturing expansion from 60 MW to 160 MW can change business scale, but new 60 MW line itself has limited operating history and additional 100 MW machinery is yet to be ordered
🔹 At ₹103, post-issue mcap is ~₹228 cr and dilution-adj FY26 P/E is ~11x
🛠️ Key things to watch next are anchor participation, QIB demand, receivable collections, operating cash flow, working-capital borrowing, utilisation of new plant, 100 MW expansion execution, govt-order diversification
⚠️ This is not a buy/sell recommendation. IPO GMP is unofficial and changes quickly. SME IPOs can be illiquid and volatile. Always read the RHP/DRHP, check valuation, risks and your own financial situation before applying
#himalayansolar #himalayansolaripo #solarenergy #solarpumps #solarmanufacturing #renewableenergy #pmkusum #smeipo #ipo #nse #bse #sebi #ipoalert #nifty50 #sensex #niftybank #niftyit #Nifty500 #niftysmallcap #shreekaram

#HimalayanSolar Ltd #NSESME IPO subscribed 0.51 Times
🔶🔶🔶🔶🔶🔶🔶🔶🔶🔶🔶🔶🔶
🟢🟢🟢🟢🟢🟢🟢🟢🟢🟢🟢🟢🟢
IPO Price - ₹68.03
IPO Size - ₹303.90 Crores
IPO Lot Size -1200 Shares
Date of Closing -29th September
Date of Allotment -30th September
Date of Listing - 5th October
#NSE #SME
#IPOAlert #IPO #StockInNews #StockInFocus #StockToWatch
Trends for you
Most Popular Users

Elon Musk 
@elonmusk
241.7M followers

Barack Obama
@barackobama
118.9M followers

Cristiano Ronaldo
@cristiano
114.6M followers

Donald J. Trump
@realdonaldtrump
111.9M followers

Narendra Modi
@narendramodi
107.2M followers

Rihanna
@rihanna
98.7M followers

NASA
@nasa
92.4M followers

Justin Bieber
@justinbieber
91.8M followers

KATY PERRY
@katyperry
90.1M followers

Taylor Swift
@taylorswift13
84M followers

Lady Gaga
@ladygaga
75.5M followers

Virat Kohli
@imvkohli
73.5M followers

Kim Kardashian
@kimkardashian
70.9M followers

YouTube
@youtube
68.8M followers

Neymar Jr
@neymarjr
66.5M followers

Bill Gates
@billgates
65.2M followers

Selena Gomez
@selenagomez
63.1M followers

The Ellen Show
@theellenshow
62.3M followers

CNN
@cnn
61.8M followers

X
@x
60.7M followers