

Top Tweets for #IndoMim

સેમી કંડક્ટર સેક્ટરઃ આ બે શેર અવગણવા જેવા નથી
#SemiconductorSector #SemiconductorStocks #IndiaSemiconductorMission #SemiconductorIndustry #RatnaveerPrecisionEngineering #INDOMIM
https://t.co/bLytFbyFVI


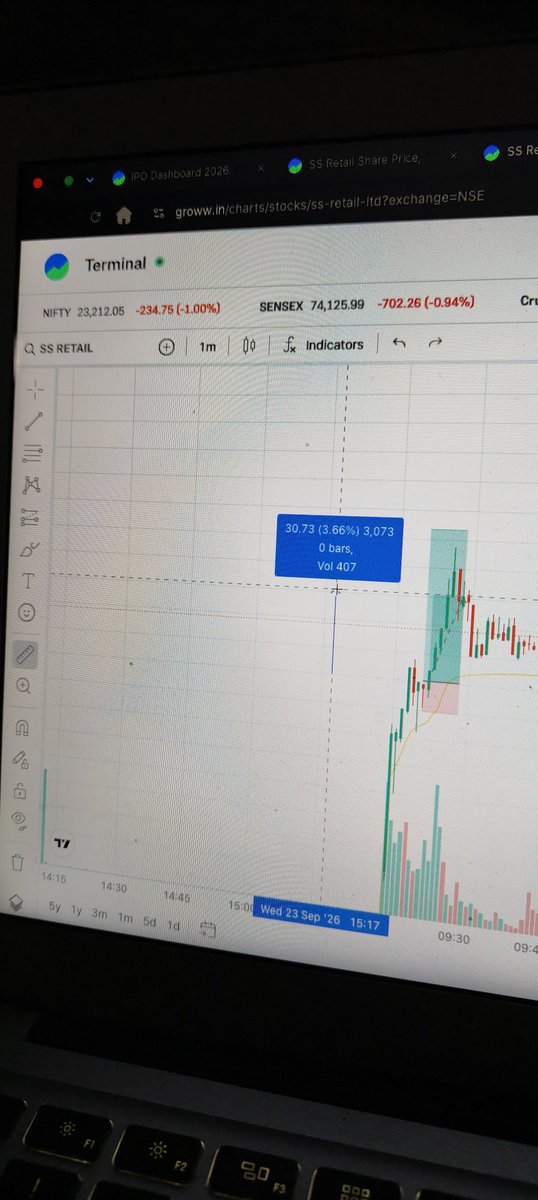
Recentmost IPOs which closed in🟢today have inherent strength. Keep a tab (only if Index seems sideways or moving upwards)
#Steamhouse
#Indomim
#Skyways
#Lalithaa
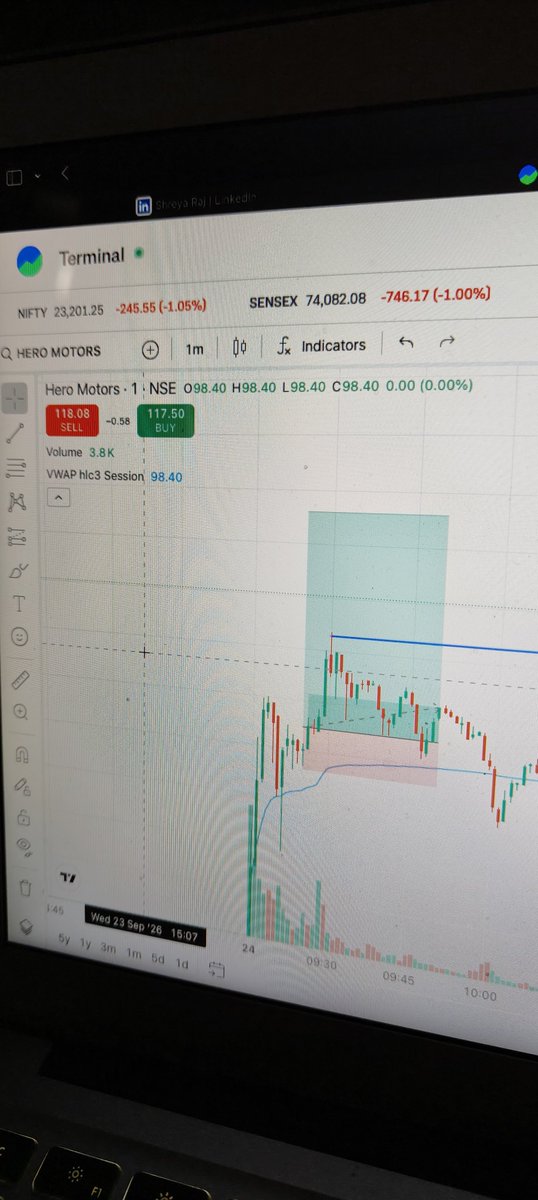
& Obviously Superperformers:
#Heromotors 20% UC 🔥
#Priority 15% Up 🚀

#IndoMIM #CUMI
Manufacturing is ultimately a pricing-power game.
Capacity has to turn into volume.
Revenue = Volume × Price.
Indo-MIM clearly has operating leverage.
Core MIM utilisation is still low, so higher volumes can lift margins meaningfully?
One nuance matters:
Not all capacity should be treated equally.
A good part of Indo-MIM's upstream capacity, especially metal powders, is meant to be consumed internally.
So upstream capacity may improve:
- raw-material security
- cost control
- margins
- product capability
…but it does not automatically translate into equivalent external revenue.
That is also why I don't expect OP/NP to converge anywhere close to 1.5x.
Some economics will continue sitting upstream before being captured downstream.
At the same time, the moat cannot simply be vertical integration.
Players like CUMI can move downstream too.
MIM remains globally fragmented, technologies are converging, and customers still have bargaining power.
So I am watching three things closely:
1. Actual downstream volumes + utilisation
2. How much upstream capacity is captive vs externally sold
3. Pricing power after accounting for competition and customer pressure
In short:
Indo-MIM is not a niche player to me.
It is a very good vertically integrated manufacturer.
The opportunity is operating leverage.
The question is whether that leverage ultimately converts into durable pricing power.
https://t.co/TfWjPlXpcj
#IndoMIM
Quick take on the results: My previous thesis holds
Revenue from operations grew 9.4% YoY. That higher-single-digit growth remains the disappointing part for me and the main reason I am still in wait-and-watch mode for fresh positions(maybe Jan or March I think)
QoQ revenue growth, however, was much healthier at 16.3%. (have to check this: seasonal?)
1⃣One important thing not to miss here is inventory.
- Indo-MIM is an inventory-heavy manufacturing business by design.
- The company says it stocks most raw materials for at least three months.
At the same time, Indo-MIM is increasingly backward integrated.
It already manufactures stainless-steel powder in-house and is working towards manufacturing iron powder as well.
Over time, this should give the company greater control over:
Raw material availability → cost → quality → lead times → margins.
2⃣But this quarter needs another layer of reading.
Reported PAT grew 31.6% YoY, from ₹182.4 cr to ₹240.1 cr.
Sounds exciting?🆘
But look at the inventory line.
Change in finished goods and WIP moved from:
+₹12.9 cr expense → -₹40.0 cr expense
That's a ₹52.9 cr favorable swing at PBT level.
After tax, roughly ₹39 cr.
₹240.1 cr reported PAT - ₹39.0 cr inventory-related benefit = ~₹201.1 cr normalized PAT
That translates to only around 10.2% YoY normalized PAT growth, much closer to the 9.4% revenue growth.
At a market cap of ₹42,831.99 cr:
- Reported TTM PAT: ~₹591 cr
→ ~72.4x P/E
- Inventory-normalized TTM PAT: ~₹552 cr
→ ~77.6x P/E
3⃣So, Don't get excited. But don't get fearful yet either.
Inventory is part of the operating model, not automatically bad accounting.
What I want to see now is whether backward integration can convert into sustainable margin improvement while topline growth accelerates.
🍀Until then: Thesis holds. Fresh buying can wait.
4⃣And if someone wants to book profits, they may work on their own sell-side thesis.
- As of now no PPT released and no concall scheduled.
Let's see what institutes will say...


#INDOMIM like hame fadak nahi padta
Again UC
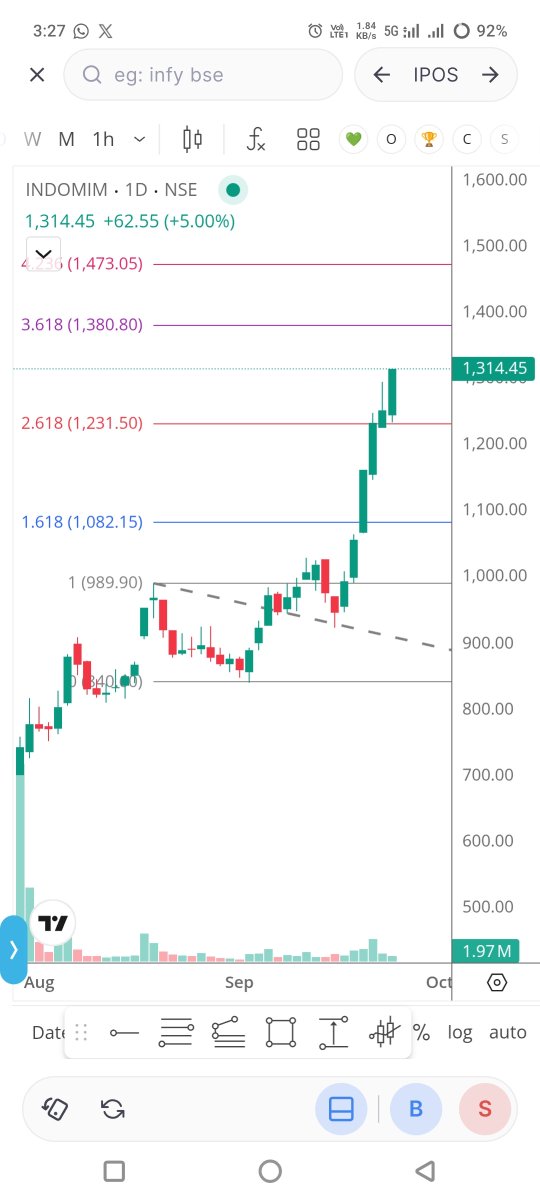

#KABRAEXTRU #RAYMOND #STLNETWORK #INDOMIM - Look at the strength. Covered the fundamentals of all of them.

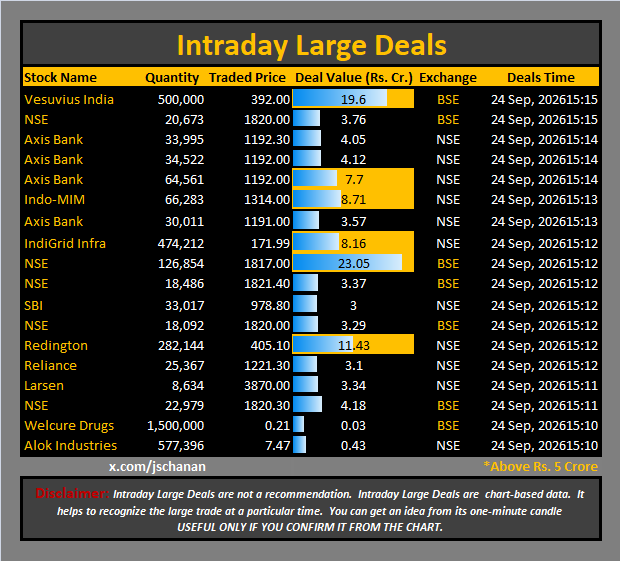

#indomim swing trade tp🎯
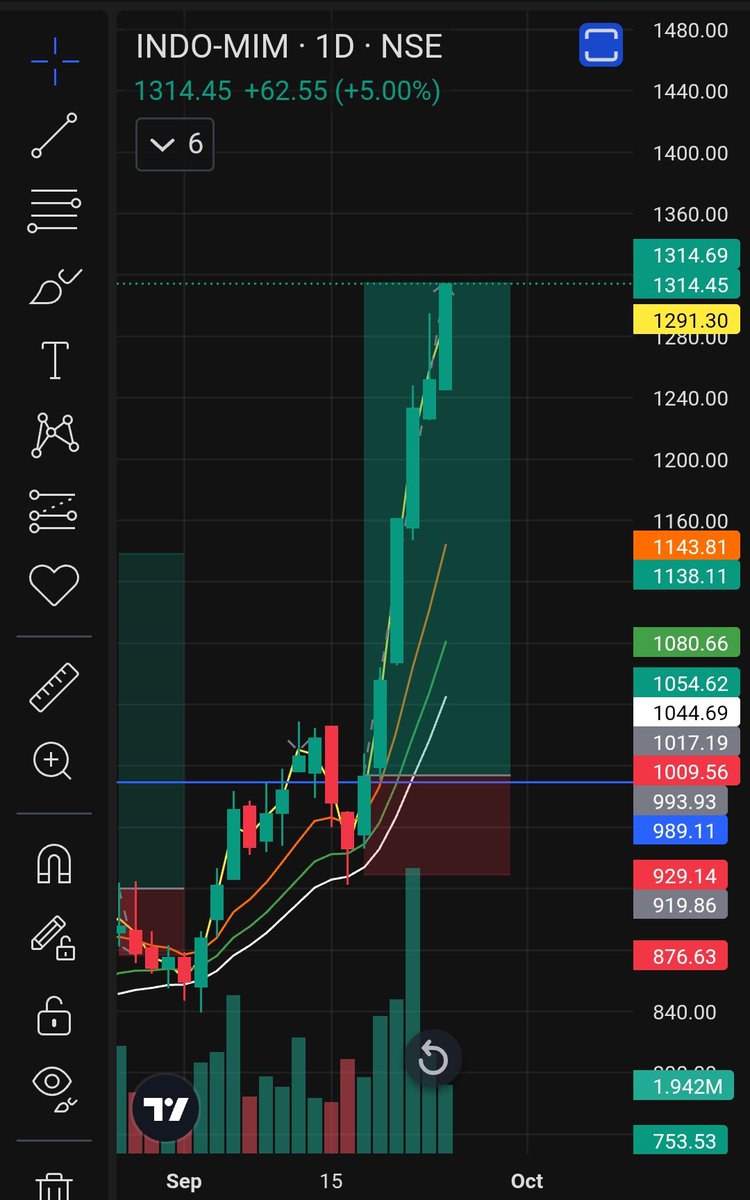

INDO MIM now 75% 🔥 💥
#INDOMIM
🚨 ANOTHER STORY OF NASCENT CONVICTION, BUT THIS TIME ITS LOADING 🚨 (2:22PM)
I studied a company recently, and as per my philosophy, I gave this company a chance.
Ki tum aasman ki unchaiyon tak jao, 🚀
And here it is - in UC today.
𝗜’𝗺 𝘁𝗮𝗹𝗸𝗶𝗻𝗴 𝗮𝗯𝗼𝘂𝘁 𝗜𝗡𝗗𝗢-𝗠𝗜𝗠.
𝗦𝘁𝘂𝗱𝗶𝗲𝗱 𝘁𝗵𝗶𝘀 @700 𝗹𝗲𝘃𝗲𝗹 𝗻𝗼𝘄 1100+ 🔥
But story is not this.
Here i am sharing a initial note (NOT deep dive)
INDO-MIM IS NOT JUST A “MIM COMPANY”.
I spent serious time going through the Mngmt Disclosure.
And deeper I went,
more interesting the business became. 👀
At first glance:
Metal Injection Moulding.
But that is only the SURFACE.
Underneath it,
there is a much bigger manufacturing story.
INDO-MIM today has:
650+ global customers
85+ material options
10,000+ parts
45+ countries
2,500+ engineers, technicians & associates
1M+ sq ft manufacturing footprint
And this is the part most people may miss:
INDO-MIM is NOT dependent on just one manufacturing technology.
MIM
Investment Casting
Precision Machining
3D Printing
Tooling
Materials
Finishing
Assembly
They are trying to become a ONE-STOP precision engineering partner.
Think about it.
A customer doesn't always want:
Vendor A for tooling.
Vendor B for manufacturing.
Vendor C for finishing.
Vendor D for assembly.
They want:
“Give us the component.”
AND THAT'S WHERE REAL STORY STARTS.
Because moat isn't simply owning a machine.
Moat can sit inside:
Material formulation
Tool design
Process know-how
Debinding
Sintering
Dimensional control
Quality
Customer qualification
Production consistency
Scale
A competitor can buy equipment.
Replicating the ENTIRE process ecosystem is much harder.
That's why I don't see INDO-MIM simply as:
“A company making metal parts.”
I see a company trying to move from:
COMPONENT MFG
↓
PRECISION ENGINEERING PARTNER
↓
MULTI-TECHNOLOGY MFG PLATFORM
NOW LOOK AT NUMBERS.
FY26 standalone revenue:
₹3,658 Cr
vs ₹2,834 Cr
~29% growth.
PBT:
₹737 Cr
vs ₹545 Cr
~35% growth.
PAT:
₹549 Cr
vs ₹404 Cr
~36% growth.
And PAT margin improved from:
14.24%
to
15.00%.
So this wasn't merely:
“Revenue grew.”
Profitability improved too.
BUT,
HERE COMES THE INTERESTING PART.
Don't look at INDO-MIM only through consolidated PAT.
Because the company has been building a GLOBAL ecosystem.
INDO-MIM INC — USA
TRIAX — USA
CONWAY MARSH GARRETT — UK
PHOENIX DEVENTURES — USA
INDO-MIM ARMS COMPONENTS — INDIA
+ Mexico associate
And this creates BOTH:
OPTIONALITY
AND
RISK.
Let's look at the subsidiaries.
INDO-MIM INC:
$42.36M revenue
$4.25M PBT
Good.
But,
TRIAX:
$25.88M revenue
-$2.36M PBT
CONWAY MARSH GARRETT:
£3.01M revenue
-£1.03M PBT
PHOENIX:
$6.70M revenue
-$2.90M PBT
Arms Components:
No revenue yet.
THIS IS IMPORTANT.
Indian core is currently doing heavy lifting.
Overseas acquisitions haven't yet demonstrated the same level of profitability across board.
So next chapter isn't simply:
“Will INDO-MIM grow?”
The bigger question is:
CAN INDO-MIM TURN ITS GLOBAL CAPABILITIES INTO GLOBAL PROFITS?
NOW,
PHOENIX IS PARTICULARLY INTERESTING.
Acquired in May 2025.
Medical device prototype manufacturing + design.
Think:
DESIGN
↓
PROTOTYPE
↓
MANUFACTURING
That's a subtle but important evolution.
Because the company can potentially move closer to the customer's product-development cycle.
But,
Phoenix was loss-making in FY26.
So I'm treating this as:
OPTIONALITY.
NOT CURRENT EARNINGS.
AND THEN THERE IS AEROSPACE.
FY26 Aerospace rev:
~₹502 Cr
~12% of total revenue.
INDO-MIM also has AS 9100 certification.
Aerospace is interesting because precision + qualification + reliability can create higher barriers to entry.
But again,
A GOOD INDUSTRY ≠ AUTOMATICALLY GOOD RETURNS.
Execution matters.
NOW LOOK AT BALANCE SHEET.
DISCLAIMER = THIS IS NOT A BUY OR SELL RECOMMENDATION. SHARING ONLY FOR STUDY PURPOSES.
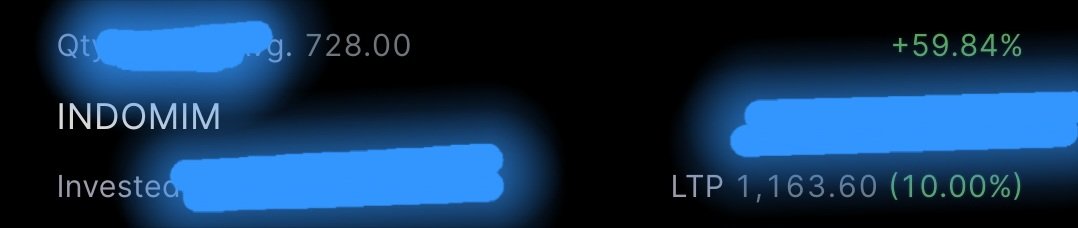



#STUDY #THINKING #INDOMIM
INDO-MIM
Studied @700 level now 1200+ 🔥
INDO-MIM: THE INTERESTING QUESTION ISN’T “WHO ARE THE COMPETITORS?” 👀
It’s:
WHY DOES A CUSTOMER STICK WITH INDO-MIM
WHEN THERE ARE SO MANY MIM PLAYERS GLOBALLY?
Because let’s be clear,
THIS IS NOT A MONOPOLY.
The MIM industry has serious global competition.
But competition ≠ commoditisation.
In a business like MIM, the real moat can sit somewhere else.
Think about the journey:
Metal powder
↓
Feedstock
↓
Tooling
↓
MIM
↓
Machining
↓
Finishing
↓
Quality
↓
Qualification
↓
Mass production
Now imagine one of these components becomes part of a critical customer product.
Can the customer simply say:
“Someone else is 5% cheaper.
Let’s switch.”
Not that easily.
The new supplier has to prove:
→ Can you manufacture the exact geometry?
→ Can you maintain tight specifications?
→ Can you pass qualification?
→ Can you maintain consistency?
→ Can you scale production?
→ Can you meet delivery requirements?
→ Can you maintain quality for years?
THAT is where switching costs can emerge.
So the pricing power question becomes much more interesting.
Not:
“Does Indo-MIM have competitors?”
Of course it does.
But:
“HOW HARD IS IT TO REPLACE IN A CUSTOMER’S SUPPLY CHAIN?”
And this is where Indo-MIM’s vertical integration becomes important to study.
From metal powders & feedstock
to tooling
to MIM manufacturing
to machining…
More of the process sits under one roof.
The numbers also show superior margins versus several competitors.
Now the job is to understand WHY.
Is it:
→ Process capability?
→ Scale?
→ Product mix?
→ Vertical integration?
→ Customer qualification?
→ Higher-value applications?
→ Manufacturing efficiency?
That answer matters far more than simply calling it a “moat”.
Because a moat is not a label.
A moat is something you can see in:
CUSTOMER STICKINESS
+
MARGINS
+
REPEAT ORDERS
+
QUALITY
+
EXECUTION.
That’s the Indo-MIM question I’m studying.
Not “Is it a monopoly?”
But:
CAN IT REMAIN DIFFICULT TO REPLACE?
Disclaimer: This post is purely for informational purposes and is NOT a recommendation.
🚨 ANOTHER STORY OF NASCENT CONVICTION, BUT THIS TIME ITS LOADING 🚨 (2:22PM)
I studied a company recently, and as per my philosophy, I gave this company a chance.
Ki tum aasman ki unchaiyon tak jao, 🚀
And here it is - in UC today.
𝗜’𝗺 𝘁𝗮𝗹𝗸𝗶𝗻𝗴 𝗮𝗯𝗼𝘂𝘁 𝗜𝗡𝗗𝗢-𝗠𝗜𝗠.
𝗦𝘁𝘂𝗱𝗶𝗲𝗱 𝘁𝗵𝗶𝘀 @700 𝗹𝗲𝘃𝗲𝗹 𝗻𝗼𝘄 1100+ 🔥
But story is not this.
Here i am sharing a initial note (NOT deep dive)
INDO-MIM IS NOT JUST A “MIM COMPANY”.
I spent serious time going through the Mngmt Disclosure.
And deeper I went,
more interesting the business became. 👀
At first glance:
Metal Injection Moulding.
But that is only the SURFACE.
Underneath it,
there is a much bigger manufacturing story.
INDO-MIM today has:
650+ global customers
85+ material options
10,000+ parts
45+ countries
2,500+ engineers, technicians & associates
1M+ sq ft manufacturing footprint
And this is the part most people may miss:
INDO-MIM is NOT dependent on just one manufacturing technology.
MIM
Investment Casting
Precision Machining
3D Printing
Tooling
Materials
Finishing
Assembly
They are trying to become a ONE-STOP precision engineering partner.
Think about it.
A customer doesn't always want:
Vendor A for tooling.
Vendor B for manufacturing.
Vendor C for finishing.
Vendor D for assembly.
They want:
“Give us the component.”
AND THAT'S WHERE REAL STORY STARTS.
Because moat isn't simply owning a machine.
Moat can sit inside:
Material formulation
Tool design
Process know-how
Debinding
Sintering
Dimensional control
Quality
Customer qualification
Production consistency
Scale
A competitor can buy equipment.
Replicating the ENTIRE process ecosystem is much harder.
That's why I don't see INDO-MIM simply as:
“A company making metal parts.”
I see a company trying to move from:
COMPONENT MFG
↓
PRECISION ENGINEERING PARTNER
↓
MULTI-TECHNOLOGY MFG PLATFORM
NOW LOOK AT NUMBERS.
FY26 standalone revenue:
₹3,658 Cr
vs ₹2,834 Cr
~29% growth.
PBT:
₹737 Cr
vs ₹545 Cr
~35% growth.
PAT:
₹549 Cr
vs ₹404 Cr
~36% growth.
And PAT margin improved from:
14.24%
to
15.00%.
So this wasn't merely:
“Revenue grew.”
Profitability improved too.
BUT,
HERE COMES THE INTERESTING PART.
Don't look at INDO-MIM only through consolidated PAT.
Because the company has been building a GLOBAL ecosystem.
INDO-MIM INC — USA
TRIAX — USA
CONWAY MARSH GARRETT — UK
PHOENIX DEVENTURES — USA
INDO-MIM ARMS COMPONENTS — INDIA
+ Mexico associate
And this creates BOTH:
OPTIONALITY
AND
RISK.
Let's look at the subsidiaries.
INDO-MIM INC:
$42.36M revenue
$4.25M PBT
Good.
But,
TRIAX:
$25.88M revenue
-$2.36M PBT
CONWAY MARSH GARRETT:
£3.01M revenue
-£1.03M PBT
PHOENIX:
$6.70M revenue
-$2.90M PBT
Arms Components:
No revenue yet.
THIS IS IMPORTANT.
Indian core is currently doing heavy lifting.
Overseas acquisitions haven't yet demonstrated the same level of profitability across board.
So next chapter isn't simply:
“Will INDO-MIM grow?”
The bigger question is:
CAN INDO-MIM TURN ITS GLOBAL CAPABILITIES INTO GLOBAL PROFITS?
NOW,
PHOENIX IS PARTICULARLY INTERESTING.
Acquired in May 2025.
Medical device prototype manufacturing + design.
Think:
DESIGN
↓
PROTOTYPE
↓
MANUFACTURING
That's a subtle but important evolution.
Because the company can potentially move closer to the customer's product-development cycle.
But,
Phoenix was loss-making in FY26.
So I'm treating this as:
OPTIONALITY.
NOT CURRENT EARNINGS.
AND THEN THERE IS AEROSPACE.
FY26 Aerospace rev:
~₹502 Cr
~12% of total revenue.
INDO-MIM also has AS 9100 certification.
Aerospace is interesting because precision + qualification + reliability can create higher barriers to entry.
But again,
A GOOD INDUSTRY ≠ AUTOMATICALLY GOOD RETURNS.
Execution matters.
NOW LOOK AT BALANCE SHEET.
DISCLAIMER = THIS IS NOT A BUY OR SELL RECOMMENDATION. SHARING ONLY FOR STUDY PURPOSES.

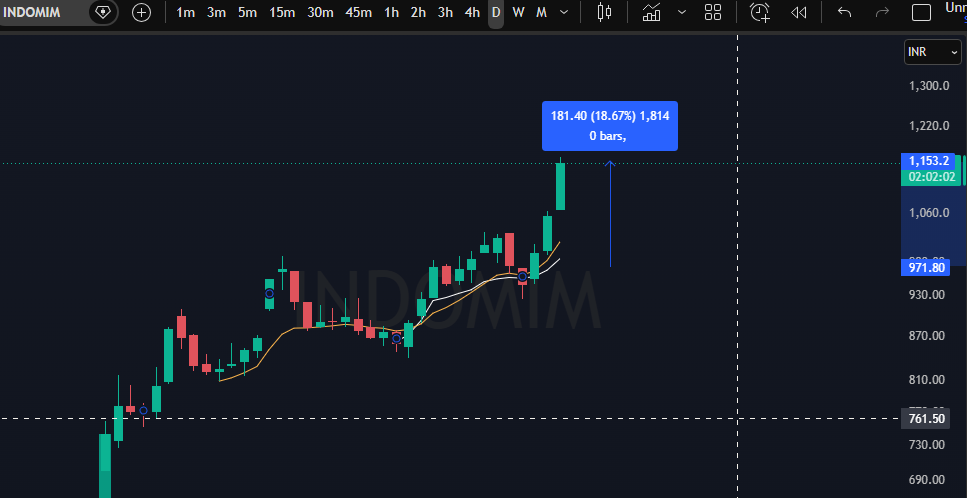

High Momentum Stocks📈
#RossTech
#Sansera
#IndoMIM
#Centum
#Syrma
#Yatharth
#EngineersIndia
#JSWInfra
#Tega
#AcmeSolar

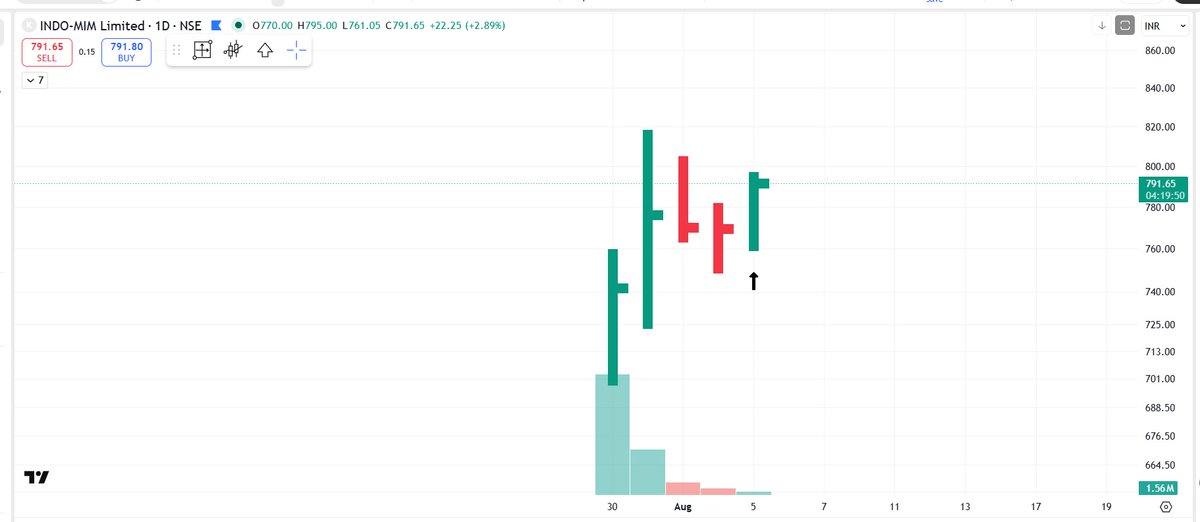
#INDOMIM
Sold Maximum Quantity at 1285🚀🚀🚀
15R Trade 💰💰💰
As Stock clearly look Extended with👇
1⃣So many green days back to back in a row
2⃣Angle of Rise has become steep (Parabolic move)
Power of Rich Liquid Young IPO'S
Here's my link of Entry Position posted real time not End of day (EOD)
https://t.co/MW0jcliEeK


ONE OF MY FAVOURITE #STOCK
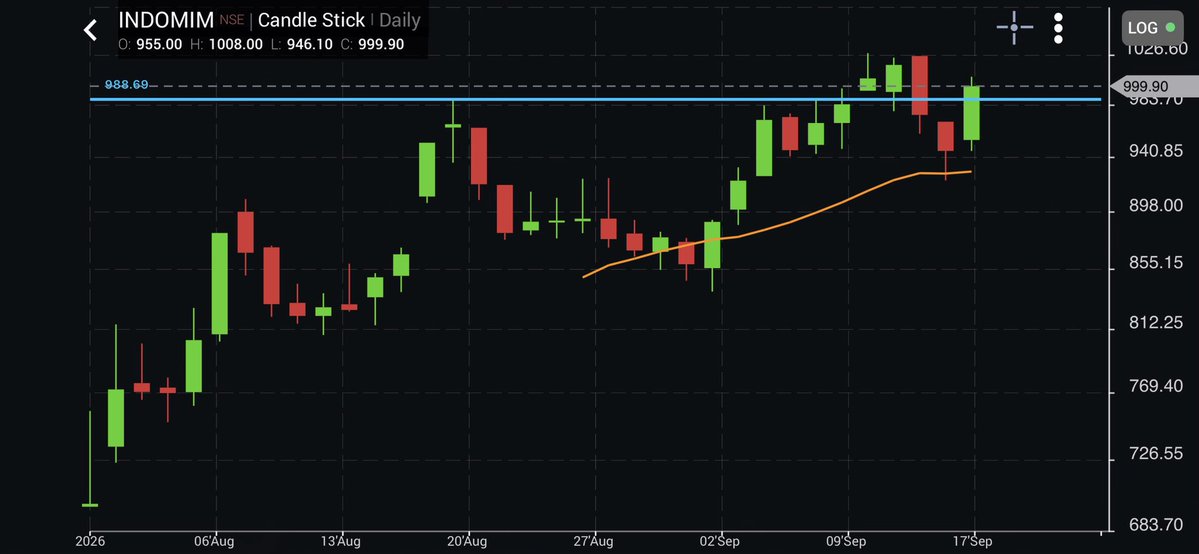
#INDOMIM CMP 999
ENTRY BASED ON #MOMENTUM
#STRONG SECTOR +VERY #STRONG #FUNDAMENTALLY
EXPECTING TARGET 1100/1200/1350+++
3-6 MONTH VIEW
#investing #StockMarketUpdate #stockinfocus @nimeshscnbc @AnilSinghvi_ #stock
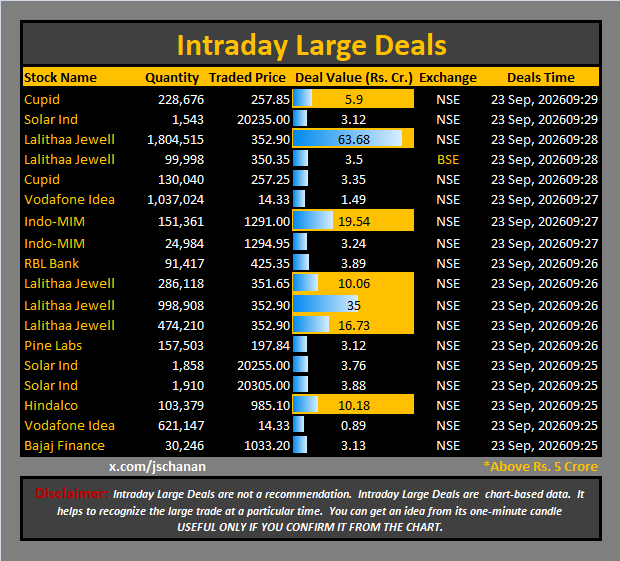
#INDOMIM
UC TODAY
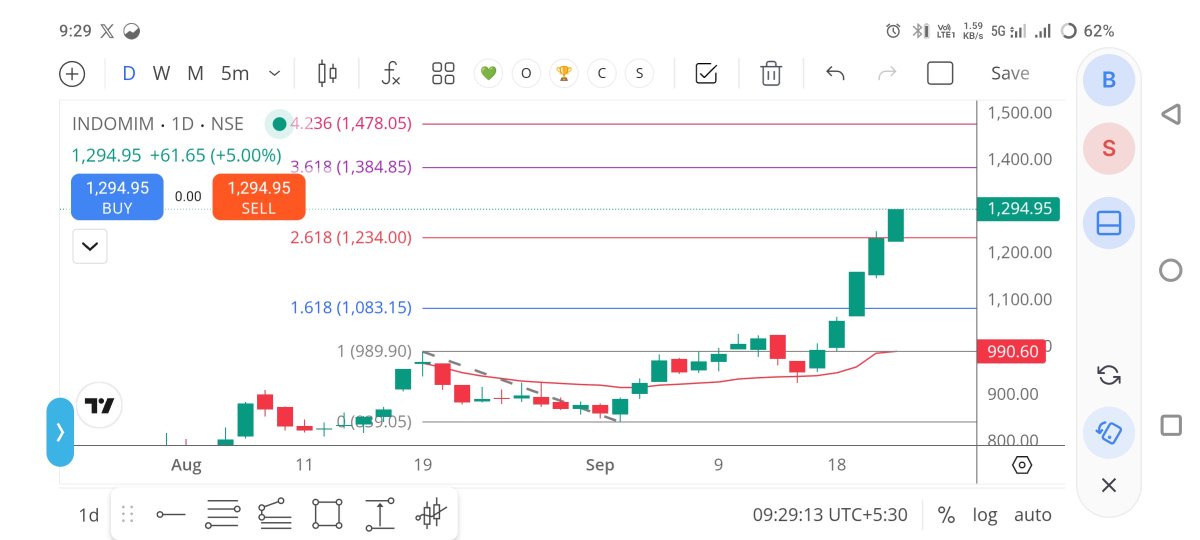

#INDOMIM UP 📈 +5% UC
Last Seen Hashtags on Sotwe
مبادل_الطايف
Seen from Kuwait
granny #nsfw
Seen from United States
snapchat ()()()()()filter:videos
Seen from United States
근친상납
Seen from Korea
หาดใหญ่นัดเย็ด
Seen from Thailand
sextape #beurette
Seen from Belgium
ebony granny
Seen from France
ชายเดี่ยวไซส์ใหญ่
Seen from Thailand
Couples
Seen from South Africa
anxiouspanda
Seen from United Kingdom
Trends for you
Most Popular Users

Elon Musk 
@elonmusk
241.7M followers

Barack Obama
@barackobama
119M followers

Cristiano Ronaldo
@cristiano
114.4M followers

Donald J. Trump
@realdonaldtrump
111.9M followers

Narendra Modi
@narendramodi
107.2M followers

Rihanna
@rihanna
98.7M followers

NASA
@nasa
92.4M followers

Justin Bieber
@justinbieber
91.8M followers

KATY PERRY
@katyperry
90M followers

Taylor Swift
@taylorswift13
83.9M followers

Lady Gaga
@ladygaga
75.4M followers

Virat Kohli
@imvkohli
73.4M followers

Kim Kardashian
@kimkardashian
70.9M followers

YouTube
@youtube
68.8M followers

Neymar Jr
@neymarjr
66.4M followers

Bill Gates
@billgates
65.2M followers

Selena Gomez
@selenagomez
63.1M followers

The Ellen Show
@theellenshow
62.3M followers

CNN
@cnn
61.8M followers

X
@x
60.7M followers