

Top Tweets for #OmnitechEngineering

Some listed companies to study
A few names in the precision-engineering ecosystem:
#IndoMIM
#Aequs
#MTARTechnologies
#PTCIndustries
#AzadEngineering
#DynamaticTechnologies
#SanseraEngineering
#HarshaEngineers
#UnimechAerospace
#OmnitechEngineering
They are NOT identical businesses. Their end markets and competitive advantages are different.

🚨Top 15 Stocks Delivered Blockbuster Q1FY27 Result 🔥
◉ Sales Growth > 50 % 🔥
◉ Profit Growth Upto 35648 % 🔥
A MEGA 🧵 Thread 🧵 👇 👇 👇 👇
1 . Omnitech Engineering Ltd 🔖
#omnitechengineering


🚨Top 15 Stocks Delivered Blockbuster Q1FY27 Result 🔥
◉ Sales Growth > 50 % 🔥
◉ Profit Growth Upto 35648 % 🔥
A MEGA 🧵 Thread 🧵 👇 👇 👇 👇
1 . Omnitech Engineering Ltd 🔖
#omnitechengineering


Omnitech Engineering | Q1 FY27 Results
• Net Profit: ₹30 Cr, ↑471% YoY, ↑1% QoQ
• Revenue: ₹167 Cr, ↑62% YoY, ↑12% QoQ
• EBITDA: ₹51 Cr, ↑91% YoY, ↑2% QoQ
• EBITDA Margin: 30.4% vs 25.7% YoY and 33.5% QoQ
#OmnitechEngineering #Q1FY27 #Earnings #StockMarket #IndianMarkets

मुनाफा बढ़ा, फिर भी शेयर 14% टूटा!
Omnitech Engineering के Q1 नतीजे उम्मीद से बेहतर रहे, लेकिन फिर भी निवेशकों ने जमकर बिकवाली की। आखिर अच्छी खबर के बावजूद स्टॉक क्यों गिरा?
जानें इसके पीछे का मार्केट लॉजिक: [https://t.co/ByCXYH8pSY ]
#OmnitechEngineering #StockMarketIndia #Q1Results #Trading #ShareMarket #Investing #MarketCorrection #ProfitBooking

Biggest #Intraday profit so far
A special milestone in a long trading journey🤞🧿
Grateful for the lessons, proud of the progress, and hungry to keep learning.❤️
Thankss to these Beautyyyyyyyyyy
#OmnitechEngineering
#ShilpaMedicareLtd
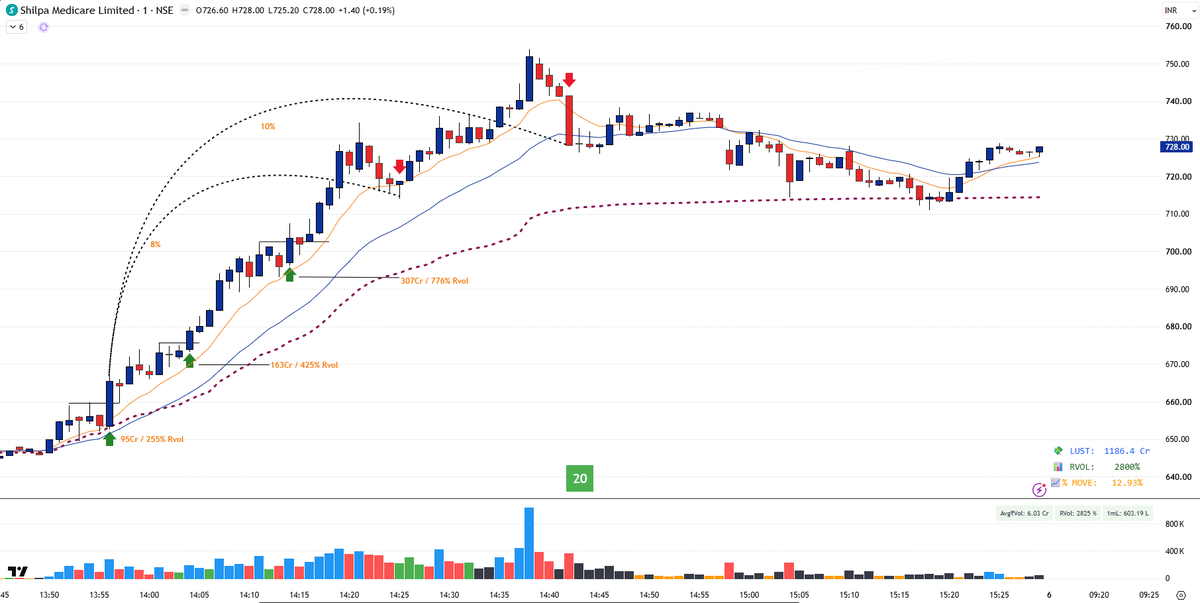
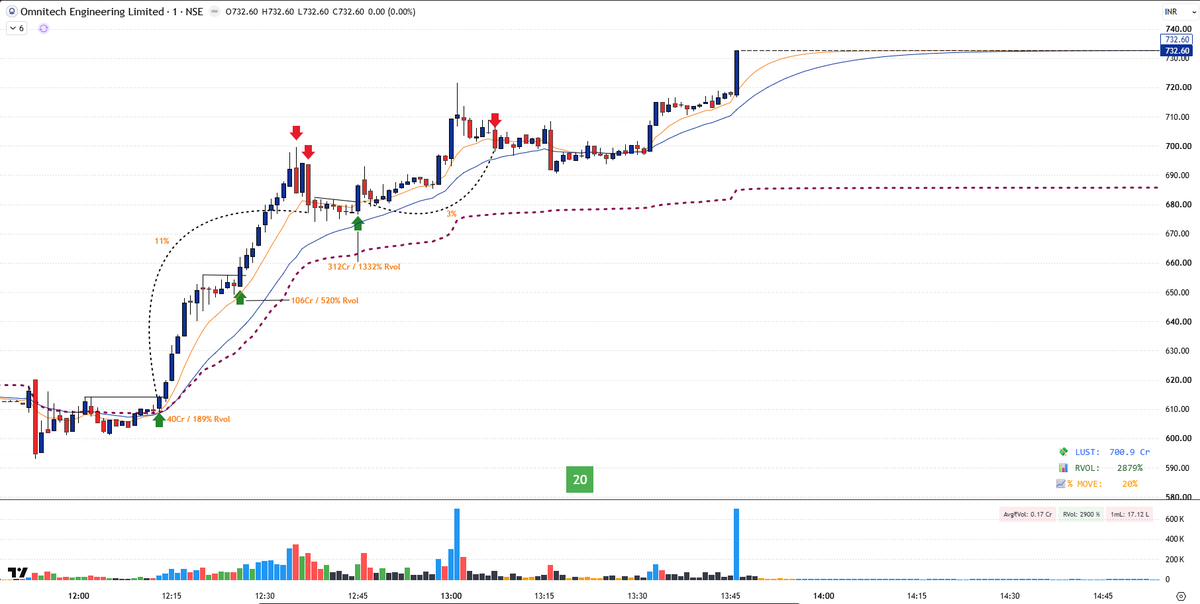

#omnitechengineering
33% EBITDA. 80× trailing P/E. ₹2,910 Crore order book.
Omnitech Engineering isn't cheap. It isn't trying to be.
It's betting that safety-critical precision machining — where clients pay for perfection, not lowest price — can compound at 32% CAGR long enough to justify what the market is paying today.
The machines are running at 100% capacity. Two new plants are being built. The Weatherford contract is just beginning to ramp.
Business story
When Udaykumar Parekh set up Omnitech in Rajkot, he deliberately avoided the obvious — the high-volume, low-margin auto component game that every Gujarat machine shop was chasing. Instead he went deep into a niche most Indian precision shops wouldn't touch: safety-critical, make-to-order components for global energy and automation OEMs.
Mandrels and slips for subsurface oil wells. Braking systems for wind turbines. Actuator rods for factory robots. Hydraulic pistons for cargo loaders at airports.
Parts that operate where human hands can't go, where failure means a $50M blowout or a grounded aircraft. Parts that get replaced regularly regardless of capital cycles. Parts where the buyer doesn't negotiate on price — they just need them to work.
The pivot that changed the scale: becoming an export powerhouse. By putting a warehouse in Houston, Texas, Omnitech became invisible to US buyers as an "Indian supplier." Today 75-79% of revenue is in USD and Euros.
Then the IPO trigger: ₹418Cr of fresh capital to build two new greenfield plants in Rajkot and land in Ahmedabad's GIDC Sanand — turning a ₹511Cr revenue ceiling into a ₹950Cr ceiling by FY28.
The order book confirmed the demand was waiting: ₹2,910 Crore. Up from ₹283 Crore a year ago. A 10× jump in 12 months.
Moat:
Four genuine pillars — three rated Strong, one Moderate:
① 18-36 month vendor qualification bottleneck. Weatherford, Schlumberger, and their peers take 18-36 months to audit and qualify a new manufacturing facility — and the certification is non-transferable. Move the machines to a new building, and the clock resets. This kills competition before it starts.
② Asymmetric switching cost. Omnitech's component is 2-5% of project cost. But if it fails downhole, the cost is a $50M blowout. Clients don't switch to save ₹50/part. They stay. 85%+ of bookings are repeat orders.
③ Rajkot cluster cost edge. Cheap skilled machinists, local forge networks, lower land costs — Omnitech's 30.7% EBITDA vs Jyoti CNC's 14% isn't just pricing power, it's structural geography.
④ No formal IP: Moderate. The OEM owns the design. Omnitech owns the process knowledge — CNC programs, fixture setups, toolpath sequences. A well-capitalised clone could replicate this in 5-7 years. It just hasn't.
Valuation & the 32% CAGR math
FY26 A: Rev ₹511Cr | EBITDA 33.5% | PAT ₹77Cr | EPS ₹6.28 | CFO -₹2Cr | ROIC 17.6%
FY27 E: Rev ₹675Cr | EBITDA 33.7% | PAT ₹118Cr | EPS ₹9.60 | CFO ₹62Cr | ROIC 19.2%
FY28 E: Rev ₹891Cr | EBITDA 34.4% | PAT ₹174Cr | EPS ₹14.17 | CFO ₹145Cr | ROIC 22.4%
At ₹536/share, forward P/E is 37.8× FY28 earnings
Growth triggers:
✅ ₹2,910Cr order book — 90%+ of FY27 revenue already confirmed
✅ ₹1,030Cr Weatherford contract ramping: ₹80-100Cr in FY27 → ₹250-300Cr/year thereafter
✅ Plant 1 commissioned Q3 FY27, Plant 2 Q2 FY28 — capacity ceiling rises ₹511Cr → ₹950Cr
✅ Aerospace/defence qualification in progress — highest-margin vertical entering FY28+
Red flags:
⚠ Debtor days at 153 — long US payment cycles trap cash; scaling worsens this before it improves
⚠ CFO negative two consecutive years — profits are real, cash isn't yet
⚠ New plant validation by OEMs adds 18-36 months before new capacity generates revenue
⚠ Customer concentration: 75-79% revenue from US/Euro energy OEMs — one capex cycle cut hits hard
Management quality & governance
The IPO structure tells the right story: ₹418Cr of ₹583Cr raised was fresh issue capital — straight into the balance sheet for capacity expansion and debt paydown. Only ₹165Cr was OFS. Promoters didn't use the IPO to exit.
Professional hires in key seats: Bhavin Acharya runs international sales, Chandrashekhar Kullolli runs the factory floor, and Raul Perez sits in Houston physically managing the Weatherford relationship.
Governance flags:
⚠ Highly centralized — Parekh holds final authority on all major client and capex decisions; succession planning not visible
⚠ Pre-IPO RPTs with local Rajkot foundries — now formalized post-listing but audit committee vigilance required
Order pipeline — does ₹2,910Cr justify 37.8× FY28 P/E?
The order book jumped from ₹283Cr (FY25) to ₹2,910Cr (FY26). A 10× move in 12 months. Let's unpack what's inside.
₹1,030Cr — Weatherford Products GmbH. This is the anchor. A multi-year master purchase agreement for oilfield subsurface components. Structured to ramp progressively: ₹80-100Cr in FY27, building to ₹250-300Cr/year in FY28-29 and beyond. It doesn't front-load — which is why 50% growth is physically impossible — but it provides long, durable annuity-like revenue.
90% of FY27 revenue is already in confirmed orders — the remaining 10% is essentially book orders Omnitech hasn't formally signed yet from existing clients who reorder mechanically.
The pipeline beyond Weatherford:
→ Schlumberger and other Tier-1 oilfield service majors under repeat MPA frameworks
→ Industrial automation and motion control: actuator, drive, and conveyor component programs
→ Aerospace/defence: in qualification — not yet revenue but 18-36 months away from initial orders
The structural buffer most people miss: these components wear out and need regular replacement regardless of new oil well drilling activity. Even in a global capex downturn, the aftermarket replacement cycle keeps Omnitech's factory loaded.
Watch FY27 Q3 (Plant 1 commissioning) and FY28 Q2 (Plant 2 commissioning) as the critical execution milestones. New plants need OEM validation before new revenue flows — and that clock is ticking.
Closing thesis
37.8× on FY28 is not cheap. For a precision engineering capital goods business with 153-day debtor cycles, negative historical CFO, and customer concentration in US energy OEMs, it requires a lot to go right.
The triggers to watch in order of importance:
✅ FY27 revenue of ₹675Cr — capacity ceiling of ₹720Cr, so execution margin is thin
✅ Plant 1 commissioned Q3 FY27 and OEM-validated without delays
✅ Weatherford Year 2 stepping up to ₹250Cr run-rate — the real CAGR engine
✅ CFO turning strongly positive — proves cash is finally following profits
✅ Aerospace qualification announced — re-rating catalyst for the next earnings cycle
The thesis cracks if:
⚠ Global oil capex cuts — Weatherford and Schlumberger pull back orders
⚠ Plant validation delays — new capacity sits idle while depreciation hits P&L immediately
⚠ Debtor days don't improve — working capital crunch returns
[Not investment advice, DYOR]


Omnitech Engineering Q1 2027 Earnings
~Revenue ₹166.66 Crores,
Up 61.4% YoY, Up 12% QoQ
~EBITDA Margin at 30.37%,
Up from 25.71% YoY & down from 33.46% QoQ
~Net Profit at ₹29.73 Crores,
Up 470.83% YoY, Up 1.45% QoQ
#OmnitechEngineering #Q1FY27 #StockMarket #investing


Omnitech Engineering’s order book jumps 970%
Omnitech Engineering’s order book has grown from ₹283 crore in FY25 to over ₹3,030 crore as of May 2026.
Strong demands came from the energy, aerospace and automation sectors.
Source: Trade Brains
#OmnitechEngineering #OrderBook


IMHO Defence n Aerospace is where Indian IT was 20 years back. Many Multibaggers and Multibeggars will be created in this space. My watch list
#SigmaAdvanced @ 583
#RossellTechsys @ 1000
#JaykayEnterprises @ 185
#OmnitechEngineering @ 523
Will keep updating it 👀

Omnitech Engineering
#Omni
#Omnitech
#OmnitechEngineering
Good Q3FY26
Highest ever revenue, EBITDA, PBT and PAT in comps history
Good QoQ uptick
Solid YoY growth
Rev at 134cr vs 74cr⏫82%
Q2 at 125cr⏫8.4% QoQ
Other income at 4cr vs 7cr QoQ
EBITDA at 51cr vs 24cr⏫118%
Q2 at 45cr⏫18%
OPM at 38% vs 32%⏫617bps
Q2 at 36.5%⏫90bps
PBT at 33cr vs 11cr up 3x YoY
Q2 at 29cr
PAT at 22cr vs 8cr⏫293%
Flat QoQ
Higher tax paid QoQ
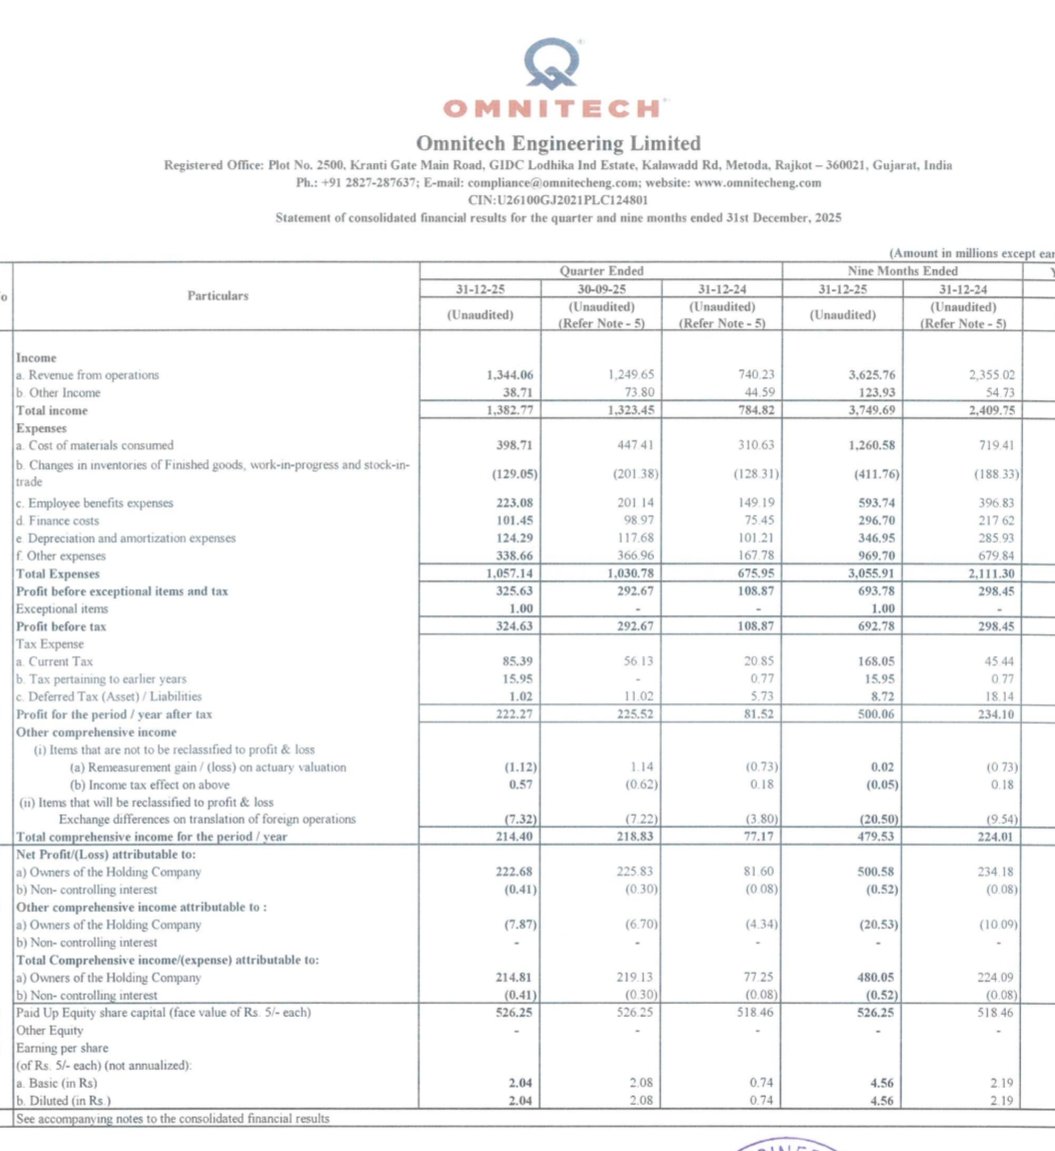
Omnitech Engineering
#Omni
#OmnitechEngineering
#Omnitech
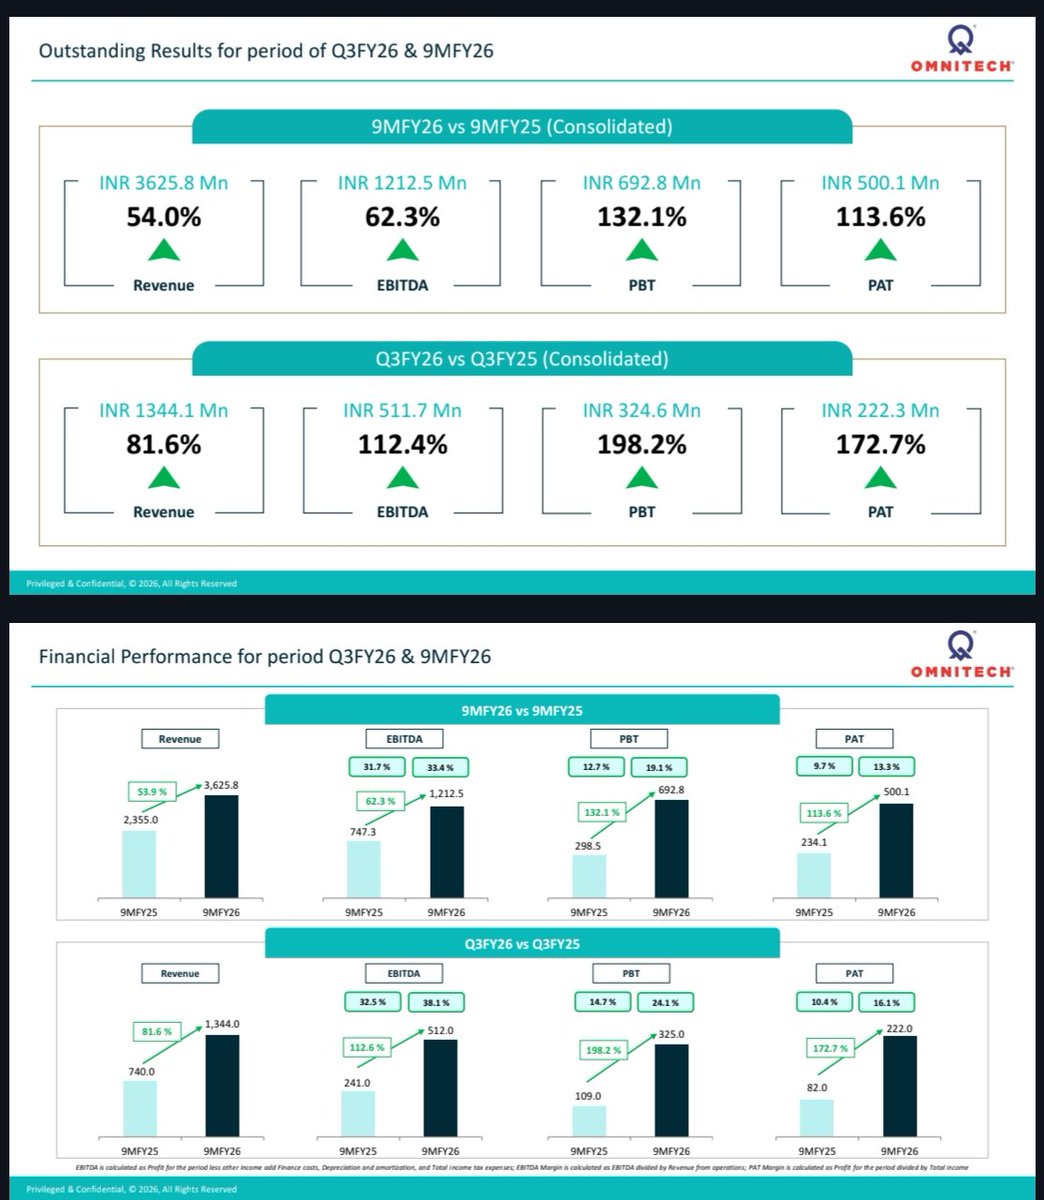
Maiden Inv PPT:
9MFY26:
Rev at 363cr⏫54%
EBITDA at 121cr⏫62%
OPM at 33.4% vs 31.7%
PBT at 69cr⏫132%
PAT at 50cr⏫114%
Q3FY26:
Rev at 134cr⏫82%
EBITDA at 51cr⏫112%
OPM at 38.1% vs 32.5%⏫570bps
PBT at 32cr⏫198%
PAT at 22cr⏫173%
RoCE 18.4%
RoE 24.1%
Orderbook at 2910cr as on 11th March
Recently set up a fabrication line with annualized fabrication capacity of 7200 MTPA
Need to track WC and D/E going forward
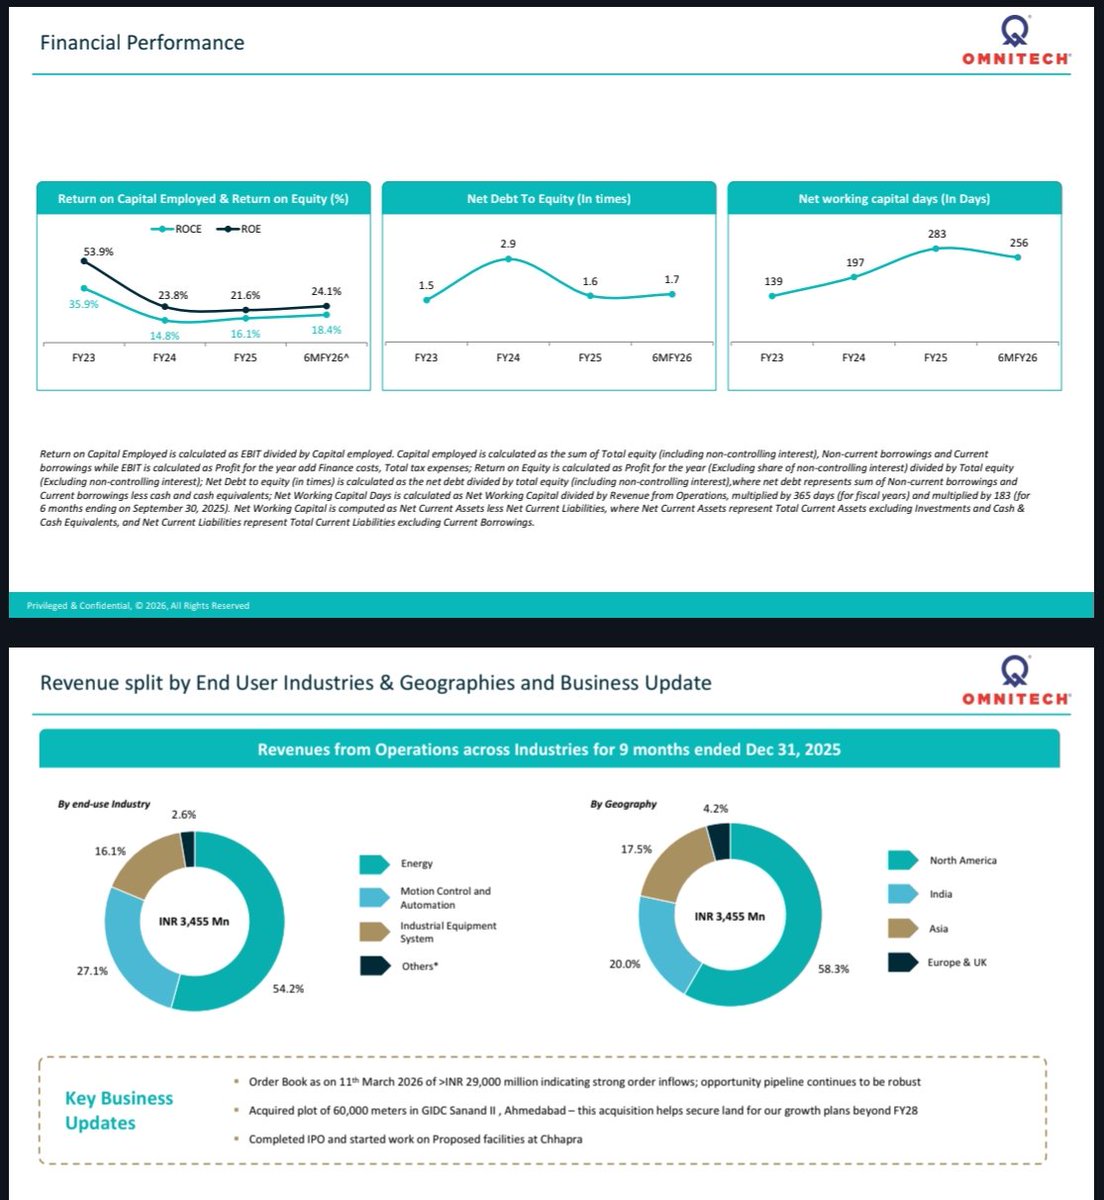


#OmnitechEngineering likely to list flat as grey market premium stays nil
@senmeghna
https://t.co/Aw8aIchQxK

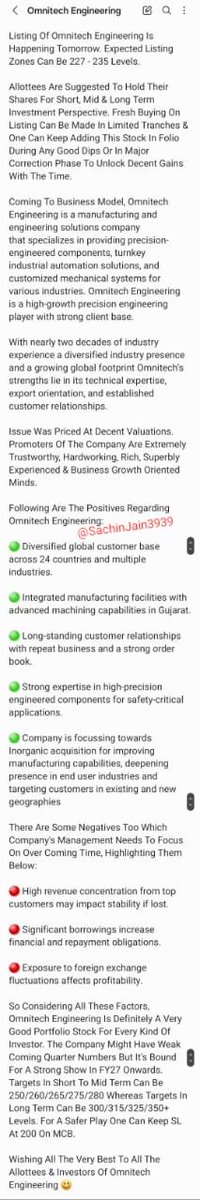
My Notes On Omnitech Engineering With Detailed Analysis & Listing Day Strategy #OmnitechEngineering #IPO

Omnitech engineering
lists at -11% ❌😅
as we have seen yesterday
Same playbook, circus listings!!
Extremely high risk takers tried, but market didn't care much as of now 🥲
#IPOAlert
#OmnitechEngineering

#WATCH | Omnitech Engineering’s Udaykumar Parekh breaks down the recent order book win with Weatherford Products, highlighting a strong revenue visibility boost over the next five years and key growth drivers ahead
#OmnitechEngineering #OrderBook #RevenueGrowth #EnergySector @SnehiShah11 @omnitecheng
#OmnitechEngineering's ₹583-crore #IPO opens today: Should you subscribe?
@senmeghna
https://t.co/it17JdIQ3z

#OmnitechEngineering IPO Day 3: Check GMP, subscription status, and broker views
#ETMarkets
https://t.co/ewWhZpFxKm

Omnitech Engineering has successfully raised ₹174 crore from 17 anchor investors ahead of its IPO, which opens today.
(@chit_ranjan reports)
#OmnitechEngineering #IPO
https://t.co/uqkC1fx43p
D-Street Debut
#OmnitechEngineering shares list at 11% discount to IPO price
#ETMarkets
https://t.co/owVazyWaAJ

Last Seen Hashtags on Sotwe
mgai
Seen from United Kingdom
hentai
Seen from United States
taboo
Seen from Turkey
gfe
Seen from United States
หลุดทวิต
Seen from Thailand
الخبز_الحمر
Seen from United States
nolimitt
snapchat
Seen from United States
mgai(**********************************************************************************************************) filter:videos
Seen from United States
Most Popular Users

Elon Musk 
@elonmusk
241M followers

Barack Obama
@barackobama
118.8M followers

Cristiano Ronaldo
@cristiano
114.5M followers

Donald J. Trump
@realdonaldtrump
111.9M followers

Narendra Modi
@narendramodi
107M followers

Rihanna
@rihanna
98.7M followers

NASA
@nasa
92.2M followers

Justin Bieber
@justinbieber
91.8M followers

KATY PERRY
@katyperry
90M followers

Taylor Swift
@taylorswift13
84M followers

Lady Gaga
@ladygaga
75.5M followers

Virat Kohli
@imvkohli
73.4M followers

Kim Kardashian
@kimkardashian
70.8M followers

YouTube
@youtube
68.7M followers

Neymar Jr
@neymarjr
66.4M followers

Bill Gates
@billgates
65.2M followers

Selena Gomez
@selenagomez
63.1M followers

The Ellen Show
@theellenshow
62.2M followers

CNN
@cnn
61.7M followers

X
@x
60.6M followers