

Top Tweets for #PAYROLLS


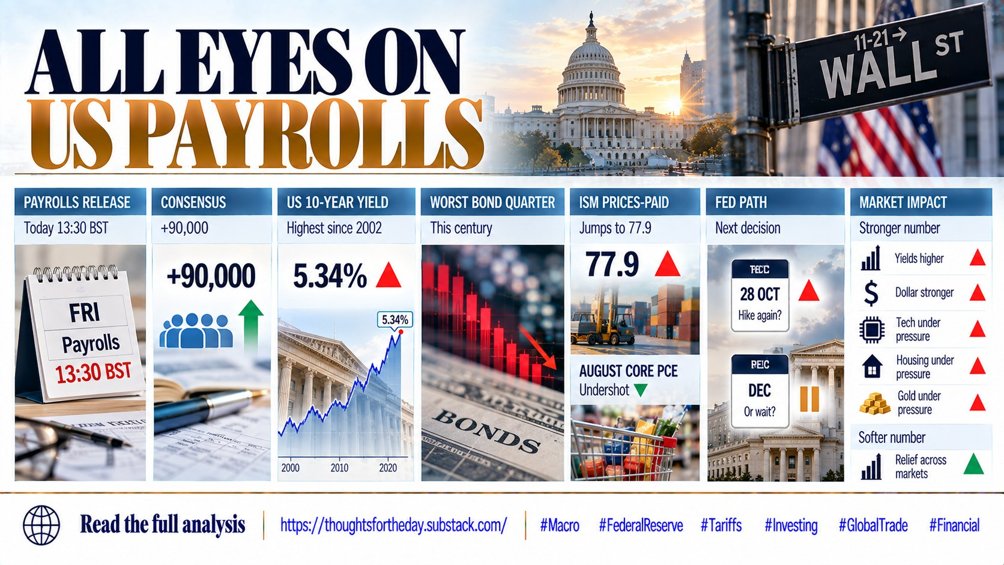
Today's September #payrolls, due at 13:30 BST with consensus at +90,000, land on a #Treasury market that touched 5.34% on the 10-year on Thursday, its highest since 2002, after the worst #bond quarter this century. The #ISM prices-paid index jumped to 77.9 even as August core #PCE undershot, so the print decides whether the #Fed hikes again on 28 October or waits until December. A strong number with firm #wages would retest the #yield high, extend the #dollar index at its strongest since May 2025 and pressure long-#duration #technology, #housing and #gold, while a soft number offers relief across all of them at once.
Thoughts of the day, Daily Market News over the last 24 hours.
Read more, for the full analysis
Thoughts for the day NEWS
https://t.co/NkkUDWNjiJ
Review our quarterly earnings updates page.
https://t.co/dKwXKoXwsy
#FederalReserve #Tariffs #Investing #GlobalTrade #FinancialMarkets
Follow me on X, search for @GryphonIAB
INTELLIGENCE ASSESSMENT
The dominant #macro driver is a policy convergence in which the marginal move across the developed world has flipped from cut to hike, and the #energy complex is what makes it self-reinforcing. August #payrolls printed at 162,000 against a 56,000 consensus with #unemployment steady at 4.1%, taking the market-implied probability of a #FED Federal Reserve increase on 16 September to roughly 60% from around 50%; the #ECB European Central Bank meets on Thursday with a 25bp move to 2.50% substantially discounted; economists expect the #BOJ Bank of Japan to lift rates on 18 September; and three #BOE Bank of England members voted for 4.00% in July. #Crude near $100 sustains the headline impulse that keeps every one of those hands forced. The tension is that this is a supply-driven #inflation being answered with demand-side instruments, into #labour markets none of these central banks describes as overheating. The core mispricing sits in the assumption that a single insurance hike settles the question rather than opening a sequence.
The positioning evidence points to a different vulnerability than the #rates debate suggests. Japanese #curve steepening has become the reference signal for global hashtag#duration, with rising #JGB term premia biasing #Treasury and #gilt curves toward the same move as fiscal and duration risk outweighs short-rate expectations — Japan is now exporting term premium rather than importing it, which inverts the causality most cross-asset models assume. Against that, the #PBOC People's Bank of China added 650,000 ounces of #gold in August for a twenty-second consecutive month, #copper set a record for a second straight session with global mined production at risk of its first annual decline since 2017, and US spot #bitcoin ETFs took $987m in the week to 4 September. Official-sector and institutional demand is migrating into hard assets while the marginal buyer of long-dated #sovereign debt thins. The asymmetry into Friday's #CPI is two-sided in an unusual way: a firm print hits #equities and bonds together with the #dollar unable to rally against a tightening Bank of Japan, while a soft print unwinds a crowded rates short without resolving the supply-side inflation that created it. The correlation breakdown, not the level of any index, is the exposure to carry into the #FOMC.
Thoughts of the day, Daily Market News over the last 24 hours.
Read more, for the full analysis
Thoughts for the day NEWS
https://t.co/IC6iLnU1A6
Review our quarterly earnings updates page.
https://t.co/dKwXKoXwsy
#FederalReserve #Tariffs #Investing #GlobalTrade #FinancialMarkets
Follow me on X, search for @GryphonIAB

#UBS – After US #payrolls rose by 162,000, UBS now expects two 25bp Fed hikes in September and December. It previously expected no hikes this year.
This week’s inflation data will now decide whether that hawkish shift can continue.
My take: The #USD no longer needs a hot inflation report to strengthen. It only needs inflation to remain firm enough.
That gives the #dollar a near-term advantage, particularly if the #ECB hikes this week but signals a long pause.
#UBS: #Markets’ responses to last Friday’s US employment report rebuke US #monetarypolicy communication. The report showed strong #payrolls growth, but unemployment rates drifted very slowly higher. The #labormarket is not creating accelerating wages. #Market #ratehike expectations increased, but the decision is still essentially a coin toss. With a clearly communicated framework for monetary policy, #markets would not be plagued by such indecision.
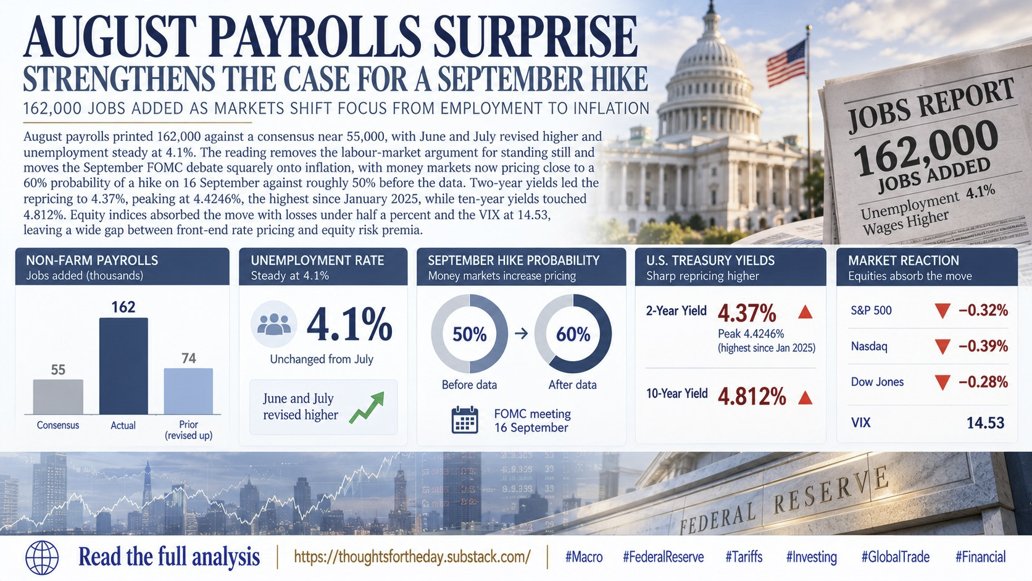
August #payrolls printed 162,000 against a consensus near 55,000, with June and July revised higher and #unemployment steady at 4.1%. The reading removes the #labourmarket argument for standing still and moves the September #FOMC debate squarely onto #inflation, with money markets now pricing close to a 60% probability of a hike on 16 September against roughly 50% before the data. Two-year #yields led the repricing to 4.37%, peaking at 4.4246%, the highest since January 2025, while ten-year yields touched 4.812%. #Equity indices absorbed the move with losses under half a percent and the #VIX at 14.53, leaving a wide gap between front-end rate pricing and equity risk premia.
Thoughts of the day, Daily Market News over the last 24 hours.
Read more, for the full analysis
Thoughts for the day NEWS
https://t.co/Dd2XYt04CW
Review our quarterly earnings updates page.
https://t.co/dKwXKoXwsy
#FederalReserve #Tariffs #Investing #GlobalTrade #FinancialMarkets
Follow me on X, search for @GryphonIAB
INTELLIGENCE ASSESSMENT
The dominant #macro driver is a #labour market that has refused to break at precisely the moment the #inflation impulse is being re-energised from the #energy complex. Friday's #payrolls did not merely beat, they beat by a factor of three, with prior months revised up, which removes the deteriorating-demand justification for policy patience and leaves #wage #growth at 3.1% as the only remaining dovish thread. The front end responded properly, with two-year #yields at levels last seen in January 2025, the #dollar index firming to 99.17 and precious #metals surrendering part of a two-session rebound. #Equities did not. An S&P 500 decline of 0.38% and a #VIX at 14.53 are not the pricing of a market assigning a coin-flip probability to a September rate rise while a shipping war runs in the world's most important oil chokepoint. That divergence between front-end rate pricing and #equity #volatility is the cleanest mispricing currently on the board.
Positioning explains part of it. Friday's tape was rotation rather than de-risking: the Philadelphia #Semiconductor Index gained 3.38% on #OpenAI's GPT-6 Astra launch while #Apple, #Alphabet and #Microsoft carried the index losses, and that rotation extended into Asia on Monday with the Nikkei up around two percent and the Kospi over three. Measured flow corroborates it, with spot #bitcoin ETFs taking $986.9 million last week and $3.8 billion over three weeks even as rate expectations turned hawkish. The second-order risk is that the energy channel converts a rates question into an inflation question before equity risk has repriced: #Brent above $96 and record U.S. #diesel feed directly into an 11 September #CPI landing five days before the #FOMC. The asymmetry is unattractive, because a soft print buys a relief rally already partly discounted while a firm one collides with a supply premium no central bank can offset. #Sterling and the #euro sit in the crossfire through yield differentials, with the #ECB on 10 September and the #BOE Bank of England on 17 September bracketing the #Fed and neither able to cut into an energy shock.

#TDSecurities – Strong #NFP Lifts the #USD, but the Rally May Not Last
US #payrolls rose by 162K, well above the 55K consensus, while previous months were revised up by 55K.
#Unemployment remained at 4.1% and participation increased to 61.6%, confirming a solid labour market.
The data pushed US yields and the #USD higher and increased the probability of a September #Fed hike to around 60%.
However, wage growth slowed to 3.1%, showing limited inflation pressure from employment.
Next week’s #CPI will be far more important for the Fed and the #dollar.
#TD remains broadly bearish on the #USD and expects only limited gains against the #CAD and #CNH.
Key takeaway: Strong employment supports the #USD temporarily, but a lasting rally requires an upside inflation surprise. Even if the #Fed hikes, dollar gains should be much smaller than in 2022 because other central banks are also tightening.

AUGUST 2026 Employment Situation (Jobs) Report
> Nonfarm Payrolls: +162,000
> U-3 Jobless Rate (Headline): 4.1% <
MORE: > https://t.co/cIlbQfvfBB <
MORE: > https://t.co/kZ24WvsL7M <
#FedPrimeRate #Jobs #Labor #Unemployment #Wages #Payrolls #Employment #Work #Career #Careers

Aug Employment Report stronger than expected
Nonfarm payrolls
+162K vs +56K consensus vs +21K in Jul
Unemployment rate
4.1% vs 4.1% consensus vs 4.1% in Jul
Average hourly earnings
+0.3% MoM vs +0.3% consensus vs +0.2% in Jul
#employment #unemployment #payrolls
US AUGUST #PAYROLLS LAND TODAY AS THE FINAL DATA POINT BEFORE THE #FED'S SEPTEMBER MEETING
Key Details: The #BureauOfLabor Statistics releases the August #employment situation at 8:30 ET, with consensus looking for #growth of just 53,000 #nonfarm #payrolls and #unemployment holding at 4.1%. June and July counts together showed a net loss of 3,000 #jobs, and initial August numbers have been revised lower in each of the past four years. The #FOMC meets 15-16 September with expectations unusually finely balanced after #Waller reopened the possibility of leaving rates unchanged, and with #inflation simultaneously threatened by elevated #energy prices, making the #employment-wage combination more important than the headline payroll number alone.
Impact Assessment: The reaction function is inverted this cycle: a strong print is the hawkish outcome and a soft one removes hike risk. With participation at multi-decade lows, the breakeven pace needed to hold unemployment steady sits far below historical norms, so small payroll numbers no longer signal weakness. Hedge funds running short-duration or long-dollar positions face particularly significant event risk.
Thoughts of the day, Daily Market News over the last 24 hours.
Read more, for the full analysis
Thoughts for the day NEWS
https://t.co/BFfDWjnxSV
Review our quarterly earnings updates page.
https://t.co/dKwXKoXwsy
#FederalReserve #Tariffs #Investing #GlobalTrade #FinancialMarkets
Follow me on X, search for @GryphonIAB


#USA PRIVATE #PAYROLLS RISE JUST 38,000 IN AUGUST, WEAKEST SINCE JANUARY
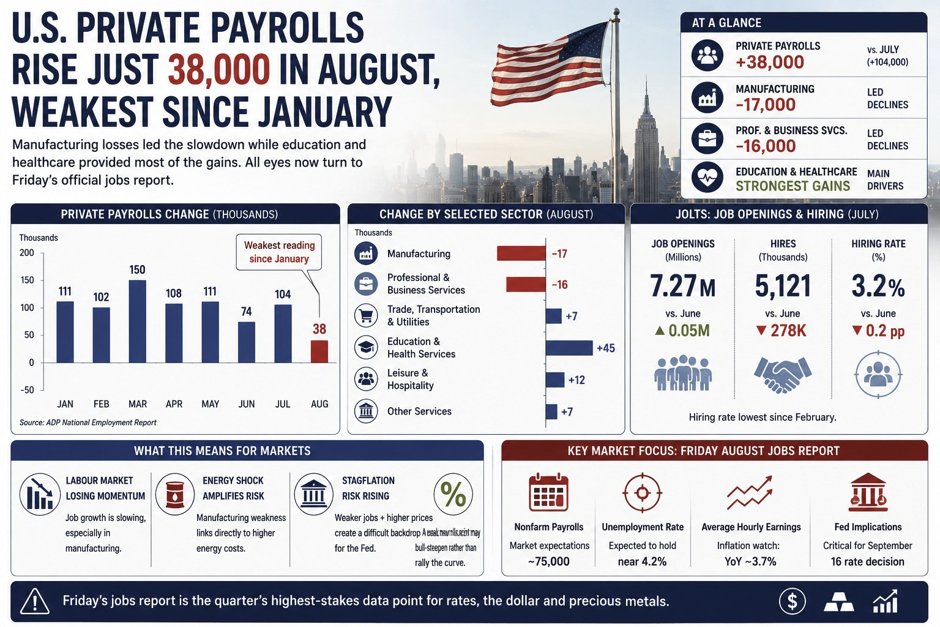
Key Details: Private employers added only 38,000 jobs in August, below expectations near 47,000 and the weakest reading since January, with the #slowdown led by #manufacturing losses of 17,000 while professional and business services shed 16,000 and education and healthcare generated most of the gains. July job openings edged up to 7.27 million, but hiring fell by 278,000, taking the hiring rate down 0.2 points to 3.2%, its lowest since February. Friday's official employment report is the next test of the rate path.
Impact Assessment: Manufacturing-led weakness ties the #labour softening directly to the #energy shock rather than broad demand destruction, producing the classic #stagflationary bind. Softer hiring would ordinarily support #Treasuries, but the oil shock weakens that relationship and a poor payroll report could bull-steepen rather than rally the curve. Friday is the quarter's highest-stakes data point for rates, the dollar and precious metals.
Thoughts of the day, Daily Market News over the last 24 hours.
Read more, for the full analysis
Thoughts for the day NEWS
https://t.co/QXIcp3rvim
Review our quarterly earnings updates page.
https://t.co/dKwXKoXwsy
#FederalReserve #Tariffs #Investing #GlobalTrade #FinancialMarkets
Follow me on X, search for @GryphonIAB
#BNY: #USD: September begins with a search for confirmation. Momentum exists, but #payrolls, #PMIs, #inflation and policy decisions now need to show that it’s broad enough to endure.
JULY 2026 Employment Situation (Jobs) Report
> Nonfarm Payrolls: -23,000
> U-3 Jobless Rate (Headline): 4.1% <
MORE: > https://t.co/KRjz1Xgkf6 <
MORE: > https://t.co/kZ24WvsL7M <
#FedPrimeRate #Jobs #Labor #Unemployment #Wages #Payrolls #Employment #Work #Career #Careers

Korea's youth employment decline has extended to its longest streak since the 2008-09 global financial crisis.
#Korea #USA #economy #semiconductors #artificialintelligence #software #youth #employment #jobs #payrolls #unemployment #growth #NEET
https://t.co/E5InaEXDcL
Nutshell – #Rabobank: #EURUSD has risen mainly because of #USD weakness, not because of #EUR strength. The euro remains the third worst-performing #G10 currency year-to-date.
The weak US #payrolls report reduced expectations of further Fed hikes, weighing on US yields and the #USD. Rabobank expects the #Fed to keep rates unchanged, leaving room for further #USD softness.
The #Eurozone economy has been more resilient than expected, with stronger Q2 GDP (+0.4% q/q) and improving July #PMI data. However, #Rabobank believes some of that optimism was temporary.
Headwinds for #Europe remain significant: higher energy costs, uncertainty after the breakdown of the US-Iran agreement, weaker German labour market, slowing wage growth and pressure from Chinese competition.
A stronger #euro is not necessarily good news. While it would help lower inflation, it would also hurt #Eurozone exporters, particularly #Germany.
Another #ECB rate hike is already priced in, so it is unlikely to provide much additional support for the euro.
Forecast: #Rabobank expects $EURUSD to edge up to around 1.16 within three months, driven mainly by a weaker #USD rather than a stronger #EUR. However, they do not expect a major #EUR rally unless #Eurozone growth surprises to the upside.
#DeutscheBank: #USD: Our economists view the #NFP report as consistent with a broadly stable labour market rather than a sharp deterioration, noting that demographic factors continue to weigh on participation. The softer #payrolls data has reduced the urgency for further #Fed tightening in the near term, but with labour market slack only gradually increasing, it's over to Wednesday's #USCPI.

US jobs market sends a warning signal.
Nonfarm #payrolls fell by 23,000 in July, against expectations of 83,000 additions.
May and June were also revised down by 103,000.
A weakening labour market could strengthen the case for #Fed rate cuts, potentially supporting global liquidity, #emerging markets and #gold.


Trends for you
Most Popular Users

Elon Musk 
@elonmusk
241.5M followers

Barack Obama
@barackobama
118.9M followers

Cristiano Ronaldo
@cristiano
114.6M followers

Donald J. Trump
@realdonaldtrump
111.8M followers

Narendra Modi
@narendramodi
107.1M followers

Rihanna
@rihanna
98.7M followers

NASA
@nasa
92.3M followers

Justin Bieber
@justinbieber
91.8M followers

KATY PERRY
@katyperry
90.1M followers

Taylor Swift
@taylorswift13
84M followers

Lady Gaga
@ladygaga
75.5M followers

Virat Kohli
@imvkohli
73.5M followers

Kim Kardashian
@kimkardashian
70.9M followers

YouTube
@youtube
68.8M followers

Neymar Jr
@neymarjr
66.5M followers

Bill Gates
@billgates
65.3M followers

Selena Gomez
@selenagomez
63.1M followers

The Ellen Show
@theellenshow
62.2M followers

CNN
@cnn
61.7M followers

X
@x
60.7M followers