

Top Tweets for #SAILIFESCIENCES

4/ 🔬 #SaiLifeSciences Innovator pharma + biotech outsourcing.
📌 Discovery chemistry → development → commercial manufacturing.
5/ 🧬 #Anthem Biosciences
CRDMO across small molecules + biologics.
📌One of the most interesting new-age listed CRDMO stories.

3. #SaiLifeSciences
One of the more interesting CRDMO plays.
FY27 capex guidance: ₹1,100–1,300 cr vs ₹633 cr in FY26.
More importantly, the balance sheet has improved dramatically:
Net debt/EBITDA fell from 5.6x to just 0.04x.
The company is also entering peptides, with a development lab and a planned greenfield manufacturing facility.
That gives it room to invest without stretching the balance sheet.

Behind every molecule is a patient waiting for a better tomorrow. Our Associate Director, Medicinal Chemistry, Suleman Maujan, reflects on the purpose that drives medicinal chemistry beyond the laboratory.
#sailifesciences #crdmo #pharma #cro #drugdiscovery

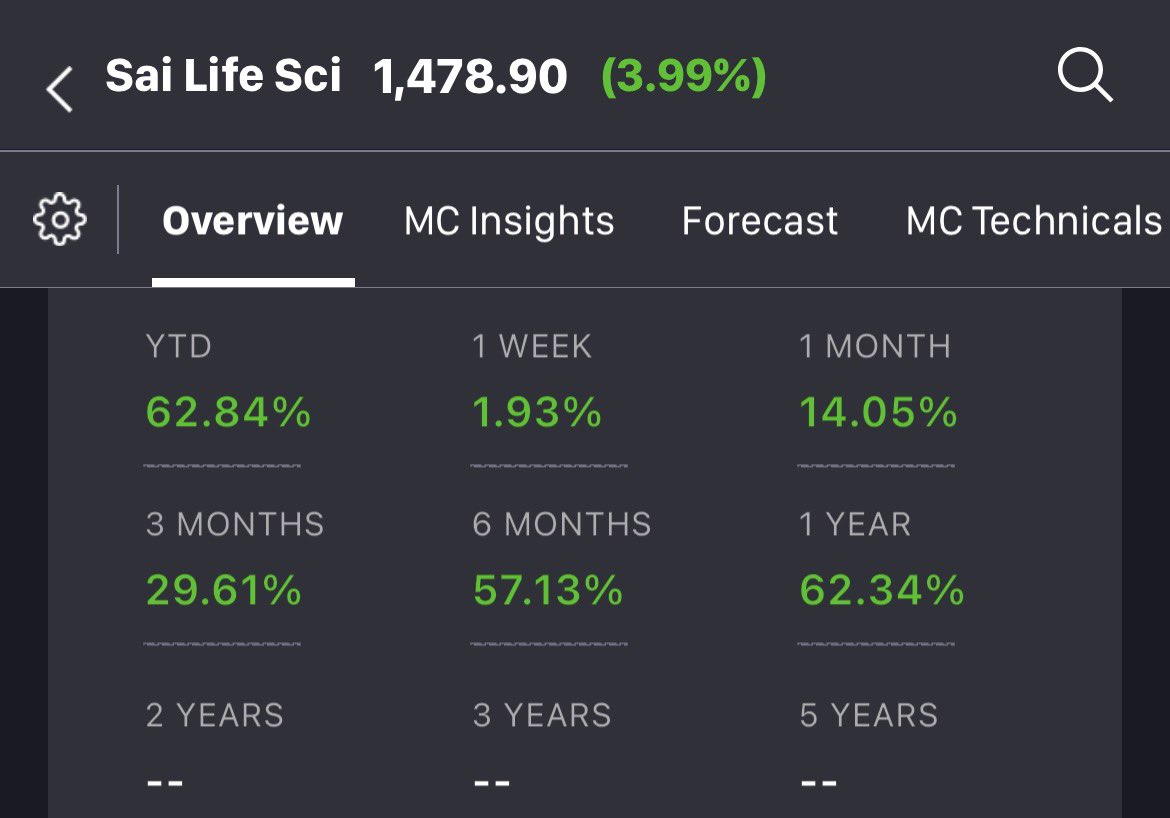
Sai Life Sciences up 62% in last 1yr n has strong fundamentals behind it:
FY26 Revenue +29%, EBITDA +56%
PAT +109%, Margins near 30%
CRDMO demand, capacity expansion lead to strong growth…
#SaiLifeSciences #CRDMO #Pharma

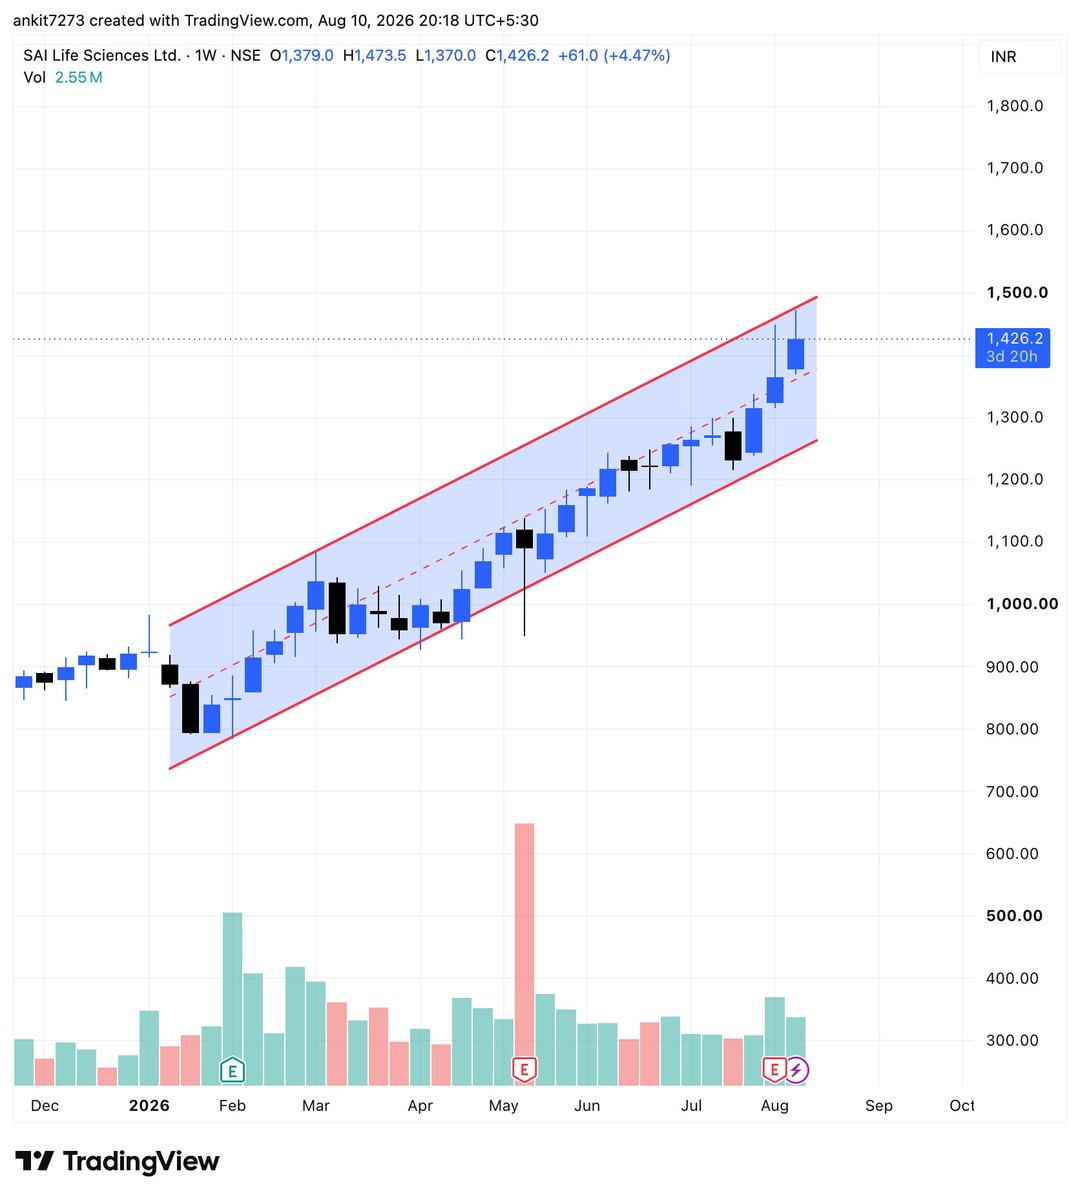
#SAILIFE | One-way rally so far. 🚀📈
The stock has delivered a strong, relentless move.
After such a run, is it finally time to relax and let the trend breathe? 😎
No need to chase — let the price action do the talking.
#SAILIFE #SaiLifeSciences #PharmaStocks #StockMarket #IndianStocks #TechnicalAnalysis #MomentumStocks #PriceAction #Trading #NIFTY #SENSEX #BANKNIFTY #FINSTRIVE
Free TG: https://t.co/XouZQJPBva
Innovation begins when we challenge what's possible. Our Director, Operations and Continuous manufacturing, Lalit Patil, shares how science-led thinking and engineering ingenuity help overcome complex process development challenges.
#sailifesciences #flowchemistry #chemistry
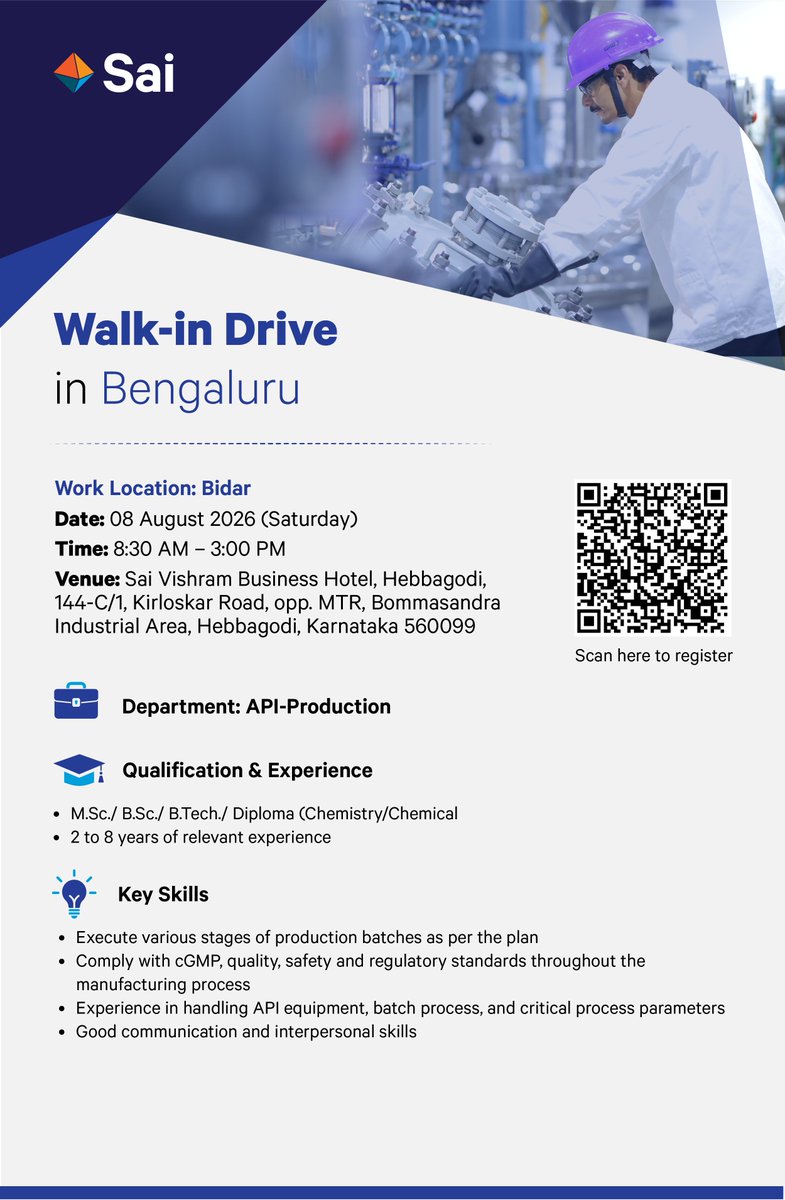
Sai Life Sciences, one of India’s leading CRDMO, will be conducting ‘Walk-in interviews’ on August 8, 2026, for API production roles. The interviews will be conducted at Sai Vishram Business Hotel, Hebbagodi, Karnataka.
Work Location: Bidar, Karnataka.
#sailifesciences
The strongest client relationships are shaped by shared experience. Our Associate Vice President & Head - Process Engineering, Suresh Naik Korra, shares how solving complex challenges together reinforces confidence and builds lasting trust.
#sailifesciences
Drug discovery is a team sport. Our vice president - medicinal chemistry, Santosh Kulkarni, shares why integrating expertise across disciplines is key to solving increasingly complex scientific challenges.
#sailifesciences #drugdiscovery #pharma #cro #crdmo #trust #medchem
Trust isn't built by having all the answers—it's built by asking the right questions.
Our Associate Vice President, P R&D, Ganesh Yaddanapudi shares why understanding the science behind a problem is the foundation of lasting client partnerships.
#sailifesciences #trust #client

Trust Small Cap Fund is investing in tomorrow's leaders, not yesterday's winners. 💰
✅ #NavinFluorine – Specialty chemicals & CDMO
✅ #SaiLifeSciences – Global CRDMO opportunity
✅ #SanseraEngineering – Auto, Aerospace & Defence manufacturing
✅ #MCX – Monopoly exchange with operating leverage
✅ #Polycab – India's power infrastructure & export champion
✅ #Shadowfax – Next-generation logistics platform
✅ #Lenskart – Omnichannel eyewear leader with strong brand moat
✅ #AtherEnergy – Premium EV ecosystem
✅ #AdityaInfotech – Electronic security & surveillance leader
✅ #AnandRathiWealth – Asset-light wealth management compounding machine
Common theme? 👇
📈 Financialisation
🏭 Manufacturing shift to India
⚡ Power & Data Centre capex
💊 Healthcare outsourcing
🚗 Premium mobility
📦 Logistics & e-commerce
🤖 Digital infrastructure
Today's small caps can become tomorrow's mid-cap and large-cap wealth creators.
That's where the biggest wealth is often created. 💎🚀
#MutualFunds #SmallCap #Investing

✨ I analysed the Top 5 holdings from three of the best-performing Small Cap Mutual Funds. 👇
Invesco India Small Cap:
✅ #BSE
✅ #AparIndustries
✅ #AmberEnterprises
✅ #SaiLifeSciences
✅ #TDPowerSystems
Nippon India Small Cap:
✅ #AparIndustries
✅ #BHEL
✅ #MCX
✅ #KarurVysyaBank
✅ #KirloskarOilEngines
Bandhan Small Cap:
✅ #VoltampTransformers
✅ #LTFoods
✅ #Sobha
✅ #REC
✅ #DataPatterns
These are businesses that could benefit from India's structural growth over the next 5–10 years across themes like capital goods, power, manufacturing, defence, financials, and real estate.
📌 Past returns attract investors. Future earnings create wealth.
Disclaimer: This is for educational purposes only and not investment advice. Please do your own research before investing.

✨I was analysing the top 5 stocks names from these three best-performing Small Cap Mutual Fund
Invesco India Small Cap
✅ #BSE
✅ #AparIndustries
✅ #AmberEnterprises
✅ #SaiLifeSciences
✅ #TDPowerSystems
Nippon India Small Cap
✅ #AparIndustries
✅ #BHEL
✅ #MCX
✅ #KarurVysyaBank
✅ #KirloskarOilEngines
Bandhan Small Cap
✅ #VoltampTransformers
✅ #LTFoods
✅ #Sobha
✅ #REC
✅ #DataPatterns
These are businesses that could benefit from India's structural growth over the next 5–10 years.
Past returns attract investors. Future earnings create wealth.
#MutualFunds #SmallCap #Investing #IndiaGrowth #GARP

ALL-TIME HIGH BREAKOUT ALERT📊
15 Stocks Closed at Fresh Lifetime Highs Today!
#TMB
#RubiMills
#BetaDrugs
#NitaGelatin
#PhoenixMills
#GoodluckIndia
#AfcomHoldings
#SaiLifeSciences
#GodrejIndustries
#TimexGroupIndia
#AnandRathiWealth
#SuvenLifeSciences
#BajajConsumerCare
#IndiaNipponElectricals
#NuvamaWealthManagement
✨I was analysing the top 5 stocks names from these three best-performing Small Cap Mutual Fund
Invesco India Small Cap
✅ #BSE
✅ #AparIndustries
✅ #AmberEnterprises
✅ #SaiLifeSciences
✅ #TDPowerSystems
Nippon India Small Cap
✅ #AparIndustries
✅ #BHEL
✅ #MCX
✅ #KarurVysyaBank
✅ #KirloskarOilEngines
Bandhan Small Cap
✅ #VoltampTransformers
✅ #LTFoods
✅ #Sobha
✅ #REC
✅ #DataPatterns
These are businesses that could benefit from India's structural growth over the next 5–10 years.
Past returns attract investors. Future earnings create wealth.
#MutualFunds #SmallCap #Investing #IndiaGrowth #GARP
First time in Gujarat!
This Saturday, Sai Life Sciences will be in Ankleshwar for a walk-in recruitment drive!
If you're an experienced API manufacturing professional, discover opportunities to grow your career with a global CRDMO.
#sailifesciences #production #pharmajobs


3. #SaiLifeSciences – Holding firmly after a breakout at 52-week/ATH levels, keep it on the watchlist.


#Sailifesciences #Sailife
Sai Life Sciences carries a valuation that most pure-play pharma manufacturers would blush at.
The market is pricing in a very specific bet: that discovery support — which today drags asset turns and compresses margins — will eventually lock in commercial manufacturing contracts that make the same asset base print far higher returns tomorrow.
It's a double-edged sword. The CRO front-end depresses asset turnover to ~1.1x (vs Neuland's 2.1x) while the molecule is still in trials. But if the molecule wins FDA approval, the same factory that looked inefficient suddenly runs multi-ton commercial orders at 30%+ EBITDA — with a switching cost that runs into ₹84-420 Crore and 24 months to change.
The question the market is paying a premium for: will enough molecules clear trials fast enough to justify what you're paying today?
Business story
The story starts with a simple frustration: pharma companies were losing years and millions handing molecules between discovery firms, development labs, and manufacturers.
Sai's answer — "Follow the Molecule." When a Big Pharma client needs to find a drug, Sai's scientists in Hyderabad, Boston, and Manchester help design it. When the molecule shows promise, Sai doesn't hand it off. It moves it down the hall to scale-up labs. When it clears trials, Sai makes it commercially at its Bidar facility.
Every step is sticky. The deeper the molecule progresses, the more expensive it becomes to switch.
The pivot that changed everything: vertical integration into Key Starting Materials (KSMs). By synthesising its own chemical building blocks in-house, Sai locked in 50-55% gross margins regardless of raw material shocks.
The growth trigger: 43 molecules now at commercial stage (7 added in the last 12 months alone). Plus 11 more in Phase-3/NDA pipeline. This is the funnel converting discovery drag into manufacturing annuity.
Moat:
Three pillars rated Strong:
① Regulatory lock-in. Once Sai's process chemistry is written into a client's NDA filing, switching vendors requires 12-24 months and ₹84-420 Crore in re-validation. Churn is structurally near-zero. 18 of the top 25 global pharma companies are clients — average vintage over 10 years.
② Compliance moat. Zero USFDA/PMDA/EMA warning letters across all facilities. This isn't a feature — it's the price of entry for a Big Pharma client's CMO list. Took a decade to earn. Cannot be bought.
③ Geopolitical tailwind. The Biosecure Act is actively redirecting global CRDMO pipelines away from Chinese giants (WuXi AppTec). Sai is the cleanest validated alternative with scale in India.
What's missing: no formal patents. Moat is process trade secrets + regulatory history. The real risk is sector-wide margin compression if Indian CDMO capacity oversupply triggers a price war on late-stage intermediates.
Valuation & operational leverage
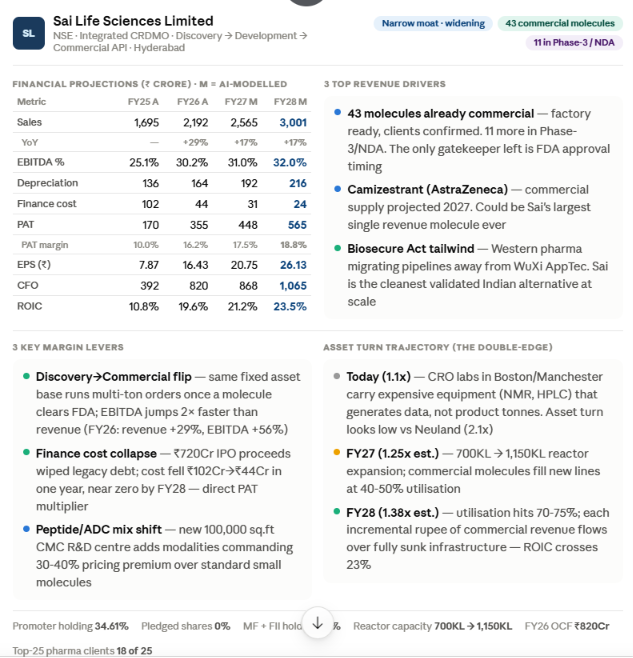
FY26 A: Rev ₹2,192Cr | EBITDA 30.2% | PAT ₹355Cr | EPS ₹16.43 | ROIC 19.6%
FY27 E: Rev ₹2,565Cr | EBITDA 31.0% | PAT ₹448Cr | EPS ₹20.75 | ROIC 21.2%
FY28 E: Rev ₹3,001Cr | EBITDA 32.0% | PAT ₹565Cr | EPS ₹26.13 | ROIC 23.5%
Is there big operational leverage? Enormous — and it's only starting. FY26 demonstrated it perfectly: revenue +29% but EBITDA +56%. That 2× outperformance is what happens when molecules cross into commercial phase and the fixed asset base starts running multi-ton orders without proportional cost additions.
The next unlock: asset turnover climbing from 1.15x → 1.38x by FY28 as 700 KL reactor capacity scales to 1,150 KL and utilisation hits 70-75%.
Growth triggers:
✅ 43 commercial molecules + 11 in Phase-3/NDA commercial by 2027
✅ ₹1,100-1,300Cr CapEx deploying HPAPI and peptide/ADC lines at 30-40% pricing premium
✅ Finance cost dropped from 6% → 2% of sales; near zero by FY28 — direct EPS multiplier
✅ Biosecure Act pipeline migration from WuXi — premium Western contracts at higher utilisation
Red flags:
⚠ Top 5 clients = 35% of revenue — one clinical failure dents utilisation significantly
⚠ Debtor days stretched to 77.6 days — global pharma credit cycles trap working capital
⚠ June 2026 lock-up expiry on 4.19Cr pre-IPO shares — potential technical overhang
⚠ ₹1,100-1,300Cr FY27 CapEx keeps FCF yield low despite strong OCF of ₹820Cr
Management quality & governance
Krishnam Raju Kanumuri (MD & CEO) steered the business from a regional contract provider to a partner for 18 of the top 25 global pharma giants.
The international bench is real: Dr. John Pavey (ex-AstraZeneca, Sr VP Process R&D) and Maneesh Pingle (EVP Discovery Services) anchor Western client relationships from Manchester and Boston.
Promoter holding: 34.61%. Zero pledged shares. Offset by 27.8% mutual fund and 21.17% FII/FPI holding — one of the strongest institutional validator profiles in Indian pharma.
Governance flags:
⚠ BSE/NSE warning letters (Jan 2026) for missing a mandatory Stakeholders' Relationship Committee meeting — minor, resolved, but signals a post-IPO compliance curve
⚠ Pre-IPO absorption of Sai Quest Syn required SEBI intensive look-through review
⚠ Pending IGST tax demand litigation — cash provision risk if ruled against
⚠ But: guided 28-30% EBITDA; delivered 30.15%. They walk what they talk.
Order pipeline — does it justify the valuation?
This is the central question for anyone paying a premium multiple today.
The visibility:
→ ~65% of CRO revenue locked in FTE frameworks (12-36 month contracts, recurring monthly billing — essentially annuity)
→ Commercial manufacturing (43 molecules) = multi-year supply agreements, non-cancellable without costly dossier re-filings
→ Pipeline upside: 11 Phase-3/NDA molecules, any one of which could materially shift the commercial manufacturing base
The growth story isn't about hope — it's about 11 named molecules already in late-stage trials. The risk isn't whether customers will buy. The risk is whether the drug clears FDA approval on time.
Closing thesis
To answer the earlier question: is the premium valuation for the discovery-to-commercial model actually justified?
Partially — and here's the nuanced answer.
The discovery drag on asset turns (1.1x vs Neuland's 2.1x) is real and structural. You are paying for future asset efficiency that isn't here yet. Every PhD scientist and NMR spectrometer in Boston that isn't generating commercial API volume today is a bet on what they're designing winning FDA approval tomorrow.
But the bet has a demonstrable payoff track record: Gepant migraine revenue went from ₹35 Crore to ₹133 Crore in one cycle. Gepotidacin is now a ₹143 Crore revenue line. Each commercial conversion transforms a low-asset-turn cost centre into a high-asset-turn manufacturing annuity — on the same physical infrastructure.
The valuation sustains IF:
✅ Camizestrant converts commercially in 2027 — single biggest near-term catalyst
✅ Reactors scale 700KL → 1,150KL on schedule; FATR inflects to 1.25x+ by FY28
✅ 3-4 of the 11 Phase-3 molecules clear regulatory hurdles through FY28
The valuation cracks IF:
⚠ Camizestrant hits a Phase-3 setback — removes the largest single forward revenue assumption
⚠ Indian CDMO peers trigger a price war — compresses the 30-32% EBITDA corridor
⚠ Biotech funding tightens — CRO revenue volatile quarter-to-quarter
[AI-modelled numbers for directional perspective only]
[Not an investment advice, DYOR]

All About Your Company
How is Sai Life Sciences shaping India's innovation-led pharma story?
CFO Sivaramakrishnan Chittor joins All About Your Company to discuss growth, global expansion and the CRDMO opportunity
#AllAboutYourCompany #SaiLifeSciences #Pharma @hershsayta


🚨 POWER & PHARMA Stocks Trading Near 52-Week Highs 🔥🔥
🔖 Bookmark It 📑
#GEPowerIndia
#GEVernovaTD
#AjantaPharma
#EmcurePharma
#ZydusLifesciences
#IpcaLaboratories
#CaplinPointLabs
#SaiLifeSciences
#RubiconResearch
👉Power is benefiting from India's massive transmission & grid capex cycle.
👉Pharma is riding exports, specialty drugs, CDMO opportunities, and margin expansion.
Leaders usually make new highs before they make headlines.
Disclaimer: DYOR ⚠️ - No buy sell Reco 🙏
#52WeekHigh #StocksToWatch #PowerSector #PharmaStocks #StockMarketIndia #Nifty #FinanceAct2026 #StockMarket @n_stox

Last Seen Hashtags on Sotwe
NUNESCORRUPTO
Seen from United States
ควยนักเรียน
Seen from Thailand
มอนอ
Seen from Thailand
Omegle
Seen from United Kingdom
NCP Maharashtra
Seen from Belgium
HILACHAS
Seen from United States
หลุดทวิต
Seen from Thailand
mfmthreesome
Seen from Netherlands
gooning
Seen from United States
editionspantheonassas
Seen from United States
Most Popular Users

Elon Musk 
@elonmusk
241.7M followers

Barack Obama
@barackobama
119M followers

Cristiano Ronaldo
@cristiano
114.3M followers

Donald J. Trump
@realdonaldtrump
111.9M followers

Narendra Modi
@narendramodi
107.2M followers

Rihanna
@rihanna
98.7M followers

NASA
@nasa
92.4M followers

Justin Bieber
@justinbieber
91.8M followers

KATY PERRY
@katyperry
89.9M followers

Taylor Swift
@taylorswift13
83.9M followers

Lady Gaga
@ladygaga
75.4M followers

Virat Kohli
@imvkohli
73.3M followers

Kim Kardashian
@kimkardashian
70.9M followers

YouTube
@youtube
68.8M followers

Neymar Jr
@neymarjr
66.3M followers

Bill Gates
@billgates
65.1M followers

Selena Gomez
@selenagomez
63M followers

The Ellen Show
@theellenshow
62.3M followers

CNN
@cnn
61.8M followers

X
@x
60.7M followers