

Top Tweets for #TriFusion

$MBLY — #TriFusion glass-box read | 2 September 2026
🟢 We broadly agree with Berenberg on the medium-term opportunity. We do not fully agree with the way the current dislocation is being explained.
Berenberg’s central thesis is credible: Mobileye remains strongly positioned in high-volume, cost-efficient ADAS, and the transition toward SuperVision, Chauffeur, Mobileye Drive and robotaxi commercialisation creates meaningful upside if those programs convert.
Where we challenge the analysis is the suggestion that the stock simply “overcorrected” because of Amnon Shashua’s departure.
🔴 The market did not sell Mobileye purely because the founder is stepping down.
The same period also brought a weaker near-term revenue picture. Q3 revenue guidance implied roughly a 5–6% YoY decline.
That matters because the central question around Mobileye is not technological credibility.
It is commercial conversion.
The market is effectively saying:
“Show us the revenue, not another design-win pipeline.”
Part of the discount is succession risk. But part of it is entirely rational.
🟠 We would also qualify the description of Q2 as simply “strong.”
Q2 revenue was approximately $508m, essentially flat year over year.
System volumes increased, but lower EyeQ pricing — particularly from China OEM export mix — offset some of that volume strength.
GAAP gross margin also moved lower, and adjusted gross margin declined.
So this was not a clean operating acceleration.
The headline adjusted operating result also requires a glass-box adjustment.
Mobileye reported roughly:
$155m adjusted operating income
and
31% adjusted operating margin
However, approximately $93m of first-half R&D incentive benefit was recognised in Q2, with the Q1 and Q2 economic portions described as roughly equal.
If we simply allocate half of that first-half benefit back to Q1 — Calculated, not reported — Q2 adjusted operating income falls to approximately:
$108.5m
or around:
21.4% adjusted operating margin
That is still a respectable result.
It simply means the headline 31% Q2 margin materially overstates the true sequential operating acceleration.
Important distinction:
The R&D incentive itself appears economically useful and potentially durable.
The issue is timing, not legitimacy.
🟢 Where Berenberg has a stronger argument is the product-cycle opportunity.
Mobileye remains one of the most credible scaled players in:
• Base ADAS
• L2/L2+
• Surround ADAS
• SuperVision
• Chauffeur
• Autonomous driving systems
• Robotaxi infrastructure
The company continues to win programs, and its strategic move toward higher-content platforms can increase economic value per vehicle.
That matters.
But the investment discipline remains:
Design win ≠ revenue
Launch ≠ economic conversion
Robotaxi opportunity ≠ proven robotaxi economics
This is the real battleground.
🟢 The balance sheet is one of the strongest parts of the argument.
Mobileye exited Q2 with roughly $1.4bn of cash and marketable securities and remains cash-generative.
This is not a distressed autonomy company trying to finance its way toward relevance.
Mobileye has time.
That is a major difference.
The market is pricing a trust problem, not a solvency problem.
And that is precisely why there may eventually be asymmetry here.
📊 Now look at the chart.
At approximately $8.36, our current daily chart has Mobileye below every major daily EMA:
EMA 9: $8.61
EMA 21: $8.68
EMA 50: $8.79
EMA 100: $8.98
EMA 200: $9.88
The stock is compressing.
The structure is becoming more interesting.
But:
Cheap is not the same as technically repaired.
Our current technical classification remains:
🟠 BUILDING / COMPROMISED — NOT ACTIVATED
The immediate technical job is to reclaim approximately:
$8.60–$9.00
Then the more important repair sequence begins.
Higher structural gates remain around:
$10.25
and then:
$11.26
So Berenberg’s $11 target is not unreasonable from $8.36.
But technically, the stock still has to earn it.
🔎 The share-forensics layer adds another dimension that standard analyst commentary often misses.
Mobileye has roughly:
850.2m total common shares
But that is not the tradable float.
The current Class A denominator is approximately:
252.4m shares
Intel controls:
597.8m Class B shares
plus approximately:
50m Class A shares
and retains roughly:
96.9% of the voting power
After adjusting for Intel and other constrained Class A supply, our forensic working float is approximately:
167.5m–178.8m shares
Latest reported short interest is approximately:
37.34m shares
That puts short interest at roughly:
21–22% of a credible Class A float
That is meaningful.
🟠 But it is not a clean squeeze setup.
Borrow has recently been extremely cheap — around 0.28–0.30% — with millions of shares available.
So shorts are substantial.
They are not structurally trapped.
Our glass-box conclusion is:
MBLY can move because a meaningful short position sits against a much smaller effective Class A pool than the headline share count suggests — not because the float is genuinely scarce.
That distinction matters.
🔴 There is also future-paper friction.
Mobileye’s denominator has been expanding.
The principal factors include:
• Mentee-related stock issuance
• Employee stock compensation
• Large RSU awards
• Future restricted-stock release
• Potential future Intel Class B conversion into Class A
The buyback helps.
But so far it is better described as:
dilution mitigation
rather than:
true denominator compression
This matters because you can be right about the company and still get weaker-than-expected per-share torque if the Class A denominator continues expanding.
⚖️ So where do we land versus Berenberg?
🟢 What Berenberg is right about:
• Mobileye may be materially undervalued if advanced programs convert.
• The underlying ADAS / edge-AI lane remains strategically strong.
• Higher-content L2/L2+ systems can materially improve economics.
• The balance sheet gives the company time.
• The selloff has improved asymmetry.
🟠 Where we think the argument needs more discipline:
• The selloff was not purely a CEO-transition overreaction.
• Q3 guidance gave investors a legitimate reason to remain cautious.
• Q2 revenue itself was essentially flat.
• Q2 margin optics were materially helped by first-half incentive recognition.
• China mix is pressuring ASP and margins.
• Advanced autonomy still needs to convert into reported revenue.
• The primary trend remains unrepaired.
• Short interest is meaningful, but borrowing remains easy.
• SBC and future Class A supply deserve much more attention.
🎯 TriFusion conclusion — 2 September 2026
We agree that $MBLY may be mispriced.
We do not think it has yet demonstrated that it is mispriced.
Fundamentally, the company is considerably healthier than the chart suggests.
Thematically, Mobileye remains positioned in a strong ADAS / edge-AI / autonomy lane.
The balance sheet substantially reduces existential risk.
But the market’s scepticism is not irrational.
Revenue conversion remains incomplete.
Succession remains unresolved.
China economics are softer.
The share structure carries future-paper friction.
And price remains below every major daily moving average.
Our current state remains:
🟢 Fundamentals: strong enough to survive and execute
🟢 Thematics: strong
🟠 Market perception: probably too pessimistic, but partly justified
🟠 Share structure: usable, not clean
🟠 Technical state: building, not activated
🟠 CORE: Hold / Watchlist
🟠 TACTICAL: Speculative Buy Candidate
Bottom line:
Berenberg may ultimately be right on the destination.
We simply think the market still requires proof on the journey.
The balance sheet buys Mobileye time.
The product cycle creates the opportunity.
Revenue conversion earns the rerating.
And price confirmation tells us when the market finally believes it. #swazcharts #Nasdaq

Our $TASK prediction continues to move bullishly; it's currently 31% 🆙 in the last few weeks. Yet another winner we shared out of the goodness of our hearts😍📉🚀🤑 https://t.co/HTMSKZHEaa #Nasdaq #TriFusion #swazcharts #trading #NYSE #stockmarkets #TASKUS #AI #AGI
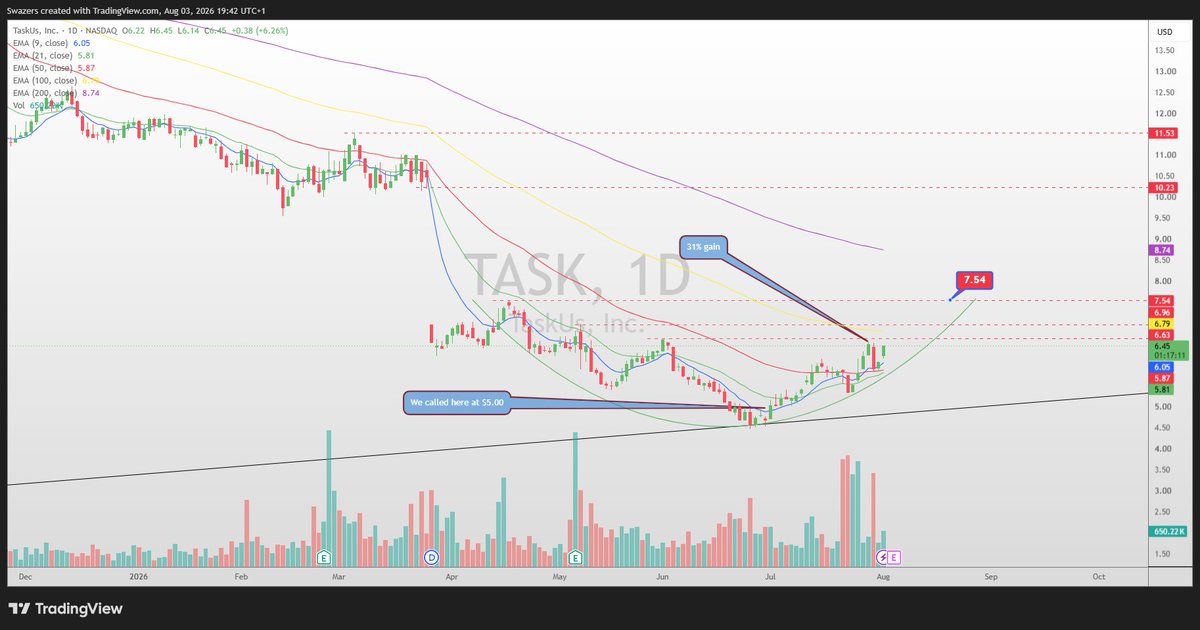
$TASK — this is exactly the kind of messy and misunderstood setup we look for🧐🔎
Not clean. Not obvious. Not widely discussed. A prime Hidden Gem💎
But potentially very mispriced🧩
Here’s the story in plain English👇
Last year, TaskUs had a proposed take-private deal at $16.50 per share.
The deal did NOT go through.
Minority / unaffiliated shareholders pushed back. Some clearly believed $16.50 did not reflect the true value of the company.
Then, a few months later, TaskUs refinanced and paid a huge $3.65 per share special dividend.
That is a massive dividend relative to where the stock trades today.
And this is where we think most people misunderstand the chart.
When a company pays a large cash dividend, the share price mechanically adjusts lower because that cash has left the company.
So the chart suddenly looks a little ugly.
But part of that ugliness is not normal selling pressure.
Part of it is corporate-action mechanics.
💥 Failed $16.50 take-private
💥 Minority holders resisted the value
💥 The company stayed public
💥 $3.65 special dividend paid
💥 Chart mechanically reset lower
💥 Market now sees a damaged $5 stock
But is it actually broken?
That’s the question.
Because underneath the messy chart, TaskUs still has a real operating business.
This is not some zero-revenue concept stock.
TaskUs generates cash.
TaskUs has real clients.
TaskUs sits in digital operations, trust & safety, AI support, model training, data workflows, and human-in-the-loop infrastructure.
And the #AI Services segment has been growing at 30%+ year on year. Q1 itself came in at 36.1% YoY growth for AI Services. The AI services grew for the last 6 quarters in a row📉🚀
That matters.
So we ask:
Why was someone willing to take this private at $16.50?
Why did minority holders resist?
Why pay out a $3.65 special dividend afterwards?
Why is there almost no public conversation about it now?
To us, this does not look like a simple “stock went down, therefore bad” situation.
It looks like a failed-buyout / dividend-recap aftermath trade.
A strange special situation where the public market may be looking at the wrong thing.
The market sees:
📉 Damaged chart
📉 More leverage
📉 Controlled governance
📉 Small-cap neglect
But the other side of the ledger is:
📈 Prior $16.50 take-private reference
📈 $3.65 cash dividend already paid
📈 AI Services compounding 30%+
📈 Cash-generative business
📈 Tight-ish Class A float
📈 Very low social/media coverage
📈 Potential chart distortion from the dividend
This is why we think $TASK is interesting.
Not because it is perfect.
It is not.
There are still real risks:
⚠️ Debt increased after the dividend
⚠️ Governance is controlled
⚠️ The share structure is messy
⚠️ Future paper/overhang exists
⚠️ The technical chart still needs repair
⚠️ AI growth has to keep showing up
But this is exactly where hidden gems can live.
Not in clean, obvious, beautifully marketed stories.
In messy situations, where most people stop reading before they understand what actually happened.
Our view:
$TASK is not just a beaten-down BPO stock.
It may be a misunderstood corporate-action special situation with #AIservices growth hiding underneath a mechanically damaged post-dividend chart.
The simple version:
They tried to take it private at $16.50.
The deal failed.
They paid out $3.65.
The chart reset lower.
The market moved on.
The AI business kept growing.
Now the stock is sitting near the lows, barely discussed, with the next earnings update likely to tell us whether the AI Services growth story is still alive.
That is the setup.🧐📊
Research only. Not financial advice. #swazcharts #TriFusionAI #Nasdaq #NYSE #Tradingview #AI #TASK #stocks #markets #TradingStrategy #TaskUSinc #TaskUs https://t.co/wFL8aQwcUT


Last Seen Hashtags on Sotwe
Most Popular Users

Elon Musk 
@elonmusk
241.5M followers

Barack Obama
@barackobama
118.8M followers

Cristiano Ronaldo
@cristiano
114.5M followers

Donald J. Trump
@realdonaldtrump
111.9M followers

Narendra Modi
@narendramodi
107.1M followers

Rihanna
@rihanna
98.7M followers

NASA
@nasa
92.3M followers

Justin Bieber
@justinbieber
91.8M followers

KATY PERRY
@katyperry
90M followers

Taylor Swift
@taylorswift13
84M followers

Lady Gaga
@ladygaga
75.5M followers

Virat Kohli
@imvkohli
73.4M followers

Kim Kardashian
@kimkardashian
70.8M followers

YouTube
@youtube
68.7M followers

Neymar Jr
@neymarjr
66.4M followers

Bill Gates
@billgates
65.2M followers

Selena Gomez
@selenagomez
63.1M followers

The Ellen Show
@theellenshow
62.2M followers

CNN
@cnn
61.7M followers

X
@x
60.7M followers