

Top Tweets for #ZAPPFRESH

Any issues with #zappfresh DSM Fresh Foods?
Any governance concerns?
Can't understand the continous fall!

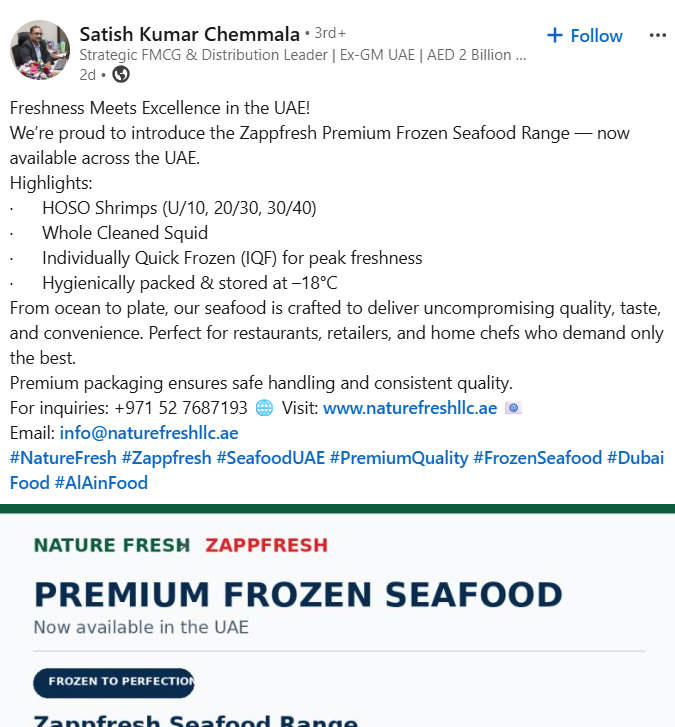

#Zappfresh
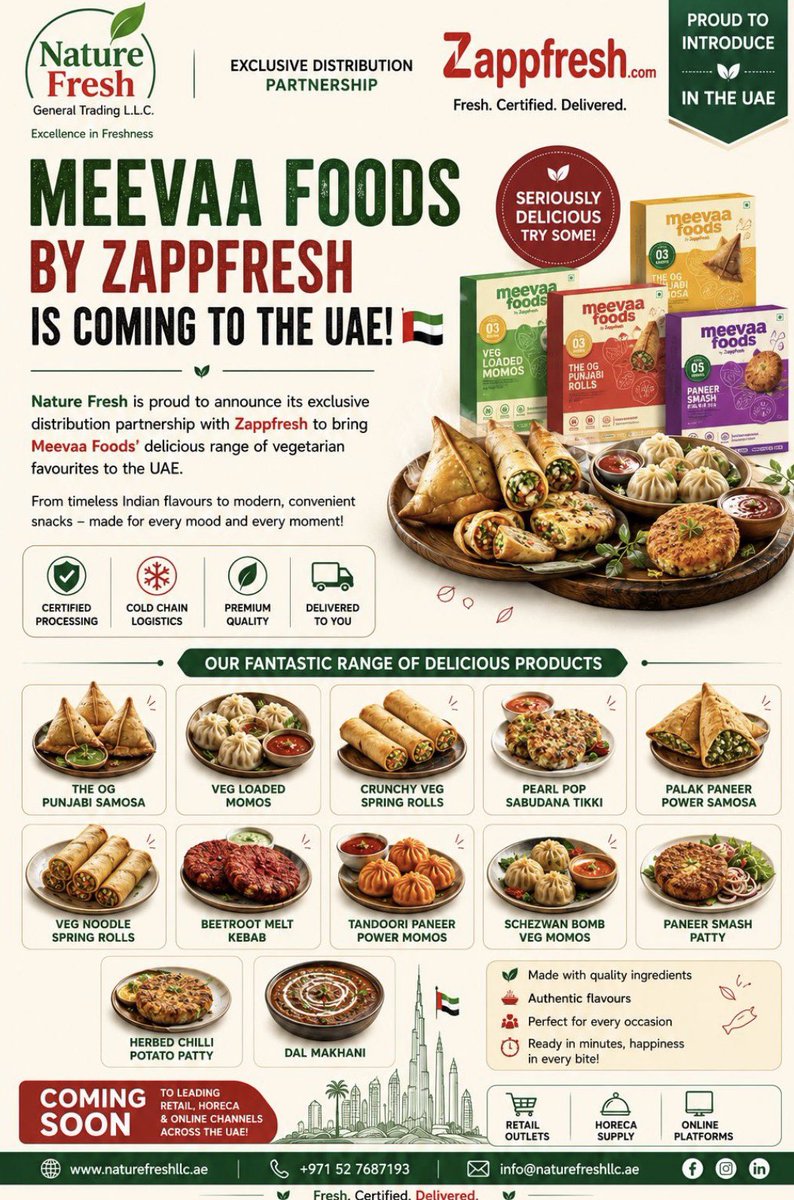
Meevaa Foods enters the UAE via an exclusive distribution tie-up with Nature Fresh General Trading, covering retail, HoReCa and online channels.
Why it matters: frozen/RTE vegetarian is the higher-margin end of the portfolio vs. the core fresh-protein business. Export mix shifting up is the stated route to the 18–20% EBITDA target by FY28.
Recent Performance:
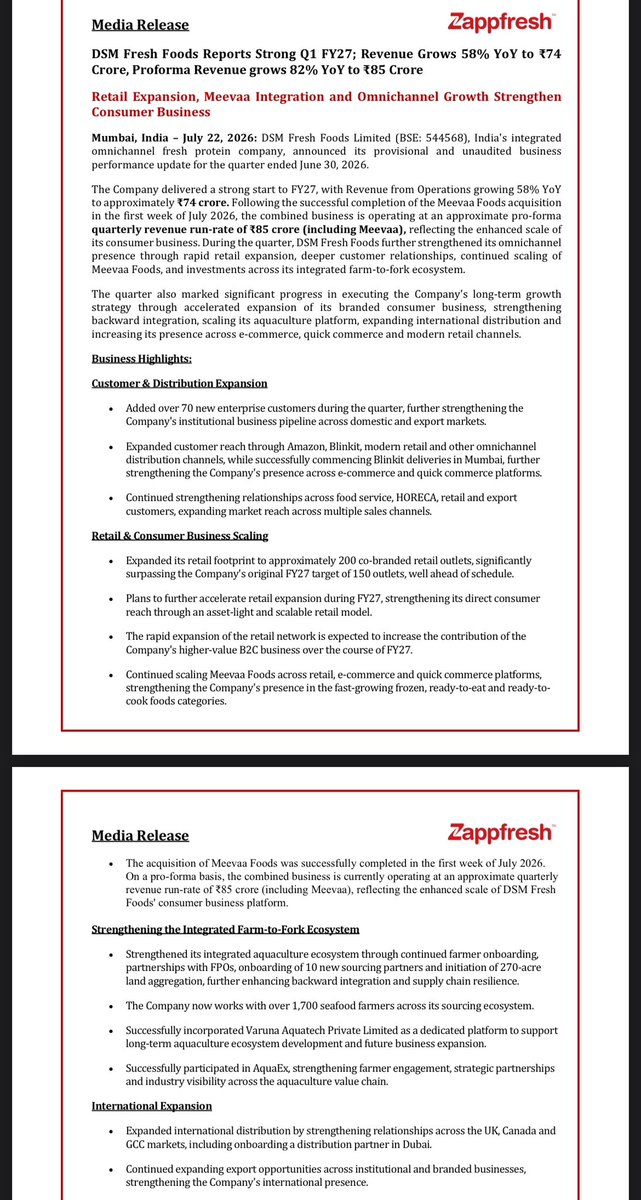
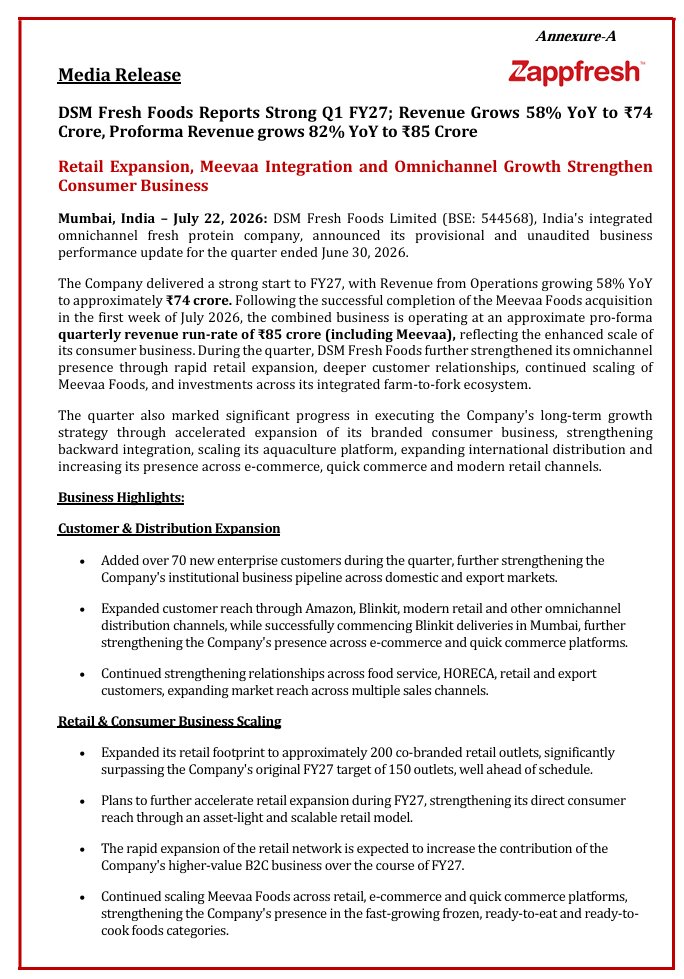
• Q1 FY27 revenue ~₹74cr, +58% YoY (₹85cr proforma incl. Meevaa)
• Retail footprint ~200 co-branded outlets vs. FY27 target of 150
• Meevaa acquisition closed; Chandigarh capacity in place
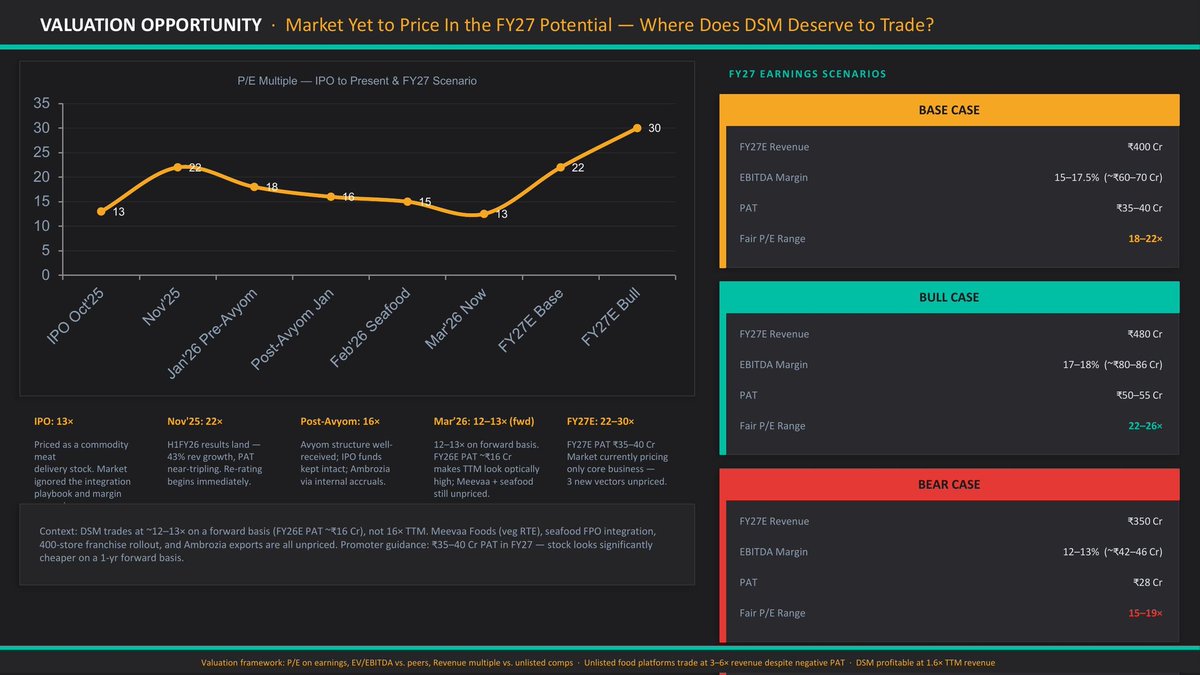
The honest risk: FY26 operating cash flow was deeply negative despite reported PAT. Receivables and advances have expanded materially.
So this is an execution bet, not a story bet. Price action has been against it. What would change the picture is H2 delivering EBITDA margin expansion with operating cash flow turning margins alone won't do it.
Invested, so read me as biased. Not a recommendation.
DSM Fresh Foods (Zappfresh) - Promoter @DeeepManchanda after seeing the share price at Rs. 70 from Rs 200 odd even after delivering profit @zappfresh #dsmfreshfoods #SME #sme #zappfresh


3/
Now the number in every headline 🧮
Post Meevaa, the combined business runs at a pro forma quarterly rate of about ₹85 cr, an 82% YoY figure.
Useful for scale, but it is pro forma, not reported Q1. Keeping the two apart is the whole point.
#ZappfreshResults #Zappfresh
1/
A meat brand grew revenue 58% last quarter 🔍 and the number everyone's quoting isn't even the one that did it.
The acquisition that doubled its run-rate closed AFTER the quarter ended.
So what actually drove the ₹74 cr? Thread🧵 👇
#ZappfreshResults #Zappfresh

Zappfresh /DSM Fresh Foods Q1FY27 Update
➡️ Q1FY27 Rev: INR 74 CR, approx 60% y/y growth & quarterly runrate of INR 85 CR, broadly on track to do INR 350 CR, broadly in line with my estimates for FY27~
➡️ Distribution network expansion - 70 new ent customers, offering cost-efficient rev visibility.
➡️ Zappfresh has further scaled its retail expansion to 200 cobranded stores, and I strongly feel that meat retail has to be an omnichannel play to ensure sustainable scalability.
➡️ Growing share of omnichannel play + Meeva expansion should ensure cash flow concerns + margin expansion.
➡️ Detailed business breakdown and valuation theses in the thread below.
Disc: post is purely for educational purposes, not a buy-sell, please do your own due-diligence and I am not a sebi registered analyst.
#zappfresh #DSMFreshfoods #dsm


@nileshkurhade One more good thing ZAPPFRESH could have done and reported: "We found our digital marketing firm was engaged in malpractice of posting fake reviews and we have terminated the contract" . That will give an extra 10% UC to the stock! @Zappfresh @DeeepManchanda

Press Release / Media Release
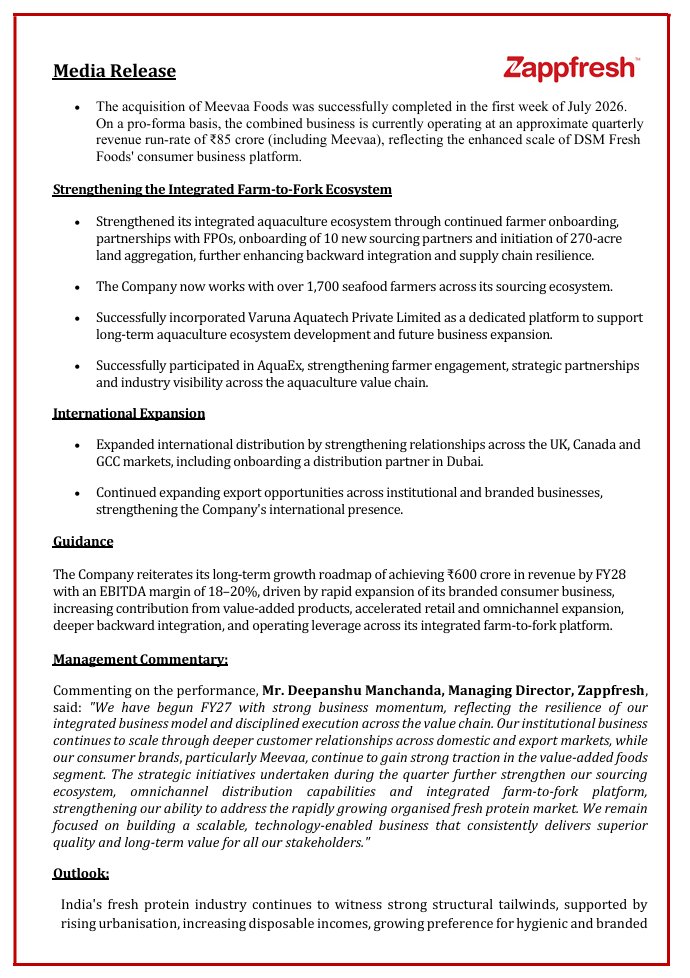
Q1 FY27 revenue rose 58% YoY to ₹74 crore, Meevaa acquisition completed, 200 outlets added.
#DSMFreshFoods #Zappfresh #SmallCapStocks #ConsumerStory #FoodTech #D2CIndia #FarmToFork #IndiaConsumptionStory #LongTermInvesting #MultibaggerPotential

DSM Fresh Foods Ltd 🥗
Building a footprint in India’s growing fresh food & processing ecosystem. A business to watch as the food consumption story evolves.
#DSMFreshFoods #multibagger #IndianStocks #SMEStocks #Microcap #Investing #Nifty #IPO


#Zappfresh | This is no longer just a fresh meat delivery company. It's quietly building an integrated consumer food platform.
DSM Fresh Foods (Zappfresh) has released a strong Q1 FY27 business update, and while the headline 58% YoY revenue growth grabs attention, the bigger story is the quality of growth.
Q1 Highlights
- Revenue from Operations: ~₹74 crore (+58% YoY)
- Pro-forma quarterly revenue of ~₹85 crore after integrating Meevaa Foods (+82% YoY including the acquisition).
- Successfully completed the Meevaa Foods acquisition, strengthening its presence in frozen, ready-to-cook and ready-to-eat foods.
But revenue growth is only one part of the story.
The real transformation is happening underneath.
1. The business model is moving up the value chain.
Historically, Zappfresh was largely known for fresh protein. Today, management is deliberately expanding into higher-margin branded food products.
Meevaa gives the company exposure to:
- Frozen foods
- Ready-to-Cook
- Ready-to-Eat
These categories typically enjoy better margins, stronger customer loyalty and greater pricing power than fresh commodity products.
That's an important evolution.
2. Retail expansion has exceeded expectations.
The company has already expanded to ~200 co-branded retail outlets, comfortably surpassing its original FY27 target of 150 stores—well ahead of schedule. Even more interesting...
Management plans to continue expanding aggressively during FY27 using an asset-light retail model.
3. Omnichannel execution is becoming a competitive advantage.
Instead of relying on one channel, Zappfresh is building distribution everywhere consumers buy food.
The company continues expanding across:
- Amazon
- Blinkit
- Modern Retail
- Food Service
- HORECA
- Export Markets
It also started Blinkit deliveries in Mumbai, expanding its quick-commerce footprint.
Consumers increasingly expect food within minutes—not days. Being present across every major channel significantly increases customer reach.
4. They're strengthening the business from the source.
One of the most underrated parts of this update is backward integration.
The company now:
- Works with 1,700+ seafood farmers
- Added 10 new sourcing partners
- Started 270-acre land aggregation
- Incorporated Varuna Aquatech Pvt Ltd to strengthen its aquaculture ecosystem.
Why is this important?
Owning more of the supply chain can improve:
- Product quality, Supply reliability, Cost control, Margins, Scalability
In food businesses, sourcing is often the biggest competitive advantage.
5. International expansion is quietly accelerating.
The company strengthened distribution across UK, Canada, GCC
Including onboarding a new distribution partner in Dubai.
Exports remain a relatively small contributor today, but they expand the addressable market beyond India.
The management's long-term ambition is bold.
The company has reiterated its roadmap of reaching:
- ₹600 crore revenue by FY28
- 18–20% EBITDA margins
Those are ambitious targets and will require flawless execution.
Investors should treat them as management aspirations—not guarantees.
Instead of simply selling fresh protein, Zappfresh is attempting to build an integrated farm-to-fork food ecosystem, where it controls sourcing, processing, branding, distribution and customer relationships.
If executed well, this can improve not just revenue growth, but also margins, cash generation and return on capital over time.
Key monitorables going forward:
- Successful integration of Meevaa Foods.
- Growth in higher-margin branded products.
- Same-store productivity of the expanding retail network.
- Progress toward the ₹600 crore FY28 revenue target.
- Margin expansion toward the guided 18–20% EBITDA range.
For long-term investors, the story is evolving from "a fresh meat company" to "an integrated branded food platform."
Execution over the next few years will determine whether that transformation translates into lasting shareholder value.
#Zappfresh #DSMFreshFoods #Meevaa #FoodTech #QuickCommerce #Retail #ConsumerBusiness #SmallCaps #IndianStockMarket #FundamentalAnalysis #LongTermInvesting


Zappfresh /DSM Fresh Foods Q1FY27 Update
➡️ Q1FY27 Rev: INR 74 CR, approx 60% y/y growth & quarterly runrate of INR 85 CR, broadly on track to do INR 350 CR, broadly in line with my estimates for FY27~
➡️ Distribution network expansion - 70 new ent customers, offering cost-efficient rev visibility.
➡️ Zappfresh has further scaled its retail expansion to 200 cobranded stores, and I strongly feel that meat retail has to be an omnichannel play to ensure sustainable scalability.
➡️ Growing share of omnichannel play + Meeva expansion should ensure cash flow concerns + margin expansion.
➡️ Detailed business breakdown and valuation theses in the thread below.
Disc: post is purely for educational purposes, not a buy-sell, please do your own due-diligence and I am not a sebi registered analyst.
#zappfresh #DSMFreshfoods #dsm


#Zappfresh
DSM Fresh foods
Last week promoters bought 73,200 shares
Today, they bought another chunk of 52,800 shares

#Zappfresh
Company is working aggressively on the value chain
I am just waiting for their quarterly business update and in particular, distribution channel to reach 300 levels as mentioned in the earnings call.

#Zappfresh
Pan-India Reach through Amazon India Launch

#Zappfresh
Pan-India Reach through Amazon India Launch

#ZAPPFRESH
DSM Fresh Foods Ltd | Earnings Call Summary (Extract) - Mar-2026 Qtr | Disc: AI generated, please verify
Management Guidance and Outlook
■ Revenue Guidance: The company is targeting aggressive revenue growth of 70-80% for FY27. This growth is expected to be driven by scaling the B2B business, increasing contribution from the newly launched 'Meeva Foods', expansion of HORECA relationships, and deeper penetration in the seafood and value-added categories.
■ Profitability Guidance: Management expects a significant improvement in profitability and operating leverage. EBITDA margins are projected to improve by 3-4% over the next two years, driven by the higher-margin 'Meeva' and seafood businesses. The bottom line is also expected to benefit from the absence of deferred tax adjustments that impacted FY26 profits.
■ Geographic Expansion: The company plans to expand its presence further in the West and South of India, with Pune, Nasik, and markets near Bangalore on the radar for new launches.
■ Category Mix Outlook: For FY27, the projected revenue contribution by category is: Chicken (40-45%), Seafood (30-35%), and Meeva Foods (15-20%), with the share of mutton expected to reduce.
■ Strategic Priorities: Key priorities for FY27 include deepening leadership in existing markets, scaling the offline retail presence to 300-400 stores, strengthening backward integration in seafood, and improving automation and technology capabilities to build a scalable omnichannel platform.
I saw many posts yesterday that their portfolio is not affected at all and despite it increased so much!!!
Congratulations and I am happy for you!!!
But My portfolio was bad to be frank yesterday due to companies like #Afcom #Zappfresh #Jublingrea
Some good companies #Influxhealthtech #marineelectricals #Anondita #Kwalitypharma #HBLEngine #Syrma and many trying to hold back but couldn't be able to help much.
Still, I am happy because I wasn't planned to exit any company in my holdings.
Ups and Downs in the market are absolutely normal and quite natural.

#SME #Zappfresh #DSM #DSMFreshFoods
Update to DSM Fresh Foods (Zappfresh) H2 FY26 Earnings Concall Highlights
👉 FY27 & Future Outlook
💠EBITDA margin target: Improvement of 3-4% over the next 2 years.
💠Fish/Seafood category share expected to rise from 27% to at least 30-35%.
💠Chicken share expected to moderate to 40-45%
💠Promoter stake increase: Deepanshu Manchanda confirmed he will be exercising warrants very soon to increase equity stake (lock-in period post-IPO now over).
👉 Meeva Foods
💠Current annualised run rate: ₹30-40 Cr (post-acquisition, more than doubled from pre-acquisition peak of ₹16 Cr).
💠Expected contribution in FY27: At least ₹70 Cr (or more).
💠EBITDA margin for Meeva: ~20% (potentially slightly higher).
💠 Installed capacity: ₹500 Cr annual revenue potential.
💠90% of current Meeva business is exports (US, Canada, Europe).
👉 Retail Partner Stores:
💠Each partner store contributes on average ₹5 lakh revenue per month.
💠Net margin from each store: 8-10%
👉 Other Points:
💠 B2C customer retention rate: ~85%.
💠Cash & Liquidity: Current cash balance ₹20-25 Cr; Net Debt/Equity ratio now below 0.5x.
💠Positive operating cash flow expected in 2-3 years (currently negative due to growth-related working capital investment)

#SME #Zappfresh #DSM #DSMFreshFoods
DSM Fresh Foods (Zappfresh) H2 FY26 Earnings Concall Highlights
👉 FY27 & Future Outlook:
▫️ Revenue growth targeted at 70-80% for FY27
💠Driven by simultaneous scaling across core Zappfresh operations, HORECA expansion, deeper fish/seafood penetration, value-added categories, and new initiatives.
💠 Meeva Foods (frozen RTE/RTC brand) expected to contribute 15-20% of overall revenues in FY27 while strengthening higher-margin value-added portfolio.
💠 Organic Zappfresh growth (including seafood integration and HORECA) to remain the primary driver;
💠Meeva to add meaningful incremental contribution
💠No specific large new acquisition quantified yet, though adjacent category opportunities are under active evaluation for cross-selling and wallet share expansion.
💠 B2B:B2C mix expected to stabilise around 50:50 going forward (currently 68:32 in FY26) as retail meat-shop partnerships scale.
💠 Margin profile set to improve meaningfully (~20-25% overall uplift anticipated) through higher-margin Meeva products, controlled seafood sourcing via backward integration, better capacity utilisation
▫️ Deferred Tax Note:
💠FY26 PAT impacted by one-time deferred tax adjustment; normalised earnings better reflect underlying strength.
💠Going forward, expect normal corporate tax rate (~25%) with no further one-time impacts highlighted.
▫️ Long-term ambition: Evolve from leading fresh protein platform into one of India’s most trusted omnichannel food brands, with continued focus on profitability alongside scale.
👉 Strategic Projects, Expansions & Growth Pipeline:
▫️ Retail Meat-Shop Partnership Initiative:
💠Pilot (15-20 stores) delivered strong customer engagement and operational integration.
💠Already onboarded/signed ~100 stores; targeting 300-400 partner stores by year-end for hyper-local B2C expansion and modernising neighbourhood retail.
💠 This will meaningfully boost B2C contribution and brand visibility.
▫️ Seafood Backward Integration:
💠Partnerships with nearly 300 seafood farmers under FPO model + development of integrated aquaculture platform across ~270 acres (estimated ~500 tonnes annual capacity).
💠Expected to drive sourcing reliability, traceability, quality, and significant long-term margin improvement in the fast-growing seafood category (27% of FY26 revenue, up from 21% in H1).
▫️ Meeva Foods Launch: Strong initial traction with over 5,000 orders within 48 hours in Delhi-NCR; marks entry into broader convenience/value-added frozen foods segment.
▫️ HORECA/B2B Pipeline:
💠Currently servicing >300 restaurants & institutional customers; B2B channel now at 68% of revenue, providing strong scale, visibility, and capacity utilisation.
▫️ Additional adjacent food verticals under evaluation for cross-selling and platform expansion.
👉 Other Notable Points:
▫️ FY26 Consolidated Performance:
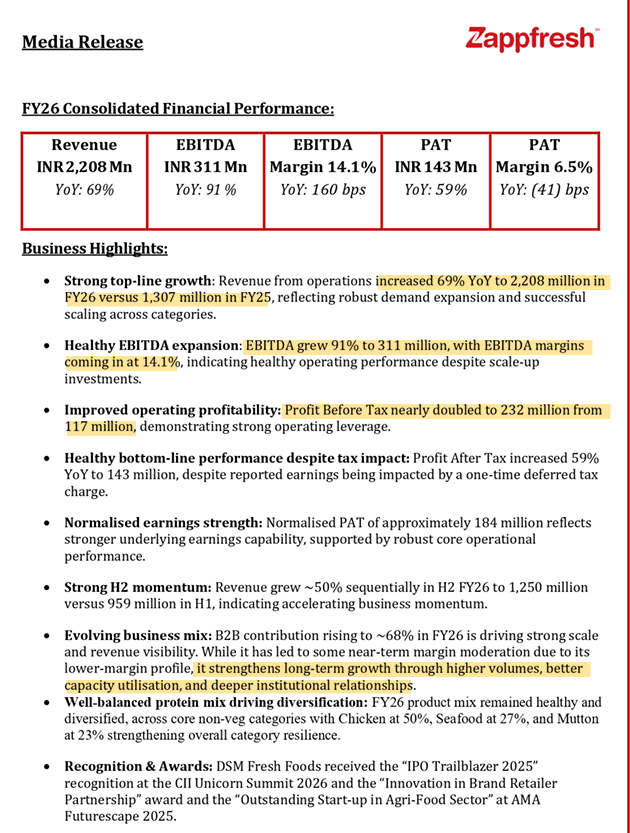
- Revenue: ₹2,208 Mn (+69% YoY)
- EBITDA: ₹311 Mn (+91% YoY), margin 14.1% (+160 bps)
- PAT: ₹143 Mn (+59% YoY), margin 6.5%; normalised PAT ~₹184 Mn
- H2 FY26: Revenue ₹1,250 Mn (~100% YoY / ~50% sequential growth), EBITDA ₹15.9 Cr (+42% YoY).
- PBT nearly doubled to ₹23.2 Cr.
💠 Well-balanced protein mix: Chicken ~50%, Seafood 27%, Mutton 23%.
💠 B2C monthly transacting users currently 80-90k.
▫️ Key Strategic Highlights:
💠Acquisition of Ambrozia RTE business via Avyom Foodtech strengthened vegetarian portfolio and export-ready manufacturing.
💠Leadership recognitions, IPO Trailblazer award, and Deepanshu Manchanda’s appointment as Goodwill Ambassador for UN SDGs.
💠Ongoing CSR via Beti Foundation (nutrition, women empowerment).
▫️ Emphasis on sustainable, profitable growth — scale and operating leverage now moving in tandem after years of patient building of the integrated farm-to-fork model
#SME #Zappfresh #DSM #DSMFreshFoods
DSM Fresh Foods (Zappfresh) H2 FY26 Earnings Concall Highlights
👉 FY27 & Future Outlook:
▫️ Revenue growth targeted at 70-80% for FY27
💠Driven by simultaneous scaling across core Zappfresh operations, HORECA expansion, deeper fish/seafood penetration, value-added categories, and new initiatives.
💠 Meeva Foods (frozen RTE/RTC brand) expected to contribute 15-20% of overall revenues in FY27 while strengthening higher-margin value-added portfolio.
💠 Organic Zappfresh growth (including seafood integration and HORECA) to remain the primary driver;
💠Meeva to add meaningful incremental contribution
💠No specific large new acquisition quantified yet, though adjacent category opportunities are under active evaluation for cross-selling and wallet share expansion.
💠 B2B:B2C mix expected to stabilise around 50:50 going forward (currently 68:32 in FY26) as retail meat-shop partnerships scale.
💠 Margin profile set to improve meaningfully (~20-25% overall uplift anticipated) through higher-margin Meeva products, controlled seafood sourcing via backward integration, better capacity utilisation
▫️ Deferred Tax Note:
💠FY26 PAT impacted by one-time deferred tax adjustment; normalised earnings better reflect underlying strength.
💠Going forward, expect normal corporate tax rate (~25%) with no further one-time impacts highlighted.
▫️ Long-term ambition: Evolve from leading fresh protein platform into one of India’s most trusted omnichannel food brands, with continued focus on profitability alongside scale.
👉 Strategic Projects, Expansions & Growth Pipeline:
▫️ Retail Meat-Shop Partnership Initiative:
💠Pilot (15-20 stores) delivered strong customer engagement and operational integration.
💠Already onboarded/signed ~100 stores; targeting 300-400 partner stores by year-end for hyper-local B2C expansion and modernising neighbourhood retail.
💠 This will meaningfully boost B2C contribution and brand visibility.
▫️ Seafood Backward Integration:
💠Partnerships with nearly 300 seafood farmers under FPO model + development of integrated aquaculture platform across ~270 acres (estimated ~500 tonnes annual capacity).
💠Expected to drive sourcing reliability, traceability, quality, and significant long-term margin improvement in the fast-growing seafood category (27% of FY26 revenue, up from 21% in H1).
▫️ Meeva Foods Launch: Strong initial traction with over 5,000 orders within 48 hours in Delhi-NCR; marks entry into broader convenience/value-added frozen foods segment.
▫️ HORECA/B2B Pipeline:
💠Currently servicing >300 restaurants & institutional customers; B2B channel now at 68% of revenue, providing strong scale, visibility, and capacity utilisation.
▫️ Additional adjacent food verticals under evaluation for cross-selling and platform expansion.
👉 Other Notable Points:
▫️ FY26 Consolidated Performance:
- Revenue: ₹2,208 Mn (+69% YoY)
- EBITDA: ₹311 Mn (+91% YoY), margin 14.1% (+160 bps)
- PAT: ₹143 Mn (+59% YoY), margin 6.5%; normalised PAT ~₹184 Mn
- H2 FY26: Revenue ₹1,250 Mn (~100% YoY / ~50% sequential growth), EBITDA ₹15.9 Cr (+42% YoY).
- PBT nearly doubled to ₹23.2 Cr.
💠 Well-balanced protein mix: Chicken ~50%, Seafood 27%, Mutton 23%.
💠 B2C monthly transacting users currently 80-90k.
▫️ Key Strategic Highlights:
💠Acquisition of Ambrozia RTE business via Avyom Foodtech strengthened vegetarian portfolio and export-ready manufacturing.
💠Leadership recognitions, IPO Trailblazer award, and Deepanshu Manchanda’s appointment as Goodwill Ambassador for UN SDGs.
💠Ongoing CSR via Beti Foundation (nutrition, women empowerment).
▫️ Emphasis on sustainable, profitable growth — scale and operating leverage now moving in tandem after years of patient building of the integrated farm-to-fork model
👉Mainboard stocks often get all the attention but some of the most compelling businesses are hiding in plain sight — on the SME Platform.
👉Smaller. Less covered, though noisy at times. Yet occasionally, genuinely exceptional.
———
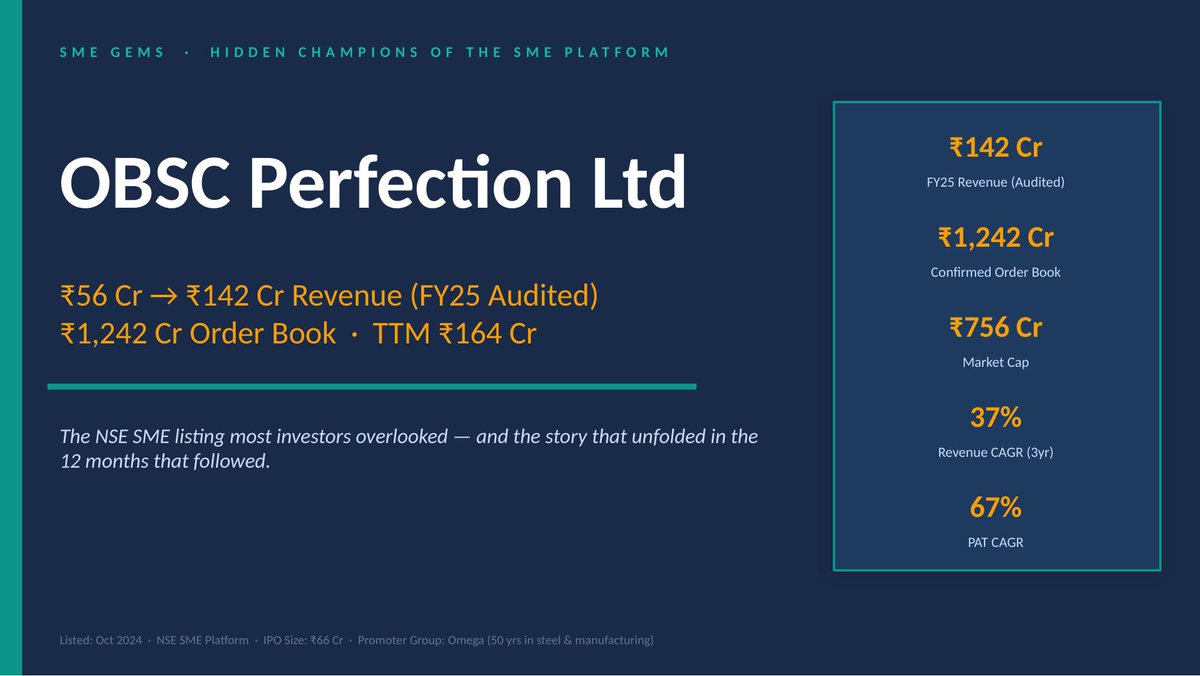
👉Introducing SME Gems — a new independent series on Hidden Champions of the SME Platform :
💠 OBSC Perfection
💠 Aimtron Electronics
💠 Yash Highvoltage
💠 CFF Fluid Control
💠 DSM Fresh Foods
💠 L.T. Elevator
💠 Monolithisch India
💠 GSM Foils
👉Across Different Sectors. One common place.
🔗 https://t.co/Sto1a1qHIQ
👉Stay tuned for more insights
———
⚠️ For educational purposes only. Not investment advice. Please DYODD.
#SMEGems #SMEPlatform #HiddenChampions #SME
#Zappfresh
#DSMFreshfoods
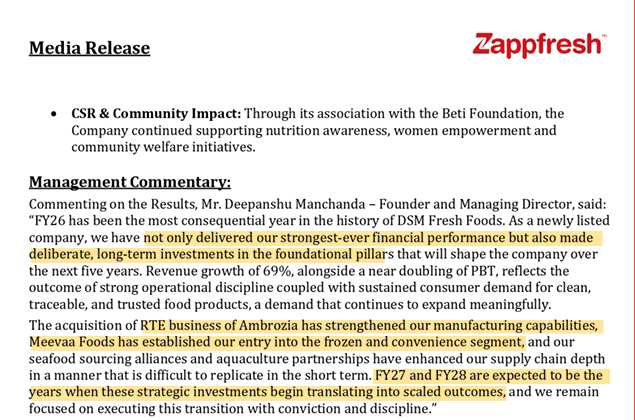
Management commentary:
"FY27 and FY28 are expected to be the years when these strategic investments begin translating into scaled outcomes"
"We have not only delivered our strongest-ever financial performance but also made deliberate, long-term investments in the foundational pillars that will shape the company over the next five years."
1. Inorganic growth:
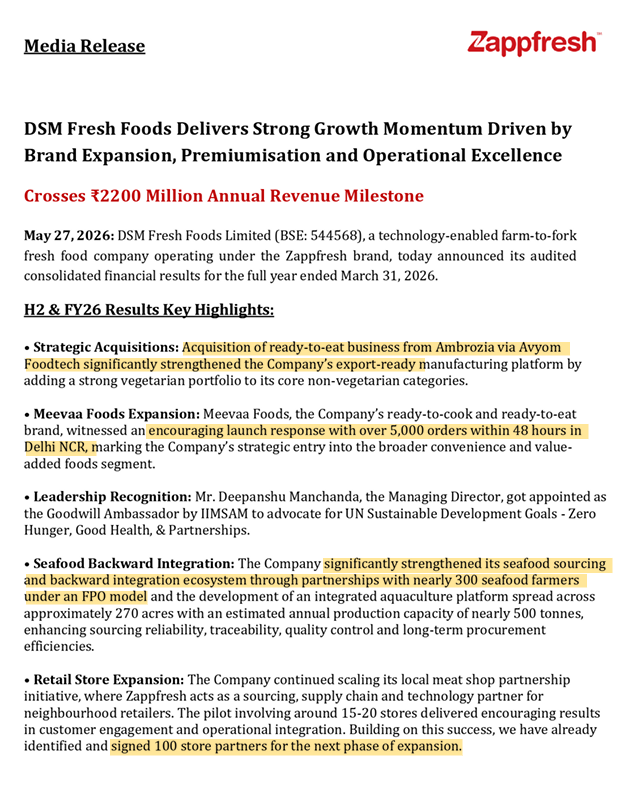
Strategic Ready-to-Eat (RTE) Acquisition: Acquired the RTE business of Ambrozia via Avyom Foodtech, adding a crucial vegetarian portfolio to its core non-vegetarian offering and strengthening its export-ready manufacturing capability.
Brand Expansion via Meevaa Foods: Launched the Meevaa Foods brand (Ready-to-Cook/Ready-to-Eat), capturing strong initial traction in Delhi NCR with over 5,000 orders within the first 48 hours of launch.
Seafood Backward Integration: Partnered with nearly 300 seafood farmers under an FPO model, establishing an integrated aquaculture platform across ~270 acres (annual capacity of ~500 tonnes) to secure sourcing, improve traceability, and lower long-term procurement costs.
Retail Store Footprint Scaling: Following a successful 15–20 store pilot, the company has signed 100 store partners for the next phase of its local meat shop partnership model, operating as their sourcing and technology partner.
2. Business Mix
Evolving B2B Mix: The B2B segment's contribution rose to ~68% of total revenue in FY26. While its lower-margin profile mildly compressed short-term PAT margins (down 41 bps), it structurally enhances long-term capacity utilization and institutional stickiness.
Diversified Product Portfolio: The company maintains a healthy, balanced protein mix to mitigate category risks: Chicken leads at 50%, followed by Seafood at 27%, and Mutton at 23%.
3. Financial Performance:
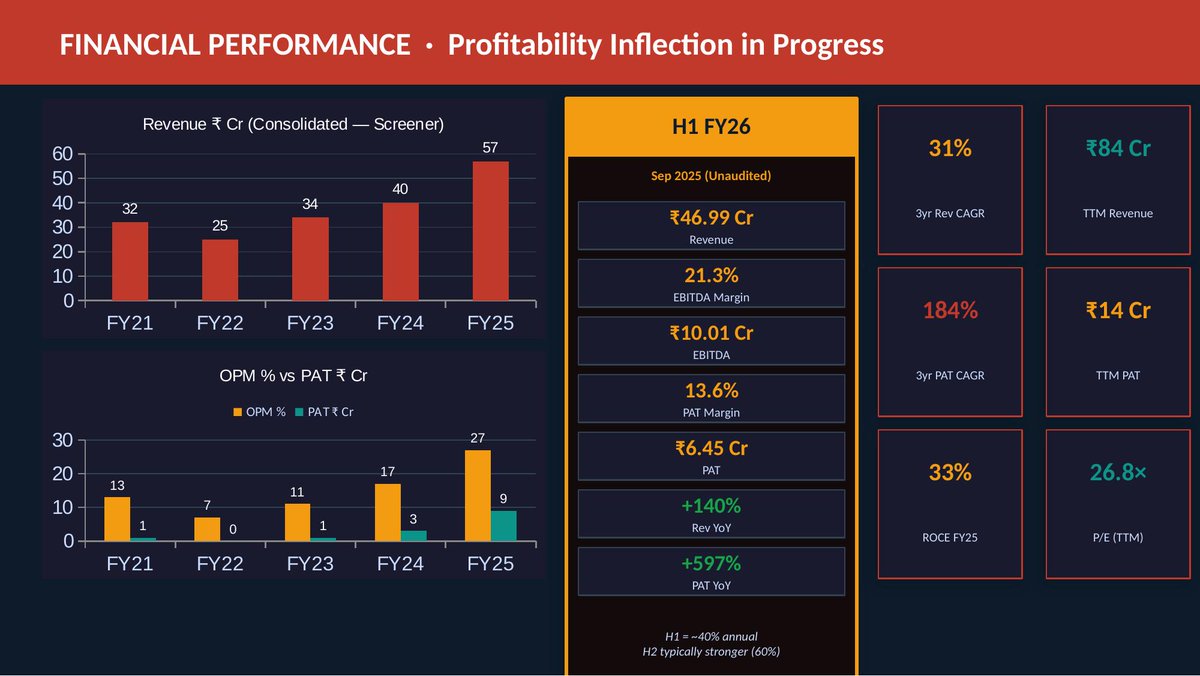
Robust Top-line Growth: Total annual revenue crossed the ₹2200 million milestone, coming in at INR 2,208 Mn, representing a massive 69% YoY growth compared to INR 1,307 Mn in FY25.
Strong Operating Leverage: EBITDA grew by 91% YoY to INR 311 Mn, with EBITDA margins expanding by 160 bps to 14.1%, indicating highly efficient scaling despite ongoing investments.
Earnings Expansion: Profit Before Tax (PBT) nearly doubled to INR 232 Mn (up from INR 117 Mn). Profit After Tax (PAT) increased 59% YoY to INR 143 Mn (6.5% margin), though it was temporarily weighed down by a one-time deferred tax charge. Normalised PAT stood stronger at INR 184 Mn.
Accelerating H2 Momentum: Revenue grew ~50% sequentially in H2 FY26 to INR 1,250 Mn (vs. INR 959 Mn in H1), showing a strong acceleration in business momentum in the latter half of the year
Cashflows are very weak at the moment as management focussing on growth first
Company is trading at very attractive levels and doesn't move from IPO price. Only profitable company in this Industry at the moment.
Licious IPO expecting in this year, may rerate this company
Last Seen Hashtags on Sotwe
Trends for you
Most Popular Users

Elon Musk 
@elonmusk
241.5M followers

Barack Obama
@barackobama
118.8M followers

Cristiano Ronaldo
@cristiano
114.5M followers

Donald J. Trump
@realdonaldtrump
111.8M followers

Narendra Modi
@narendramodi
107.1M followers

Rihanna
@rihanna
98.7M followers

NASA
@nasa
92.3M followers

Justin Bieber
@justinbieber
91.8M followers

KATY PERRY
@katyperry
90M followers

Taylor Swift
@taylorswift13
84M followers

Lady Gaga
@ladygaga
75.5M followers

Virat Kohli
@imvkohli
73.5M followers

Kim Kardashian
@kimkardashian
70.9M followers

YouTube
@youtube
68.8M followers

Neymar Jr
@neymarjr
66.5M followers

Bill Gates
@billgates
65.3M followers

Selena Gomez
@selenagomez
63.1M followers

The Ellen Show
@theellenshow
62.2M followers

CNN
@cnn
61.7M followers

X
@x
60.7M followers