

Top Tweets for #hyTech

#htel
#Hytech Engineers
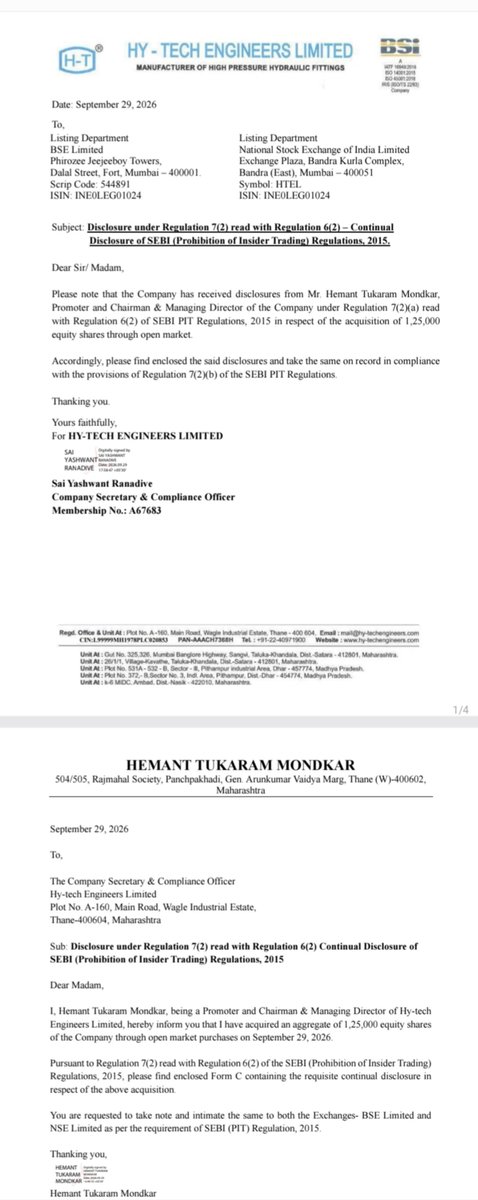
Promoter bought 1.25L shares at avg ₹68.68
Value: ₹85.85L | Open-market | 29 Sep
New Idea
#Hytech engineering 77
No buy/sell recomendation
Hy-Tech Engineers Ltd (HTEL / 544891) is a 48-year-old Maharashtra-based manufacturer of hydraulic fittings. It listed on NSE and BSE on 1 September 2026 at a 36–42% premium to its ₹53 IPO price and has since traded roughly in the ₹75–81 range.9d37c8
Business-standard
It is a B2B precision-engineering play, not a broad capital-goods conglomerate. The long-term case rests on whether it can convert industry tailwinds, capacity expansion, and new high-barrier segments (rail + defence) into sustained 15%+ earnings growth from a reasonably healthy margin and balance-sheet base.
What the company actually does
Hy-Tech designs and makes hydraulic fittings — the connectors that join pipes, tubes and hoses in high-pressure hydraulic systems. Portfolio: 11,000+ SKUs covering DIN-metric, JIC, ORFS, conversion and custom fittings.ba8ec8
Economic Times
End markets (FY26 mix, approx.):
Construction machinery ~23%
Farming equipment ~23%
Automotive ~9%
Hydraulic systems, injection moulding, railways/defence and others
Six plants (Thane, Shirwal, Kavathe, Nashik forging, two in Pithampur). Installed capacity ~483 lakh pieces/year plus 3,120 MT captive forging. Utilization ~70%. IATF 16949 and ISO 14001 certified; also IRIS (railways) and DRDO approval (defence).8cf0f4
Ipowatch
~170 direct customers, high repeat business (~90%), some relationships stretching 25 years. Exports ~29% (US is the largest overseas market; group company Hy-Tech USA Inc. acts as distributor). Domestic ~71%.
Financial snapshot (restated consolidated)
Metric
FY24
FY25
FY26
Revenue from operations
₹137.7 Cr
₹161.4 Cr
₹189.4 Cr
Total income
₹141.2 Cr
₹166.7 Cr
₹193.4 Cr
EBITDA
₹22.6 Cr
₹35.8 Cr
₹41.7 Cr
PAT
₹11.6 Cr
₹19.6 Cr
₹22.6 Cr
EBITDA margin
~16%
~22%
~22%
PAT margin
~8%
~12%
~12%
Revenue CAGR ~17% over two years; PAT more than doubled from FY24. ROE ~20%, ROCE ~24%. Debt has come down (from ~₹43.5 Cr to ~₹30 Cr) and IPO proceeds include another ₹16 Cr for repayment.112981
Business-standard
Post-issue shares ~9.49 crore. At ~₹76–79 the market cap is roughly ₹720–750 Cr, or about 32x FY26 PAT. At the IPO price the multiple was closer to 22x.
Why there is a structural story
Industry growth is real, not cyclical hype. India’s hydraulic fittings market grew ~10% CAGR recently and is projected at ~11% through CY31 (CARE/Maia figures cited in the RHP), driven by construction equipment, farm mechanisation, industrial machinery and infrastructure spend. Global demand is also expanding.bada8a
Sebi
Capacity is being added with IPO money. ~₹30 Cr of the ₹60 Cr fresh issue goes into machinery at Shirwal, Kavathe and Pithampur. Those units are slated for 40–80% capacity increases. Combined with existing ~30% unused capacity, volume growth is visible if demand holds.
Rail and defence are new, higher-entry-barrier markets. IRIS certification and DRDO approval open government-linked, quality-sensitive work where unorganised players struggle. These are still small in the mix but strategically important given India’s capex and indigenisation push.
Backward integration and product breadth. The Nashik forging unit gives cost, quality and lead-time control. 11,000+ SKUs plus custom work create switching costs once a customer has qualified the fittings.
Export optionality. 29% export share with an established US channel. China+1 and nearshoring could help if they keep quality and delivery consistent.
Promoter and operating history. Hemant Mondkar (IIT Bombay) has run the business for decades. This is not a 5-year-old “story stock.”
Why someone might hold it long-term
Niche manufacturer with decent pricing power (22% EBITDA) in a market that should grow with India’s physical-capex cycle.
Capacity coming online + new segments (rail/defence) + export base give a multi-year volume runway.
Balance sheet is improving; interest cost should fall further.

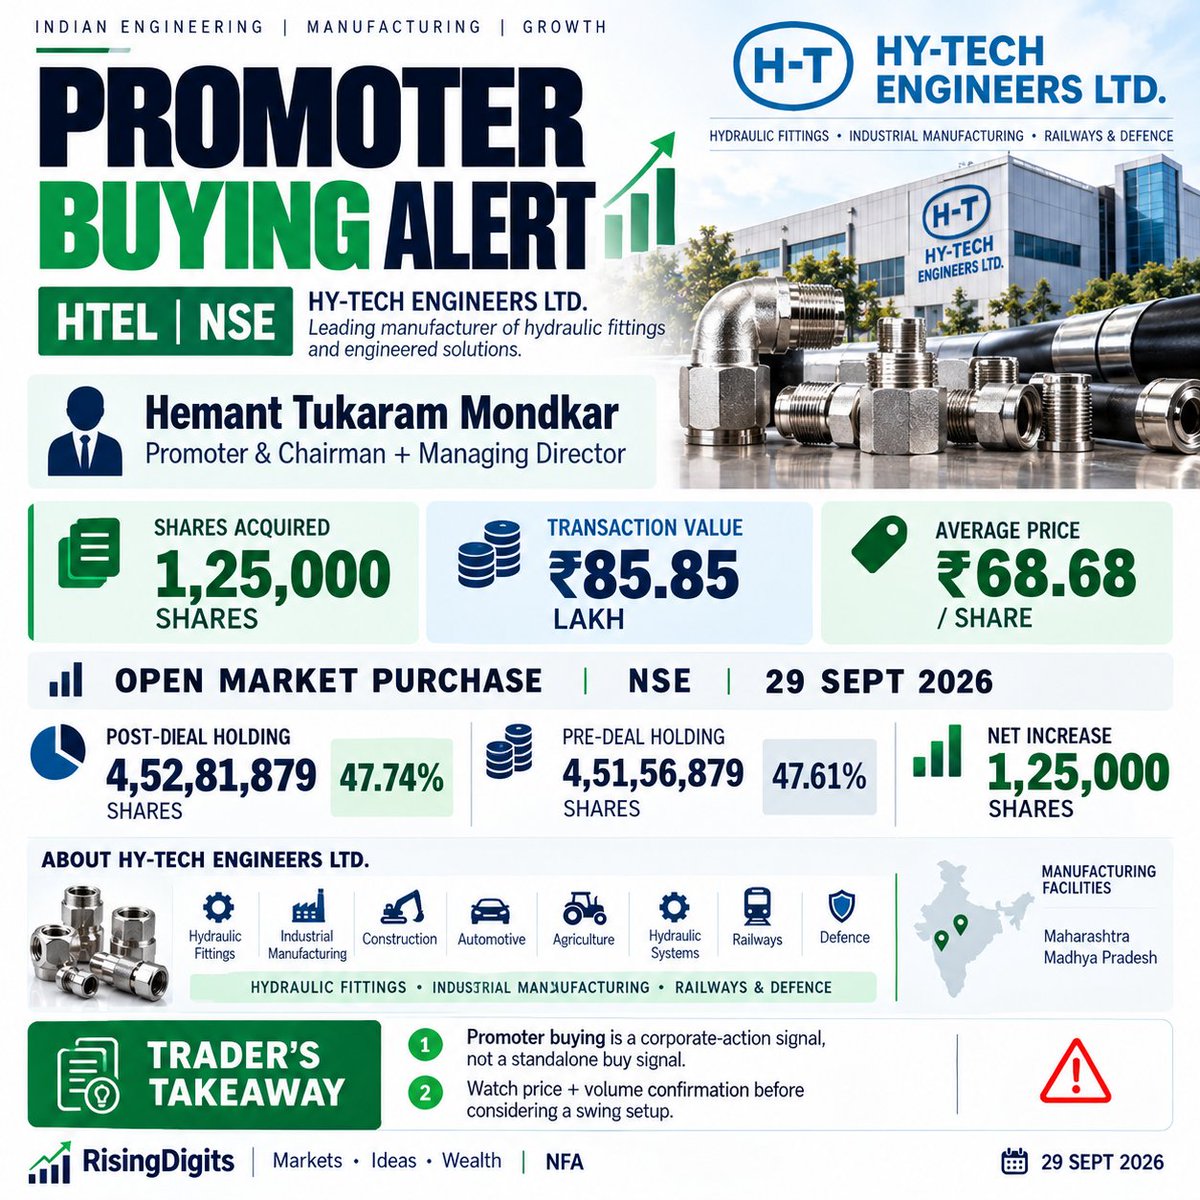
#HTEL Promoter Buying Alert
Promoter bought 1.25L shares at avg ₹68.68
Value: ₹85.85L | Open-market | 29 Sep
Post-deal holding: 47.74%
Trader takeaway: Promoter buying is a positive corporate-action signal; wait for price + volume confirmation.
NFA.
#HYTECH #SWINGTRADE #HTEL
#HTEL — Swing Setup
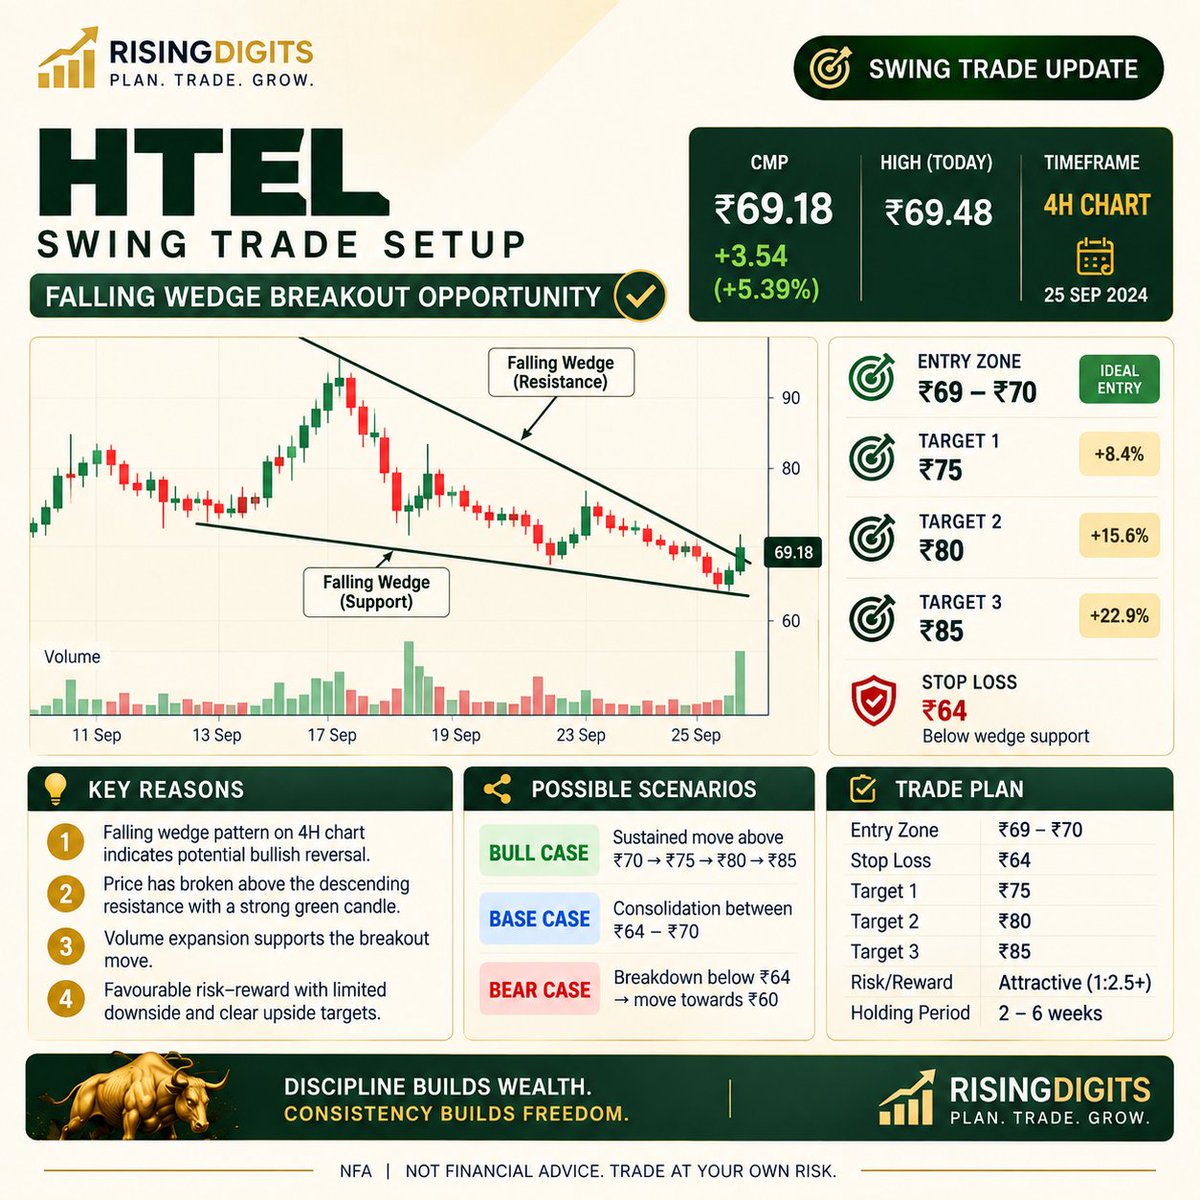
4H Falling Wedge Breakout | CMP ₹69.18
Entry: ₹69–70 | SL: ₹64
Target 1: ₹75
Target 2: ₹80
Target 3: ₹85
Takeaway: Breakout + volume confirmation; avoid chasing.
#HTEL #NSE #SwingTrading

Added Hytech at pre-open.
Brief thesis: Strong growth potential, healthy business fundamentals and, most importantly, valuation looks relatively low compared with the growth opportunity and sector peers.
At the current valuation, I believe the risk-reward looks attractive for the long term.
#Hytech #IPO


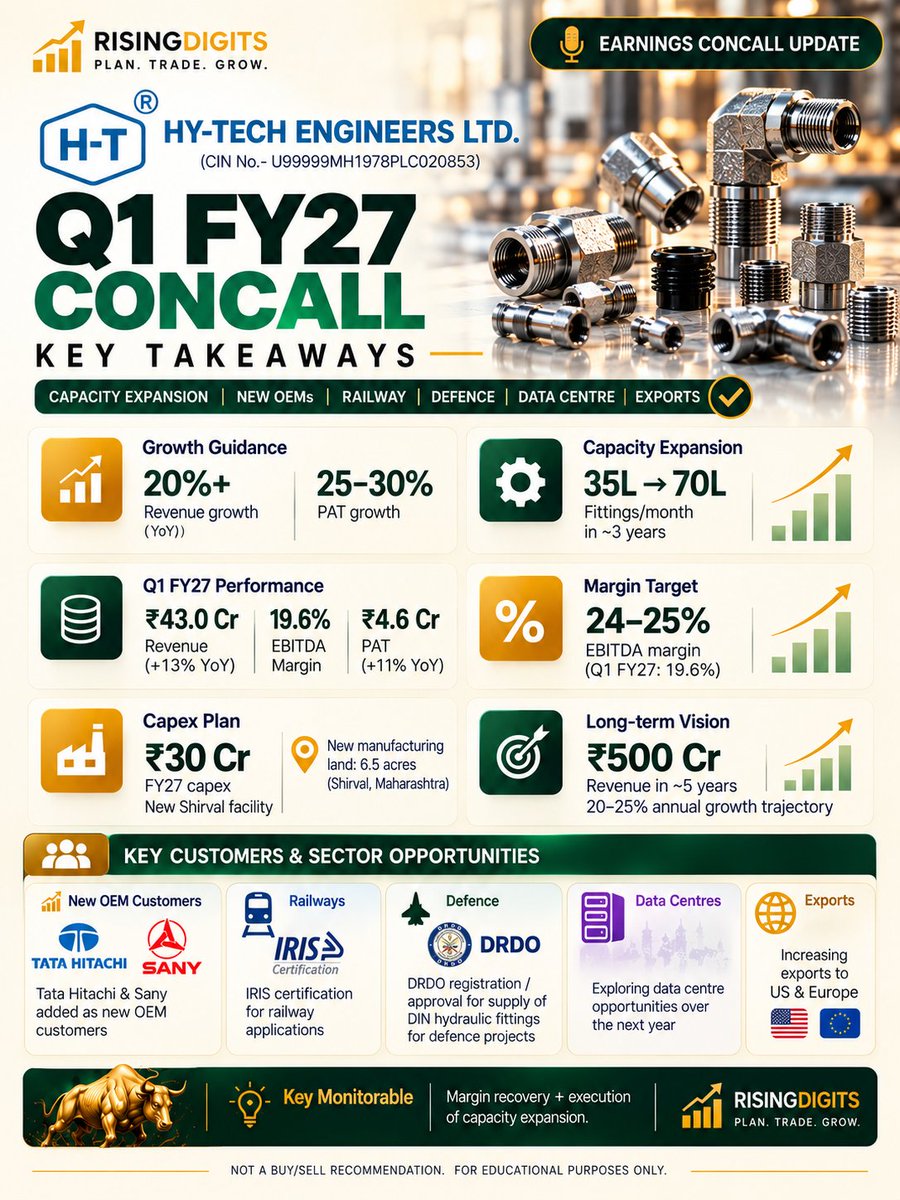
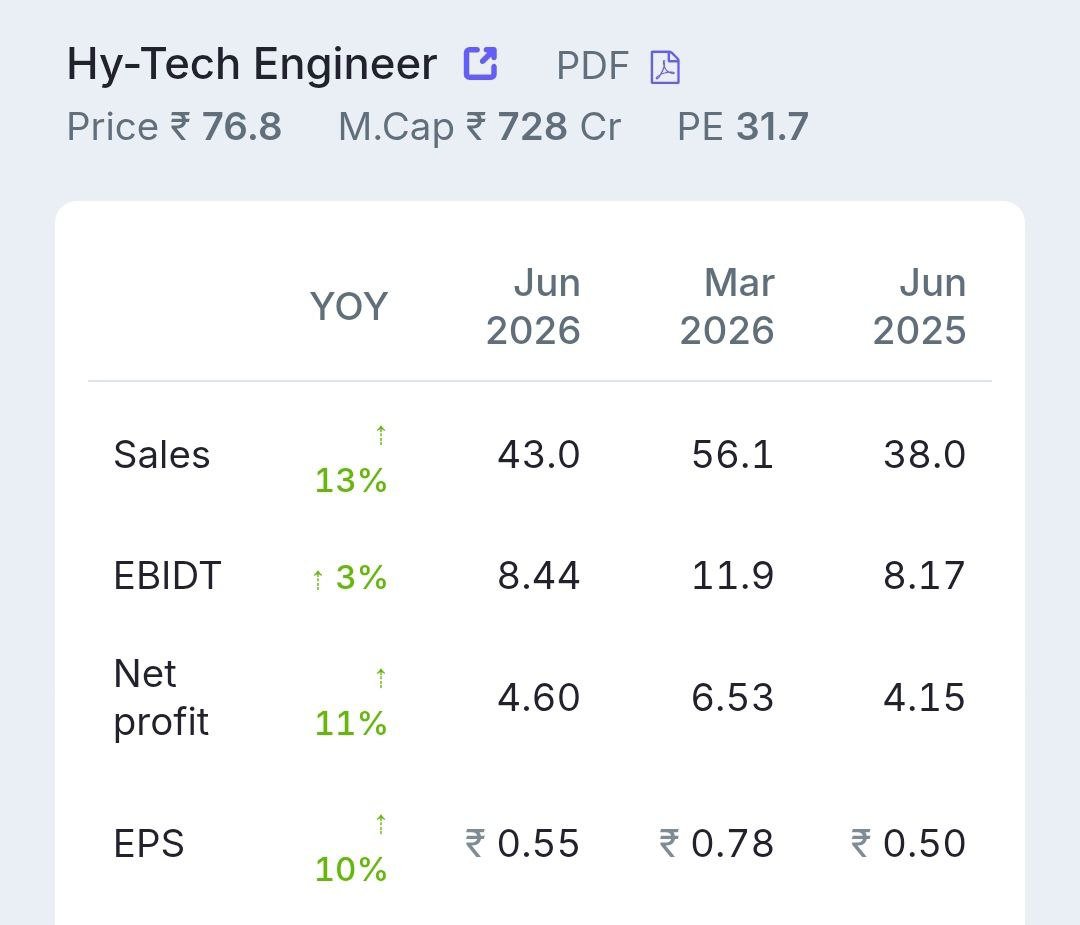
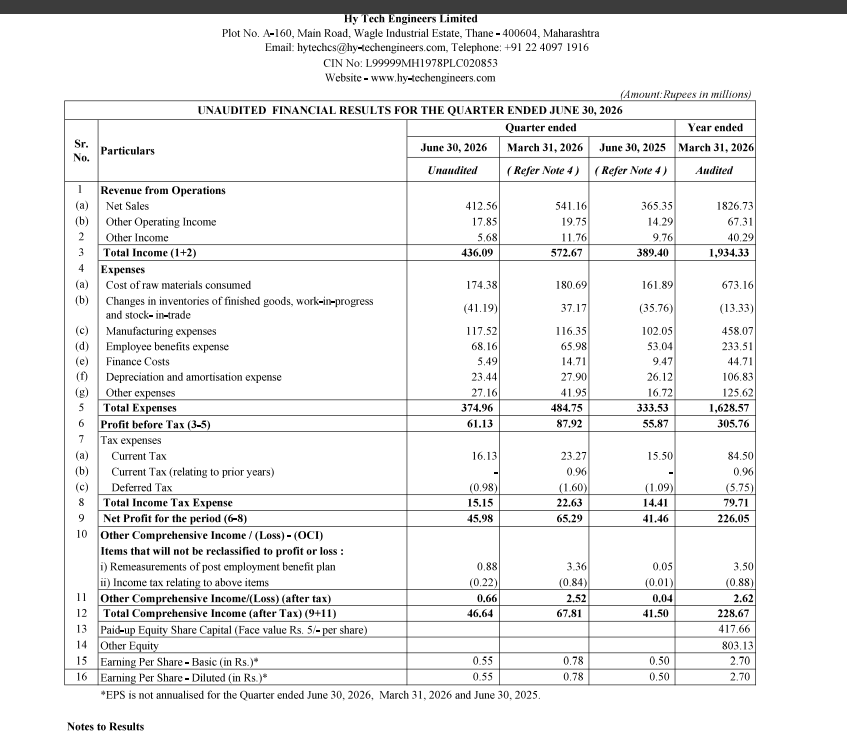
Hy-Tech Engineers Ltd Q1FY27 Results:-
#Q1Results #Q1FY27 #Stockmarket #Nifty #Hytech
Total Revenue 43.04 Cr vs 37.96 Cr
(+13.37% YoY┃-23.27% QoQ)
EBITDA 8.44 Cr vs 8.17 Cr
(+3.28% YoY ┃-28.96% QoQ)
EBITDA Margin 19.60% vs 21.52% YoY & 21.17% QoQ
PBT 6.11 Cr vs 5.59 Cr
(+9.41% YoY┃-30.47% QoQ)
PAT 4.60 Cr vs 4.15 Cr
(+10.90% YoY┃-29.58% QoQ)
Other Income 0.57 Cr vs 0.98 Cr YoY & 1.18 Cr QoQ

Hy Tech Engineers
Snapshot from website and google
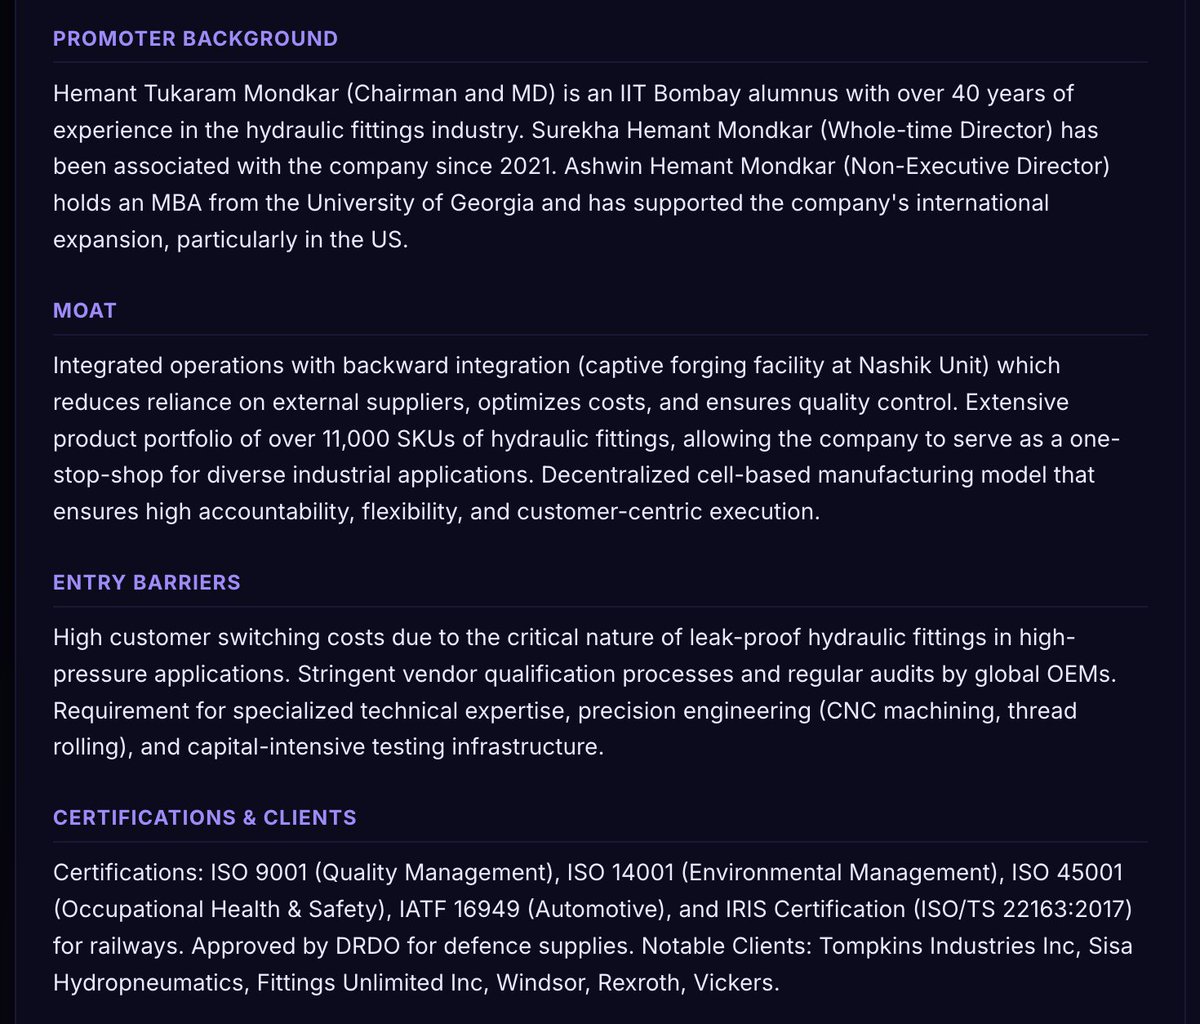
Company with high moat and very very cheap valuations, all peers at 100PE
Approved by DRDO as supplier
Promoter from IIT bombay
No buy sell recommendation
#hytech



#HyTech Engineers
CMP: 85.6
MCAP: 812cr
P/E: 36.1
Hy Tech is expanding its factory capacity in a big way. It plans to add new machines at three of its units, Shirwal, Kavathe and Pithampur which will raise their production capacity by roughly 45%, 41% and 83% respectively.
Since these plants are already running at 60 to 85% utilization, this extra capacity directly translates into more pieces sold once it comes online, without needing entirely new factories.
The company is also pushing hard into new high value sectors like defence and railways. These are areas where India is investing heavily in modernization, and hydraulic fittings used here typically carry stricter quality requirements, which means better pricing power.
The company already holds an IRIS railway certification and DRDO defence approval, so it is positioned to capture this demand early.
Exports are another strong lever. International sales already make up close to 30% of revenue, and management wants to grow this further by entering new countries, investing in local logistics and building stronger distributor relationships abroad. Export markets tend to offer better margins than the domestic market, so growing this share should help profit growth outpace revenue growth.
The company is also planning to enter the valves business, which uses the same customer base and manufacturing skills it already has. This is a natural extension that could open a whole new revenue stream without much additional capital investment.
Finally, there is a steady focus on getting more business from existing customers and distributors, adding new product variants (thousands of new SKUs every year), and improving efficiency through backward integration and cost control. Since more than 95% of revenue already comes from repeat customers, this loyal base gives a strong and stable platform on which all the above growth drivers can build.

LAST 10 IPO ALLOTMENT SCORE 👇🏻
#TEMPSENS~0/20
#AUGMONT~0/11
#HYTECH~0/7
#SYMBIOTEC~0/7
#SKYWAYS~0/7
#LUMINO~0/11
#ESDS~0/15
#PRIORITY~0/5
#DEEPA~0/7
#MOMSBELIFE~0/5
Last 10 IPOs mein ek bhi allotment nahi mila 😭
Lagta hai merry kismat ka GMP -100% chal raha hai! 🤡
New Idea
#Hytech engineering 77
No buy/sell recomendation
Hy-Tech Engineers Ltd (HTEL / 544891) is a 48-year-old Maharashtra-based manufacturer of hydraulic fittings. It listed on NSE and BSE on 1 September 2026 at a 36–42% premium to its ₹53 IPO price and has since traded roughly in the ₹75–81 range.9d37c8
Business-standard
It is a B2B precision-engineering play, not a broad capital-goods conglomerate. The long-term case rests on whether it can convert industry tailwinds, capacity expansion, and new high-barrier segments (rail + defence) into sustained 15%+ earnings growth from a reasonably healthy margin and balance-sheet base.
What the company actually does
Hy-Tech designs and makes hydraulic fittings — the connectors that join pipes, tubes and hoses in high-pressure hydraulic systems. Portfolio: 11,000+ SKUs covering DIN-metric, JIC, ORFS, conversion and custom fittings.ba8ec8
Economic Times
End markets (FY26 mix, approx.):
Construction machinery ~23%
Farming equipment ~23%
Automotive ~9%
Hydraulic systems, injection moulding, railways/defence and others
Six plants (Thane, Shirwal, Kavathe, Nashik forging, two in Pithampur). Installed capacity ~483 lakh pieces/year plus 3,120 MT captive forging. Utilization ~70%. IATF 16949 and ISO 14001 certified; also IRIS (railways) and DRDO approval (defence).8cf0f4
Ipowatch
~170 direct customers, high repeat business (~90%), some relationships stretching 25 years. Exports ~29% (US is the largest overseas market; group company Hy-Tech USA Inc. acts as distributor). Domestic ~71%.
Financial snapshot (restated consolidated)
Metric
FY24
FY25
FY26
Revenue from operations
₹137.7 Cr
₹161.4 Cr
₹189.4 Cr
Total income
₹141.2 Cr
₹166.7 Cr
₹193.4 Cr
EBITDA
₹22.6 Cr
₹35.8 Cr
₹41.7 Cr
PAT
₹11.6 Cr
₹19.6 Cr
₹22.6 Cr
EBITDA margin
~16%
~22%
~22%
PAT margin
~8%
~12%
~12%
Revenue CAGR ~17% over two years; PAT more than doubled from FY24. ROE ~20%, ROCE ~24%. Debt has come down (from ~₹43.5 Cr to ~₹30 Cr) and IPO proceeds include another ₹16 Cr for repayment.112981
Business-standard
Post-issue shares ~9.49 crore. At ~₹76–79 the market cap is roughly ₹720–750 Cr, or about 32x FY26 PAT. At the IPO price the multiple was closer to 22x.
Why there is a structural story
Industry growth is real, not cyclical hype. India’s hydraulic fittings market grew ~10% CAGR recently and is projected at ~11% through CY31 (CARE/Maia figures cited in the RHP), driven by construction equipment, farm mechanisation, industrial machinery and infrastructure spend. Global demand is also expanding.bada8a
Sebi
Capacity is being added with IPO money. ~₹30 Cr of the ₹60 Cr fresh issue goes into machinery at Shirwal, Kavathe and Pithampur. Those units are slated for 40–80% capacity increases. Combined with existing ~30% unused capacity, volume growth is visible if demand holds.
Rail and defence are new, higher-entry-barrier markets. IRIS certification and DRDO approval open government-linked, quality-sensitive work where unorganised players struggle. These are still small in the mix but strategically important given India’s capex and indigenisation push.
Backward integration and product breadth. The Nashik forging unit gives cost, quality and lead-time control. 11,000+ SKUs plus custom work create switching costs once a customer has qualified the fittings.
Export optionality. 29% export share with an established US channel. China+1 and nearshoring could help if they keep quality and delivery consistent.
Promoter and operating history. Hemant Mondkar (IIT Bombay) has run the business for decades. This is not a 5-year-old “story stock.”
Why someone might hold it long-term
Niche manufacturer with decent pricing power (22% EBITDA) in a market that should grow with India’s physical-capex cycle.
Capacity coming online + new segments (rail/defence) + export base give a multi-year volume runway.
Balance sheet is improving; interest cost should fall further.



#IPO #IPOAlert #Allotment #Investment
Lag Gaya Hy-Tech Engineers IPO ♥️
Check Here:
https://t.co/TEqZfX9K6n


🚨 NEW LISTINGS — TODAY 📊
🏷️ #SYMBIOTEC ₹978.20 | 🔻 -0.99%
🏷️ #SKYWAYS ₹124.50 | 🔻 -9.78%
🏷️ #HYTECH ₹72.00 | 🟢 +35.85% 🚀
🔥 HY-TECH ENGINEERS leads with +35.85% on debut!
Listing day action speaks for itself. 📈
#IPO #NewListing #StockMarket #BSE

Skyways, Hytech & Symbiotec — all three screens are looking weak.
I think the listing could be below expectations, despite the strong GMP.
GMP ≠ guaranteed listing gains. Let’s see how the market reacts.
Disclaimer Personal View.
#Skyways #Hytech #Symbiotec

Very strong Subscription Numbers! 🔥
QIB Subscription:
🔹 Hytech: 250X — ₹6,800 Cr
🔹 Skyways: 140X — ₹16,250 Cr
🔹 Symbiotec: 182X — ₹63,500 Cr
Excellent subscription in symbiotech after listing 🔥
IPO market is absolutely on fire! 🔥
#Hytech #Skyways #Symbiotec #IPO

GOT SHNI OF HY-TECH
BEST OF LUCK TO ALLOTTEES 😄
#StockMarketIndia #IPO2026 #Valuation #Investing
#IPOs #IPO #IPOListing
#SME #ipoallotment
#IPOListing
#SMEIPO #IPOALERT
#HYTECH
#HYTECHIPO


🚨 Ram.. Robert.. Rahim... With their blessings.. Secularism finally delivered 🤑
Not Triple Talaq… this is.. Triple Treat
Got allotment in 3 IPOs 🔥
🔹 Symbiotec Pharmalab
🔹 Hy-Tech Engineers
🔹 Skyways Air Services
#ipo #symbiotec #hytech #skywaysair #ipo #nse #bse #sebi #ipoalert #nifty50 #sensex #niftybank #niftyit #Nifty500 #niftysmallcap #shreekaram


Symbiotec Pharmalab - 0/3
Skyways Air Services - 0/5
Hy-Tech Engineers - 0/10
#symbiotec
#skyways
#hytech
Back to back Streak maintain🥴🤞🏻


Last Seen Hashtags on Sotwe
WebStrategies
Seen from United States
anxiouspanda
Seen from United States
ปราจีน304
Seen from Thailand
swingersparty
Seen from Germany
全裸
Seen from Korea
chibola
Seen from Mexico
hackingarts
Seen from United States
galahyde
Seen from Germany
goonedit
Seen from United Kingdom
omegle()+video
Seen from Australia
Trends for you
Most Popular Users

Elon Musk 
@elonmusk
241.8M followers

Barack Obama
@barackobama
119M followers

Cristiano Ronaldo
@cristiano
114.6M followers

Donald J. Trump
@realdonaldtrump
111.9M followers

Narendra Modi
@narendramodi
107.2M followers

Rihanna
@rihanna
98.7M followers

NASA
@nasa
92.4M followers

Justin Bieber
@justinbieber
91.8M followers

KATY PERRY
@katyperry
90.1M followers

Taylor Swift
@taylorswift13
84M followers

Lady Gaga
@ladygaga
75.5M followers

Virat Kohli
@imvkohli
73.5M followers

Kim Kardashian
@kimkardashian
70.9M followers

YouTube
@youtube
68.8M followers

Neymar Jr
@neymarjr
66.5M followers

Bill Gates
@billgates
65.3M followers

Selena Gomez
@selenagomez
63.1M followers

The Ellen Show
@theellenshow
62.3M followers

CNN
@cnn
61.8M followers

X
@x
60.7M followers