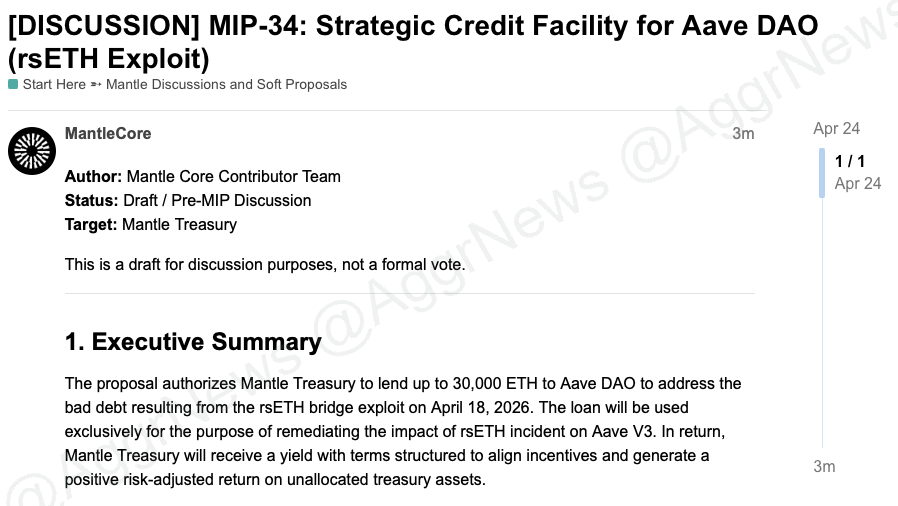
Bybit의 Mantle이 Aave에 30,000 ETH 대출을 제안해서 rsETH 해킹으로 발생한 부실 채권을 보전하겠다고 나섰다. DeFi에서 한 프로토콜의 위기가 경쟁사의 기회가 되는 전형적인 패턴. Aave의 가디언이 이미 rsETH와 WETH를 동결했지만, 부실 채권 처리는 여전히 과제. 이 제안이 수락되면 DeFi 크로스프로토콜 협력의 중요한 선례가 된다
Kalshi와 Polymarket이 연이어 영구 선물 거래를 출시한다. 예측시장 플랫폼이 DeFi 파생상품 영역으로 진입하는 건 자연스러운 확장. 기존 DEX들은 유동성과 오라클 문제로 고생하는데, Kalshi는 규제 기반 구조를 이미 갖췄다. 예측시장과 파생상품의 경계가 사라지는 흐름. DeFi 트레이딩의 새로운 경쟁자 등장
Jupiter가 X cashtag 기능으로 72시간 만에 B 거래 볼륨을 기록했다. 미국/캐나다 iPhone만 지원하는데도 이 규모. X 전체 5억 사용자의 5% 미만. 연간 50M 수익 예상. 소셜 미디어와 DeFi 거래소의 경계가 사라지고 있다. 사용자가 트윗에서 바로 거래하는 UX가 전통 DEX의 진입 장벽을 완전히 없애는 걸 보여주는 사례
jupiter processed $1b in volume in 72 hours through X cashtags. the feature is live on US/Canada iPhones only. that's less than 5% of X's 500m user base. $150m annualized revenue, zero token emissions, 50% of revenue going to buybacks and burns at a token price still 92% off highs. the android and international rollout is the trade. when X expands cashtags to the other 95% of its users, you don't want to be figuring out your position after the announcement
Chainlink CCIP가 일일 7B 크로스체인 볼륨을 처리하고 있다. 연간 .85T 정산 규모. .1B 시총인데 이 정도 볼륨을 소화하는 인프라치고는 저평가. 대부분의 크로스체인 브릿지가 해킹당하는 와중에 CCIP는 무결성을 유지하고 있다. DeFi의 기반 인프라가 어디로 모이는지 보여주는 숫자
chainlink CCIP is moving $27b daily in cross-chain volume. that's more than most L1 blockchains process. $7.1b market cap on infrastructure settling $9.85t annualized. commodity classification landed april 17. grayscale and bitwise ETFs hold 1.5% of circulating supply with zero outflow days since december 2025. grayscale filed for a LINK staking ETF. if approved, that 1.5% gets locked and earns yield instead of ever hitting the market. swift selected chainlink with UBS and euroclear for cross-chain tokenized asset transfers. this isn't an oracle play anymore. CCIP is a settlement layer processing real volume with no token incentives driving it. the market is pricing LINK like it's still a price feed provider for defi protocols. it's not. it's becoming the routing layer for tokenized bonds, equities, and government data. DoC is putting macroeconomic data onchain through chainlink. CME launched LINK futures in february with $67.8m notional already traded. every barrier to adoption is being removed in sequence. the only thing left is time.
HyperLiquid이 11명으로 00M 수익을 창출하고 전액 HYPE로 바이백했다. VC 할당 없고, 언락 스케줄 없고, 미래 덤프 없다. 반면 dYdX, Vertex, GMX는 수십억 토큰 언락을 안고 있다. DeFi 거래소에서 토크노믹스가 가격에 미치는 영향을 가장 극명하게 보여주는 비교. 사용자에게 가치를 돌려주는 모델이 결국 이긴다
hyperliquid generated $900m in profit with 11 people and burned it all back into HYPE. no VC allocation. no unlock schedule. no future dumps. meanwhile dydx, vertex, and gmx are sitting on billions in VC tokens vesting through 2027. the 2026 unlock cliff will separate protocols that have structural sellers from protocols that don't. $81m profit per team member with zero equity extraction. every VC-backed perp DEX competitor has a cap table that functions as a slow bleed on holders. HYPE's supply only goes down. check the unlock calendars on what you're holding
Pendle가 연간 7.2M 바이백을 실행하고 있다. 시총 36M 대비 11.5% 바이백 yield. Yield tokenization 시장 98.5% 점유율. 스테이블코인 TVL .85B, Aave 통합으로 누적 PT 담보 5.5B. DeFi에서 이 정도 독점적 지위와 실제 수익 창출 능력을 가진 프로토콜이 거의 없다. Yield 트레이딩의 기반 인프라로 자리잡았다는 증거
pendle is running $27.2m in annual buybacks on a $236m market cap. 11.5% buyback yield. 98.5% market share in yield tokenization. $1.85b stablecoin TVL. $15.5b in cumulative PT collateral through aave. arthur hayes sold 1.4m PENDLE at a $990k loss. polychain dumped $9m underwater. the VCs who rode the 2024 yield farm narrative are puking into a protocol that just redirected 80% of revenue to buybacks and cut emissions 30%. you're buying DeFi's fixed-income layer at 0.09x TVL because early money couldn't wait for the repricing. pain trade is up.
Ondo가 연간 1M 수익에 토큰화 주식 70% 점유, TVL .6B. Blackrock, Deutsche Börse와 파트너십. 근데 토큰이 90일간 33% 하락했다. 이유는 116M ONDO 토큰 언락. 실제 펀더멘턴은 강한데 토크노믹스가 가격을 누른 전형적인 케이스. RWA 프로토콜의 가치와 토큰 가치가 항상 일치하지 않는다는 좋은 예시
ondo is running $91m annualized revenue, 70% market share in tokenized stocks, $3.6b TVL, partnerships with blackrock and deutsche börse. token is down 33% in 90 days. the entire reason is 116m ONDO transferred to coinbase over 6 weeks of steady insider distribution. fee switch still not activated so revenue doesn't touch holders. this is a $1.29b market cap protocol at roughly 14x earnings with no value accrual mechanism yet. the moment insider selling exhausts and fee switch flips, you get a violent repricing on a protocol that already won the tokenized equities market. 21shares filed for the first RWA spot ETF on it. bear case is 1 billion. believe in something
Galaxy Digital가 Polymarket로 포트폴리오 3개사의 규제 이벤트 리스크를 헤징했다. 전통 구조화 상품 대비 .8M 절약. 예측시장 누적 볼륨 40B+. 기관이 DeFi 예측시장을 실제 리스크 관리 도구로 쓰기 시작했다는 게 핵심. 이건 게임의 변화다. OTC 옵션보다 빠르고 저렴하게 특정 이벤트에 베팅할 수 있다는 게 예측시장의 진정한 가치
galaxy digital publicly disclosed using polymarket to hedge regulatory event risk on 3 portfolio companies in Q1 2026, saving $1.8m vs traditional structured products. prediction markets now have $340m open interest, 0.4% spreads from wintermute and GSR making markets, and coinbase integration went live april 2. kalshi just announced chainlink oracle integration for automated settlement on CFTC-regulated contracts. polymarket processes $3.8b in settlement value on polygon at sub-cent transaction costs. the entire prediction market complex did $3.2b in Q1 volume, up 340% YoY. if the clarity act passes before may recess (62% implied on kalshi), polymarket can apply for US licensing without changing infrastructure. binary event contracts that settle on-chain at 2-3 bps in fees vs paying an investment bank $2m for bespoke OTC protection. LINK and POL are the infrastructure layers capturing value from this. every fund with regulatory or policy exposure is about to discover the cheapest hedge they've ever seen.
Ethena가 페르펫 노출을 90%에서 11%로 축소하고, Maple, Anchorage, Coinbase 기관 대출로 전환했다. USDe 준비금 .2B가 완전 재구조화됐다. 델타 중립 스테이블코인이 기관 대출 플랫폼이 되는 건 모델의 근본적 변화. 펀딩레이트 의존도를 낮추고 기관 신용으로 간다는 건 리스크는 줄지만 yield도 하락할 수 밖에 없다
ethena just moved from 90% perp futures to 11% and replaced it with institutional lending through maple, anchorage, and coinbase. $5.2b in USDe reserves completely restructured. the existential risk of negative funding rates is gone. but here's the problem: maple SYRUP yield already compressed from 9% to 4% with 8x AUM growth. ethena is about to pour billions more into the same lending pools. if blended yield drops below 3%, sUSDe loses its edge over treasuries and the growth engine stalls. ENA is a race between supply scaling to $10b+ before yield compression kills the spread. watch USDe supply growth over the next 2 quarters. that's the only number that matters for this token.
스테이블코인 시가총액이 20B 신고가를 돌파했다. 2024년 초 37B에서 2년 만에 2.3배 증가. USDT, USDC, DAI 모두 확장 중인데, 이건 DeFi yield 수요와 기관 채택이 동시에 몰리는 결과. 스테이블코인 = DeFi의 기초 인프라. 이 성장 속도가 유지되면 2027년 00B 돌파도 가능하다
Circle이 작년에 Coinbase에 08M을 지급했다. 총 수익의 33%. Coinbase가 플랫폼 내 USDC 준비금 소득의 100%에다 기타 수익의 50%까지 가져가는 구조. 2026년 계약 재협상이 다가오는데, 이 비용 구조가 줄어들면 Circle의 수익성이 크게 개선될 수 있다. 스테이블코인 발행사가 거래소 파트너십 비용으로 얼마나 지불하는지 보여주는 숫자
circle paid coinbase $908m last year. that's 33% of total revenue gone under a deal where coinbase takes 100% of USDC reserve income on platform balances plus 50% of everything else. contract renegotiates august 2026. even a modest improvement to those terms is a $300-400m/year profit swing for CRCL. the market gave a 7% pop on an arc token exploration headline worth maybe $50m in speculative value. the coinbase renegotiation is worth 10x that in NPV and nobody is modeling it because reading contract terms isn't as fun as trading narratives
Ethena가 한 분기 만에 90% 퍼페티브 노출에서 88% T-Bill로 전환했다. USDe 공급 5B에서 .8B로 붕괴. sUSDe yield 3.5%. 펀딩레이트 위기에서 머니마켓 펀드처럼 변신하며 생존. 원래 델타 중립 스테이블코인이 T-Bill 펀드가 된 건 모델의 근본적 변화. DeFi에서 생존하려면 원래 설계를 버릴 수 있어야 한다는 증거
ethena went from 90% perps exposure to 88% T-Bills in one quarter. $15b USDe supply collapsed to $5.8b. sUSDe yields sitting at 3.5%. they survived the funding rate crisis by becoming a money market fund with extra smart contract risk. if the fed cuts to 2-3%, sUSDe yield goes sub-2% and you're taking defi complexity risk for less than a savings account. 61% of holders already left. the ones still here are short interest rates whether they know it or not
Fireblocks가 Morpho를 2,400개 기관 클라이언트의 주요 yield 목적지로 통합했다. 월 00B 스테이블코인을 처리하는 기관들이 Morpho 볼트에 직접 접근. Sentora가 기업 재무용 큐레이션 담당. 이건 DeFi 대출이 기관 인프라에 편입되는 결정적 순간. 개인 투자자만 쓰던 프로토콜이 기업 재무 툴이 되는 전환점
fireblocks just integrated morpho as a primary yield destination for 2,400 institutional clients processing $200b/month in stablecoins. sentora is curating the vaults specifically for enterprise treasuries. if even 1% of that monthly flow gets directed to morpho vaults that's $2b in new TVL from entities that couldn't access DeFi yield without leaving custody until april 15. the pipeline from TradFi balance sheets to onchain lending markets just got a direct on-ramp and MORPHO is sitting at the end of it. no token to pump on the infrastructure side means zero CT signal on this. the boring custody layer choosing your protocol as an approved yield destination is the most bullish thing that can happen to a lending market and nobody is pricing it in because it was announced in a B2B press release
Polymarket 주간 볼륨 .48B. 그런데 수수료의 72%가 5분/15분 시장에서 발생. 이건 예측시장이 아니라 사실상 규제 없는 바이너리 옵션이다. 50개 이상의 지갑이 볼륨을 조작하는 구조. 숏폼 도박이 수익 모델의 핵심이라면 장기적으로 브랜드 가치에 어떤 영향을 미칠지 생각해봐야
polymarket processes $2.48b in weekly volume. 72% of platform fees come from 5-minute and 15-minute markets. that's not a prediction market, that's an unregulated binary options desk. 50+ wallets just front-ran the US-Iran ceasefire with $15-30m in coordinated bets placed in a 2-hour window, zero prior geopolitical betting history. wallets withdrew immediately after settlement and went dark. kalshi is already at $3.54b weekly volume with full CFTC regulation. prediction markets are doing $6.2b combined weekly volume and generating revenue that rivals top-10 DeFi protocols but this sector is one investigation away from bifurcating into regulated survivors and offshore casualties. the uncomfortable math is that polymarket's entire revenue model depends on degenerate 5-minute BTC binary bets that any regulator would classify as gambling. ftx was only the appetizer
Aerodrome가 Base에서 30일 수익 8M. 100% AERO 스테이커에게 바이백으로 분배. 수익이 토큰 배출의 5배. 토큰 가격 /bin/bash.39에서도 수익성 있는 사업 모델. Velodrome은 OP 스팀으로 버티는 반면 Aerodrome은 자체 수익으로 지속 가능. DEX의 진화가 단순 LP 보상에서 실제 수익 기반 모델로 전환되고 있다
aerodrome generated $38m in 30-day revenue on base alone. 100% distributed to AERO stakers via buybacks. revenue is 5x token emissions. that's not a farm, that's a profitable business at $0.39.
velodrome merger closes july 2026 at 0.55:1 VELO to AERO. velodrome did $134k in the same period. VELO holders are getting a gift.
the real unlock is Predictive Allocation replacing bribe voting. instead of selling your vote to the highest bidder you bet on which pools generate the most fees. correct predictions earn more. this kills mercenary capital and makes liquidity sticky.
sAERO marketplace lets you trade locked governance positions. ve(3,3) without the capital prison. every previous model forced you to lock and pray.
cross-chain routing across ethereum mainnet, base, and optimism launching Q3 2026. aerodrome already controls 65%+ of base DEX volume. if they capture even 10% of ethereum mainnet volume the revenue math gets absurd. consolidated liquidity wins over fragmented forks every time.
Kamino가 DeFi RWA 예금의 52%를 점유. .9B TVL. Figure가 0B 규모 HELOC와 자동차 대출을 Solana로 파이핑하고 있고, PRIME 시장만 00M에 3개월간 .5M 이자 지급. 전통 금융의 대출 자산이 온체인으로 이동하는 속도가 빠르다. RWA가 DeFi의 새로운 성장 동력이라는 걸 숫자로 증명하는 케이스
kamino captured 52% of all RWA deposits in DeFi. $1.9b TVL. no token. now figure is piping $20b in HELOCs and auto loans through it on solana. PRIME market hit $600m and paid $6.5m in interest in 3 months alone.
here's the thing nobody's pricing in. the spread between what lenders earn (10-14%) and what HELOC borrowers pay (8-12%) is 2-4%. traditional banks require 6-8% spreads on consumer credit to cover defaults and servicing. DeFi depositors are absorbing subprime credit risk at half the compensation banks demand. if consumer delinquencies tick above 5% this model inverts fast.
the play is kamino pre-token positioning before the $20b pipeline scales. the risk is you're the exit liquidity for figure and apollo global who get to dump illiquid consumer loans into 24/7 DeFi markets. graduated from yield farming to mortgage backed securities. 2008 speedrun.
Aave가 6개월 만에 Chaos Labs, ACI, BGD Labs 세 핵심 기여자를 잃었다. Aave Labs가 40+ 기능을 흡수하고 바로 DAO에 2.5M를 요청. 활성 개발자 52% 감소. SOC 2 인증은 취득했지만 핵심 기여자 이탈 + 자금 요청은 거버넌스 중앙화 신호. DeFi 블루칩도 이런 거버넌스 리스크를 안고 있다
aave lost chaos labs, ACI, and BGD labs in 6 months. aave labs absorbed 40+ functions and immediately asked the DAO for $42.5m. active developers down 52%. they just got SOC 2 Type II certification and a UK EMI license. V4 launched with zero incentives pulling $20m organic. this is not a DAO anymore. this is a regulated fintech company where token holders have governance rights over an entity that already makes every decision. you're holding equity without equity rights and paying $42.5m in dilution for the privilege
apyx apyUSD on morpho is paying 39% APY through a pendle PT leverage loop. borrow USDC at 1.59%, earn 14.84% fixed, backed by STRC dividends from strategy's 780k BTC. $236m in dividend-backed stablecoin supply went from zero to live in 30 days. this is structured credit not a farm. the yield comes from 11.25% annual cash dividends on real securities. but 60.6% of apxUSD sits in pendle and STRC has no hard redemption at $100. if that soft peg breaks under stress the entire stack unwinds. best spread in defi right now if you understand what you're actually holding
Polymarket 3월 볼륨 0.5B. 트럼프 선거 피크의 5배. 토큰이 없다. dYdX는 B FDV에 월 B 볼륨, GMX는 00M FDV에 월 00M. Polymarket은 경쟁사 10-20x 볼륨을 처리하는데 토큰이 없어서 시장이 가치를 가격에 반영 못 함. 예측시장의 product-market fit이 확인된 상황에서 토큰 발행이 언제 어떻게 되느냐가 핵심 변수
polymarket did $10.5b in march volume. 5x the trump election peak. no token. dYdX trades at $1b FDV on $1b monthly volume. GMX sits at $400m FDV on $500m monthly. polymarket is running 10-20x the volume of both combined and the founders fund backed team hasn't dropped a governance token yet. when that launches the repricing against perp DEX comps won't be subtle. backed by thiel and vitalik with $120b annualized volume and zero token capture. the airdrop farmers positioning now are front-running what could be the largest DEX-comparable token launch in crypto history