*BREAKING: Bondistan is opening its borders on 15th September to celebrate Lehman Collapse Day and you're invited to get your visas ready!
The Ultimate Guide to Bondistan 2nd Edition is coming to print!
Do me a favour and spread the word!
More details to follow.
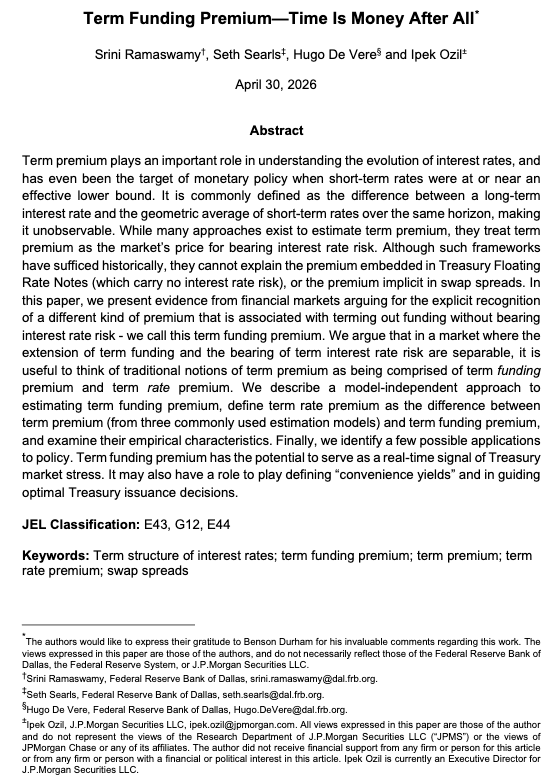
New WP. Core idea is term premia embed more than rate risk compensation. That is, the comp for extending funding to term which we called term funding premium (TFP)
New WP. Core idea is term premia embed more than rate risk compensation. That is, the comp for extending funding to term which we called term funding premium (TFP)
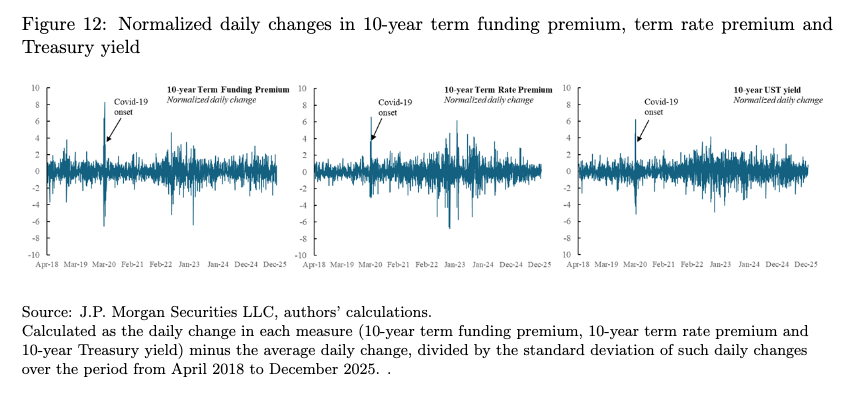
Overall, we argue TFP and TRP respond to different economic forces. TFP offers a complementary signal that sits at the core of many Tsy mkt stress episodes. During Covid, the term funding component rose to extreme levels and only normalizeÍd after Fed LSAPs stabilized the market.
Going forward, if this type of flow from AI financing grows, the long end of the curve and long-maturity swap spreads may diverge from their historical relationship.
New blog out on how AI financing is impacting rates, esp. swap spreads.
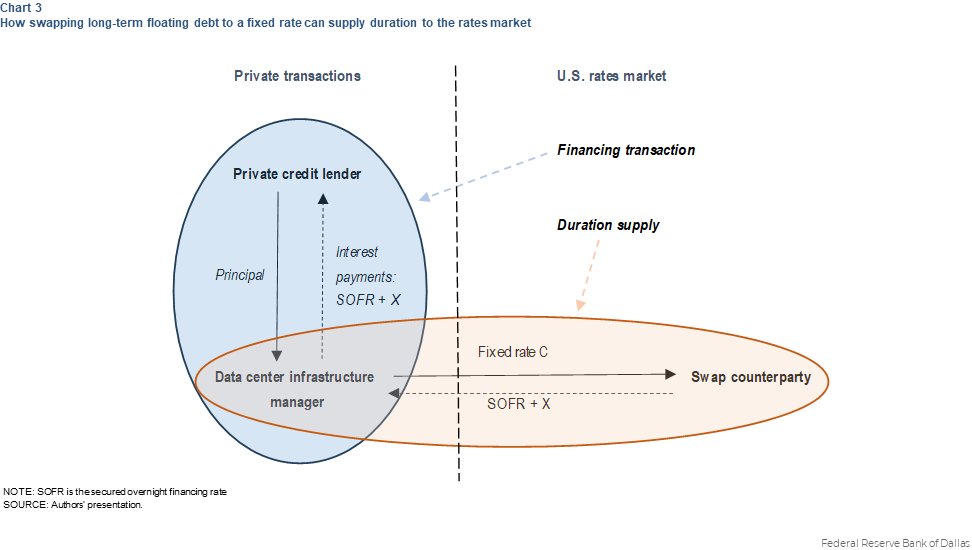
One channel we discuss is how data centers are being financed, which can generate meaningful pay-fixed flow that could impact spreads. Chart below is hypothetical...
https://t.co/e7dDjAp8zf
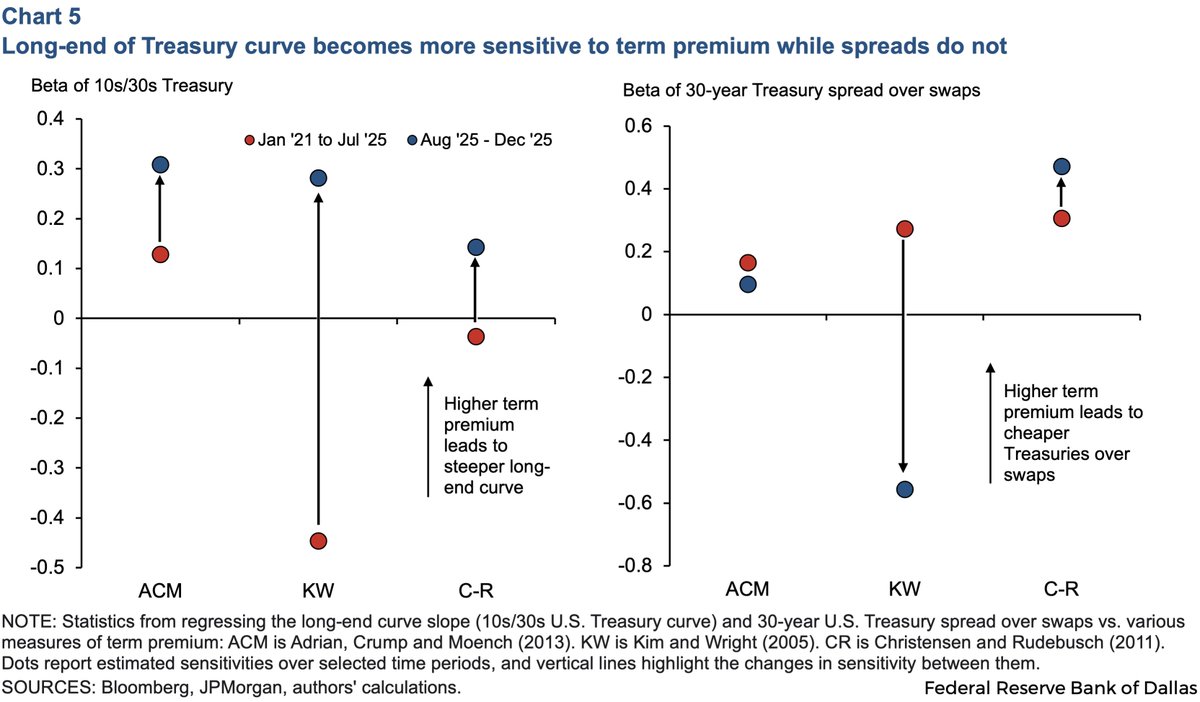
Therefore, if this supply has had meaningful mkt impact, you’d expect a divergence in sensitivities, e.g. 10s30s UST and 30y spreads react differently to term premia. And that’s what we see in chart below: the 10s30s curve has become more sensitive to TP, but 30y spreads have not
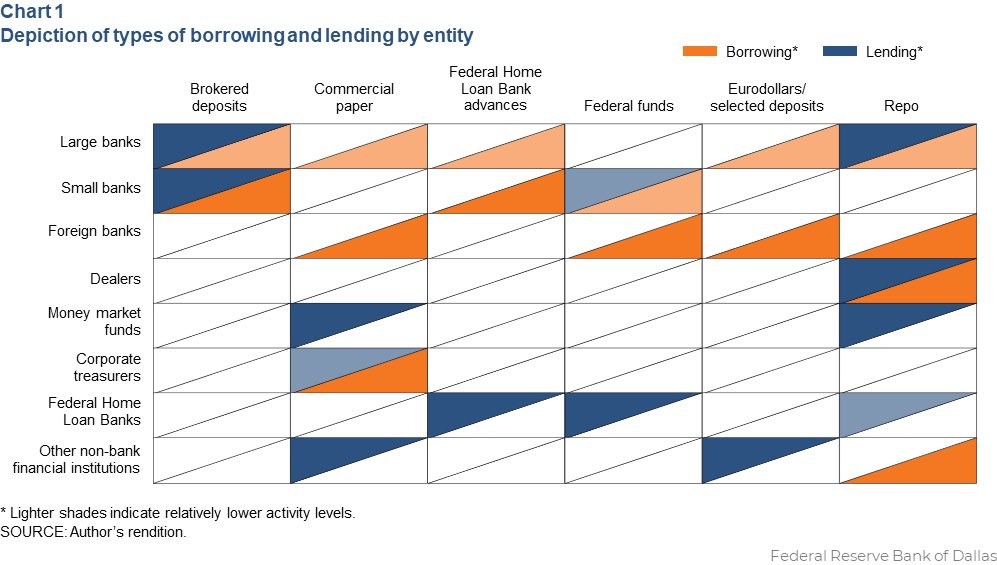
New blog post that focuses on the network of markets and institutions that trade liquidity, and how these network structures affect the pass through of different monetary policy instruments.
https://t.co/qsRmq3s7B0