On harnesses, I vacillate between three beliefs:
- the less harness, the better. Models are the magic
- post training a model and harness is dramatically better and the model providers win
- harnesses have real independent value from the model
I have no idea which is right.
Feature richness and UX flow have served as durable moats while coding and design were scarce.
Coding is now rapidly commoditizing toward near-zero marginal cost. UX design remains somewhat constrained—for now—but likely not for long.
Traditional app moats persist only as long as “app bundles” remain as it has been, which I increasingly doubt.
The last wave exposed the fragility of 'GPT wrappers.' This time it is for coding wrappers, UX wrappers—whatever label we may call them.
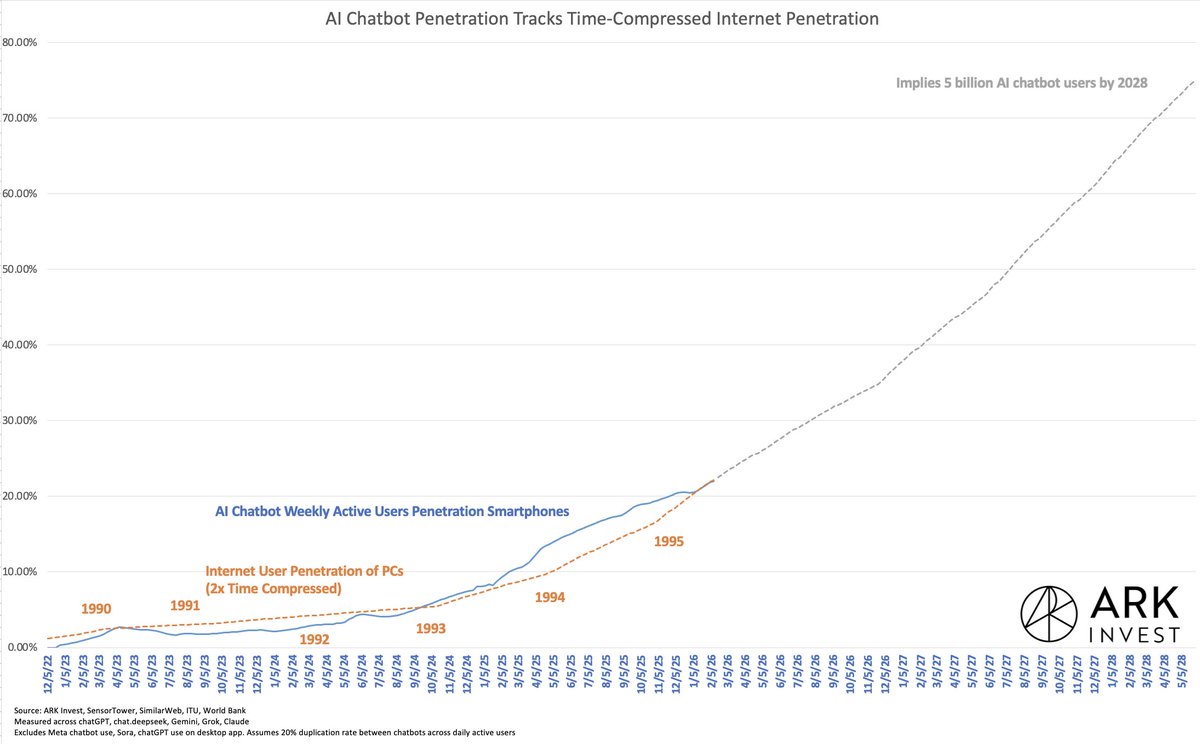
AI penetration of smartphone users roughly equivalent to January 1996 internet penetration of PC users with diffusion happening 2x faster.
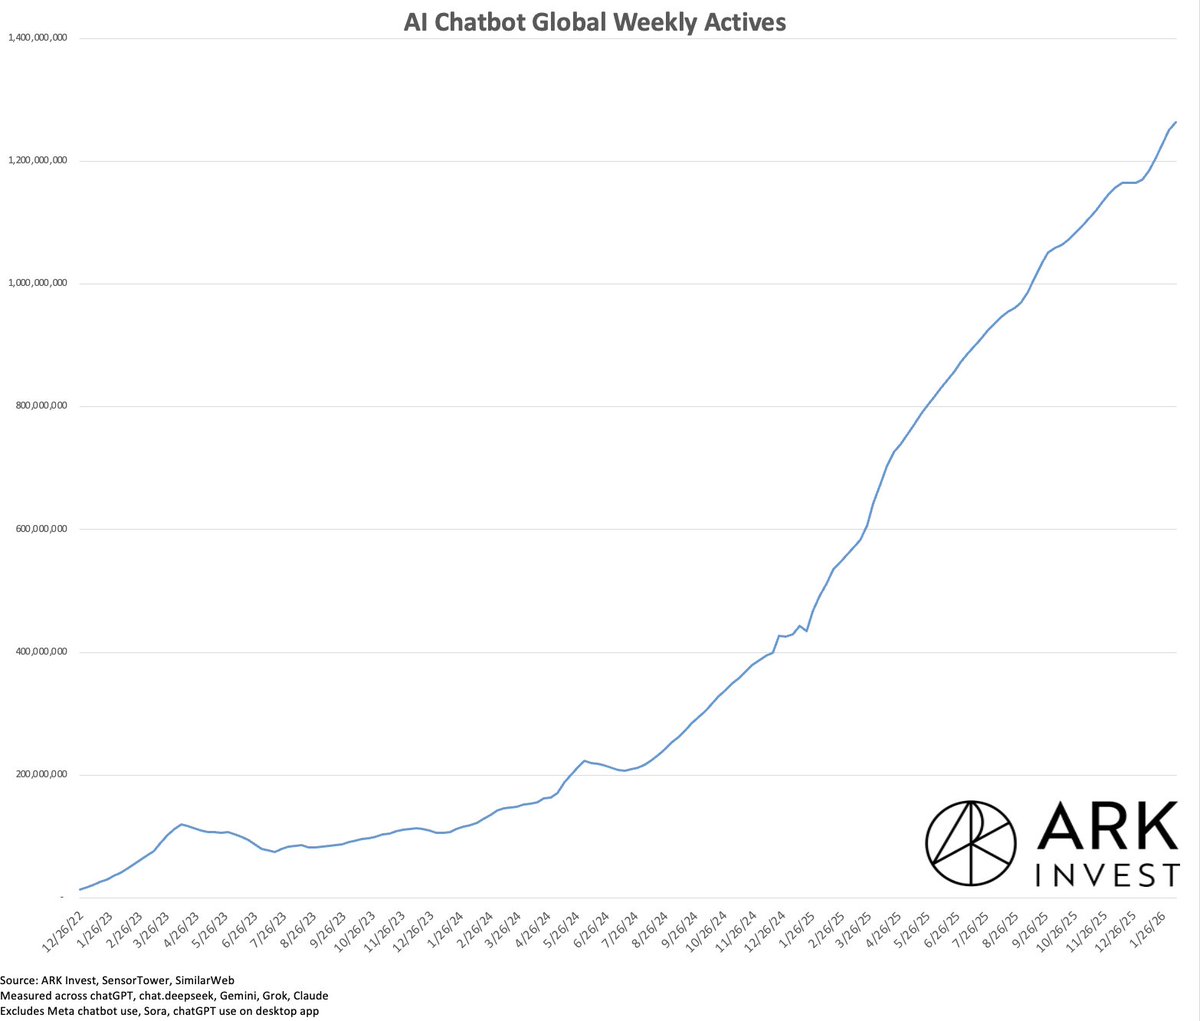
1.25 billion AI users (up 2.5x year over year), but they're not using it very much, an hour per week (up 1.6x year over year). In '96 internet users were doing a half hour per week.
Internet users got to 75% penetrated by 2000.
Implies 5 billion AI users by 2028.
Internet time use increased 7-fold by 2000 to a half hour per day.
On its compressed adoption time-scale if AI follows the same engagement trend it implies AI use will scale from ~60 billion annualized hours today to 1.3 trillion by late '28.
For context Youtube currently does 1 trillion hours.
Still very early days for AI, the consumer, and indirect monetization.
I’ve long imagined the Consumer AI landscape as a swarm of millions—eventually billions—of agents: some directly managed by individuals, others ambient and autonomous.
These agents would dynamically form and dissolve subnetworks to achieve specific goals, intermingling with humans to create a hybrid society of people and agents.
What I didn’t anticipate was seeing an early manifestation of such a semi-autonomous agent society emerge so quickly—through @openclaw in @moltbook.
An intriguing and inspiring journey lies ahead for Consumer AI.
In Consumer AI, the real outcome isn’t incremental growth, but a structural reset: new consumer flows, new distribution, and a reallocation of value away from incumbents.
After looking top-down for the shift from "Attention Economy" towards "Intent Economy", here goes bottom-up - starting from what AI newly enables, the behaviors it unlocks, and the second-order effects that define the next consumer platform cycle.
Key takeaways:
- “YouTube-ification of everything”: AI collapses the cost of creation (media → software → even scientific researches), and the durable change isn’t better outputs. It’s new behaviors at scale.
- From interface-heavy to intent-driven: the request/response UX loop weakens; users start approving the delivery for her 'intent'.
- Market structure rewrites: app bundles unbundle—expect consolidation into headless suppliers on one end and an explosion of micro-capabilities on the other, with a new “intent router” layer capturing distribution.
If you’re building in Consumer AI: the power laws likely accrue to intent orchestration, trust/permission infrastructure, and workflow-native distribution—not another standalone app with better functionalities and/or UX.
Read the full post 👉 https://t.co/338oBs55lQ
The most important shift in Consumer AI isn’t model quality—it’s where intent is captured and executed.
We’re moving from the Attention Economy to the Intent Economy.
For 20+ years, the internet monetized attention: traffic, clicks, funnels, attribution. Because true intent was hard to observe, platforms optimized proxies—SEO, ads, performance marketing, affiliate layers.
AI changes that. Users now express intent directly:
“Help me decide”, “Plan this”, “Do this for me”
As AI assistants become the endpoint—not just the starting point—traffic no longer flows through Google → SEO → ads → destination sites. When traffic reroutes, revenue reroutes.
This shift is already visible:
AI assistants are moving from search to summary
Purchase journeys are moving from search & browse to intent & recommendation
Agents can already execute end-to-end transactions for commerce and services
At a technical level, this means search → browse → checkout is being replaced by task → recommendations → selection.
When that happens, monetization shifts upstream—to whoever owns intent interpretation and execution. That puts a meaningful portion of today’s internet revenue pools at risk, including ~$130B of Google revenue and ~$55B of Amazon search ads.
The AI Super App race is really a race to own the concierge layer—the system that understands user intent, orchestrates agents, and delivers outcomes. History suggests that once this layer consolidates, value concentrates quickly.
This is not a niche opportunity. It’s a structural reallocation at internet scale—a credible $1T outcome.
Full analysis here 👇
https://t.co/Of6brYEQVq
More analysis on the ByteDance AI assistant vs. WeChat API / mini-program access conflict:
https://t.co/WjVbF1khc5
The final section lays out the real dynamics: WeChat’s platform power vs. challengers like ByteDance, Xiaomi, and https://t.co/3EjmcyUmG9.
For now, platforms hold the upper hand—especially given Chinese regulators’ preference for preserving the status quo.
Contrast this with the US/EU, where regulators tend to favor consumer choice and interoperability. That path often leads to the API access, albeit limited, as we saw in the Epic Games vs. Apple cast.
No verdict yet. These interface wars are just beginning—and likely to play out over the next 1–2 years.
Over the past week in China, we got a fascinating (and very telling) glimpse of where Consumer AI may be heading: an emerging “interface war” around AI assistants.
What happened (in days):
12/1 — ByteDance launched an Android phone with a built-in AI assistant capable of automating actions across mobile apps (think “computer use” on mobile, but enabled via API-level access to key apps on-device).
12/2–12/3 — WeChat and Taobao reportedly moved quickly to block API access.
12/6 — ByteDance appears to have conceded (for now), restricting cross-app API access.
[The Interface War Behind ByteDance's GUI Agent](https://t.co/CLBQchzKba)
What’s even more important: ByteDance isn’t alone. Similar assistants are being prepared by handset makers and AI players—Huawei (Xiaoyi), Xiaomi (Xiao AI), https://t.co/3EjmcyUmG9 (AutoGLM), and others.
*Why this matters*
This looks like the AI Assistant version of an incumbent war happening across layers—similar to the emerging “agent access for commerce” tensions we’re seeing among Amazon, Shopify, OpenAI/Perplexity, etc.
At its core, this is a battle for ownership of the consumer layer:
Mobile UX ownership (e.g., ByteDance vs. WeChat)
Commerce ownership (who “owns” discovery → intent → checkout)
*The fear: becoming “headless”*
If you lose the interface layer, you risk becoming a headless provider—a commoditized backend that fulfills requests while someone else owns the user relationship, the data, and ultimately the margin.
That’s why I was struck by two moments earlier on the US side:
(1) ChatGPT’s demos of direct product search + add-to-cart flows via function calling (which can push intermediaries toward “headless fulfillment”), and
(2) Apple’s mini-app / app-extension direction, which—depending on how it evolves—could give an assistant the power to feel like a “super-app layer” for the AI era.
*How would this end?*
I honestly don’t know. The incentives are existential for stakeholders:
ByteDance / https://t.co/3EjmcyUmG9 vs. Huawei / Xiaomi vs. WeChat / Taobao / Meituan.
A similar dynamic may play out in the US—starting with commerce and extending to assistants attempting to displace Siri and Alexa. Whether the US ever produces a WeChat-like “superapp” is still unclear—but the fight for the interface is clearly beginning.
Curious: In an agentic world, who do you think ultimately controls the consumer interface—OS players, super-apps, or the AI assistant layer?
#ConsumerAI #AIAgents #ChinaTech
Literally, Apple quietly announced something much bigger than it looks: the Mini Apps Partner Program.
While this X-eet already breaks down many first-order and second-order effects well, here are my quick takes through the lens of Consumer & AI. Still more questions than answers.
1. “AI Super Apps” are now officially legitimized
ChatGPT—with its recently announced Apps SDK—is the current frontrunner. But others will follow quickly: Perplexity, Claude, Alexa (if Amazon is truly serious), and more.
2. What happens to the other contenders?
Think: AI agent apps and AI-native browsers (Manus, Genspark…) and the new wave of AI browsers (Comet, Dia, Follou… not to mention ChatGPT Atlas).
They’re each playing a slightly different game, but ultimately chasing the same prize: a few coveted spots in the AI Super App race.
A core value proposition of “AI browsers” has been to route around platform constraints—like the App Store for iPhone. With Apple’s Mini Apps Program, the rationale for products like OpenAI’s Atlas becomes weaker, at least on mobile.
Yes, there remain important use cases—“computer-use” workflows, primarily for backward compatibility of existing web/apps, and certain agent behaviors that don’t fit neatly into Mini Apps—but the relative value narrows.
3. A flood of Mini Apps is coming—then things may get messy
Expect an early-days-App-Store moment (remember the Fart app?), followed by a crowded, chaotic market.
Much will depend on the policies of the “container” apps competing to become the dominant AI Super Apps.
China’s mobile ecosystem consolidated into tightly controlled walled gardens (WeChat, Alipay, Meituan, to name a few). Their mini-app ecosystems are curated with firm control over who gets in, how apps behave, and what gets prioritized—very different from the freer markets of the App Store or Google Play.
Apple’s (and likely Google’s upcoming soon) Mini Apps framework seems headed toward a more open, App-Store-like approach. Which leads to…
4. A surge in “developers” and “apps”—but not in the way we’d imagine
Several forces will make this ecosystem unfold differently from any past platform shift:
Vibe-coding tools enabling effortless, social creation (think: Wabi-style social sharing of AI apps).
Claude Code and similar systems solving tasks end-to-end with autonomous agents.
A massive library of user-generated prompts—from GPTs, Claude Skills, and AI browser skills—suddenly becoming “Mini Apps” themselves.
The result: a period of creative chaos before a new equilibrium emerges.
Until then, I may have to keep thinking about the second-order effects… and the ones beyond that.
Apple JUST quietly announced something that’s a lot BIGGER than it looks: "the Mini Apps Partner Program"
Apple is admitting that the future of software is embedded, lightweight, vertical mini-apps distributed inside bigger app
For founders who want to make $$ building apps:
1. Apple just legitimized the “superapp” model for the West.
China has WeChat mini-programs. India has PhonePe Switch. The West has… nothing. Apple just opened the door. You can now run HTML/JS mini-apps inside a native host and earn 85% on qualifying purchases. That’s Apple-sanctioned platform piggybacking.
2. Distribution arbitrage becomes real again.
You don’t need to convince users to download your app. Just partner with a host app and drop in a mini-app. This is a cheat code for early traction. Think: travel apps hosting niche tools, fitness apps hosting mini workouts, marketplaces hosting micro-utilities.
3. Apple is creating a new economy layer: “embedded SaaS.”
Imagine: CRM mini-apps inside vertical tools. Math solver mini-apps inside education apps. Calendar mini-apps inside productivity apps. The TAM for tools that don’t need standalone installs just went vertical.
4. Developers get an 85% revenue share.
This is Apple basically saying: “We want this ecosystem to grow, and we’re willing to cut our take rate.” When Apple lowers its cut, I pay attention because they see a platform shift coming.
5. AI makes this 10× more important.
LLM-powered micro-apps (calculators, planners, agents, coaches, niche utilities) are tiny by design. They’re perfect mini-apps. Apple just created infrastructure for AI-native micro utilities to live inside bigger apps with built-in commerce.
6. Host apps become new “distribution landlords.”
If you own an app with traffic, you become a platform. You can host mini-apps, take a cut, and build a developer ecosystem around you.
It’s a new monetization model for existing apps with audiences.
7. This unlocks a wave of second-order opportunities.
- Agencies helping apps become mini-app hosts
- Mini-app dev shops
- “Shopify for mini-apps” toolkits
- Mini-app marketplaces
- Analytics for mini-app performance
- Discovery engines for mini-apps
- I'll be dropping mini app ideas on @ideabrowser and @startupideaspod
TLDR;
Apple just turned every high-traffic app into a potential superapp and every indie developer into a potential platform partner.
The App Store is becoming modular, composable, and layered. The next decade of consumer apps will look less like standalone products and more like ecosystems stitched together with mini-apps.
This is quietly one of the biggest distribution unlocks in years.