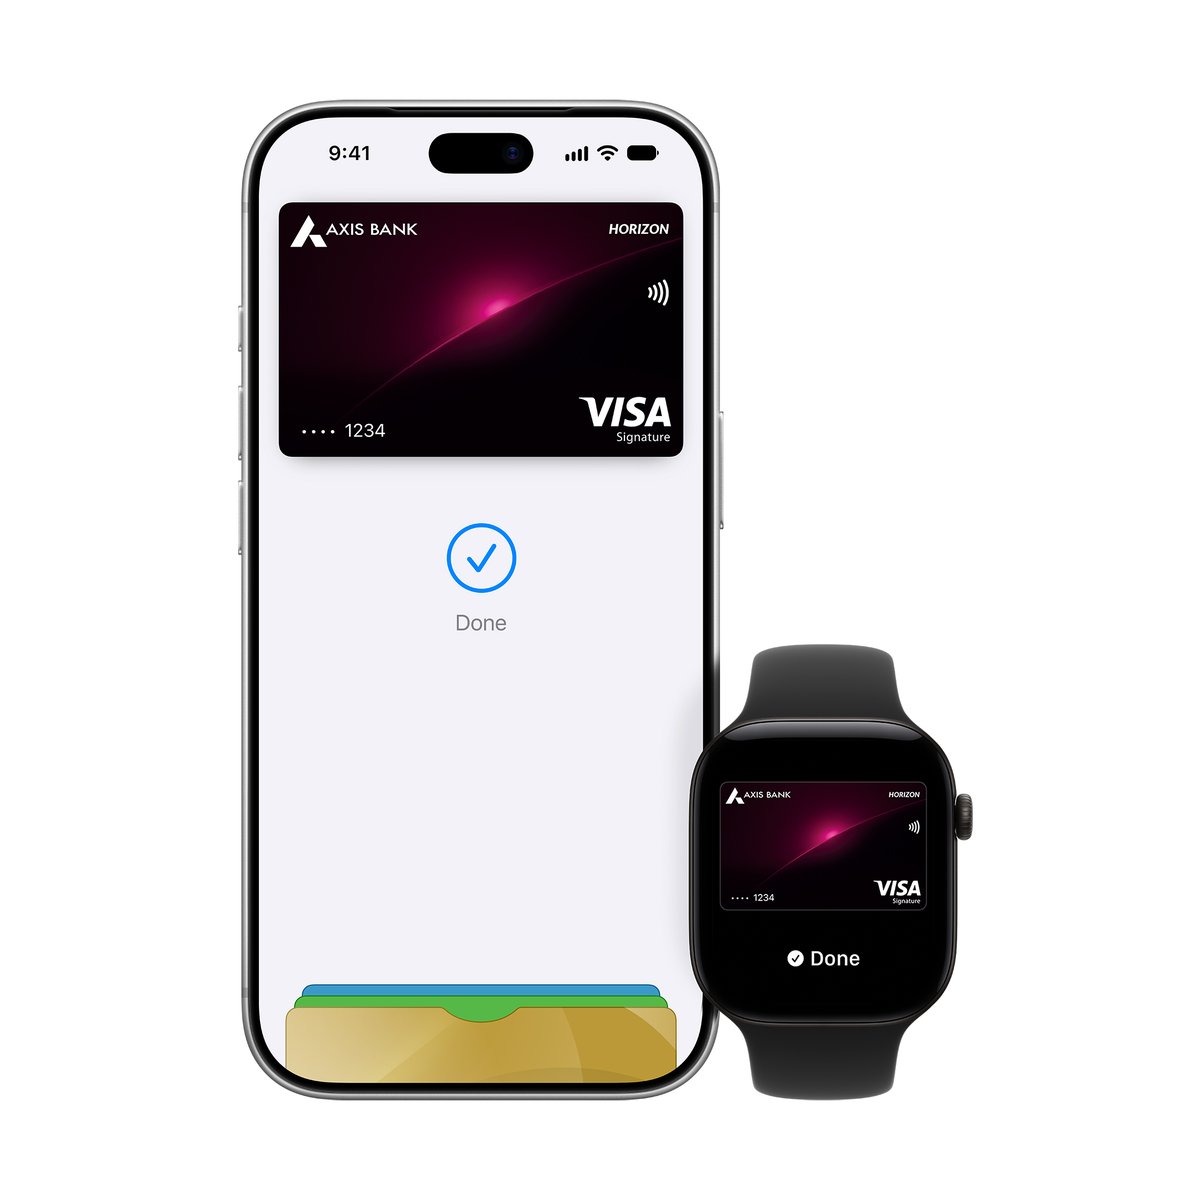
Say hello to Apple Pay in India! 🇮🇳
We’re so excited to bring Apple Pay to India today, and make it easier than ever for our customers to make safe and secure purchases on Apple devices.
🍎APPLE PAY is live in India! Finally!
How to enable
- On your iphone, Add credit card to iphone wallet
- And you are good to go!🚀
Limitations
- Only AXIS Bank Cards yet (More Banks will be added)
- Only VISA and MasterCard (Rupay excluded)
This is a promoted Tweet
Warning!
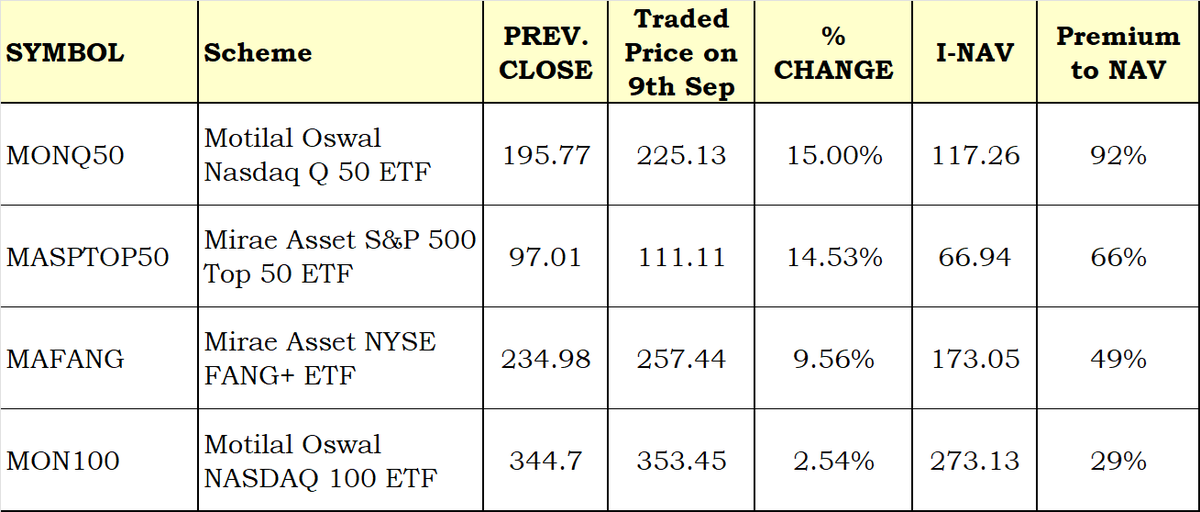
Some Global ETFs are going beserk in Indian markets.. These are some of them
Huge jump in daily traded prices and huge premium to underlying NAVs...
This can trap retail investors and also is leading to incorrect pricing of the FoFs @SEBI_updates
Sincerely request Mirae MF @MiraeAsset_IN@MotilalOswalAMC@amfiindia to issue a warning to investors and see such anomalies are not created!
I know the reason why this is happening and they know too!
Disclaimer: Pls understand all markets risks before investing. Am neither promoting nor suggesting any investments.
🇮🇳 7.8% GDP Growth 🇮🇳
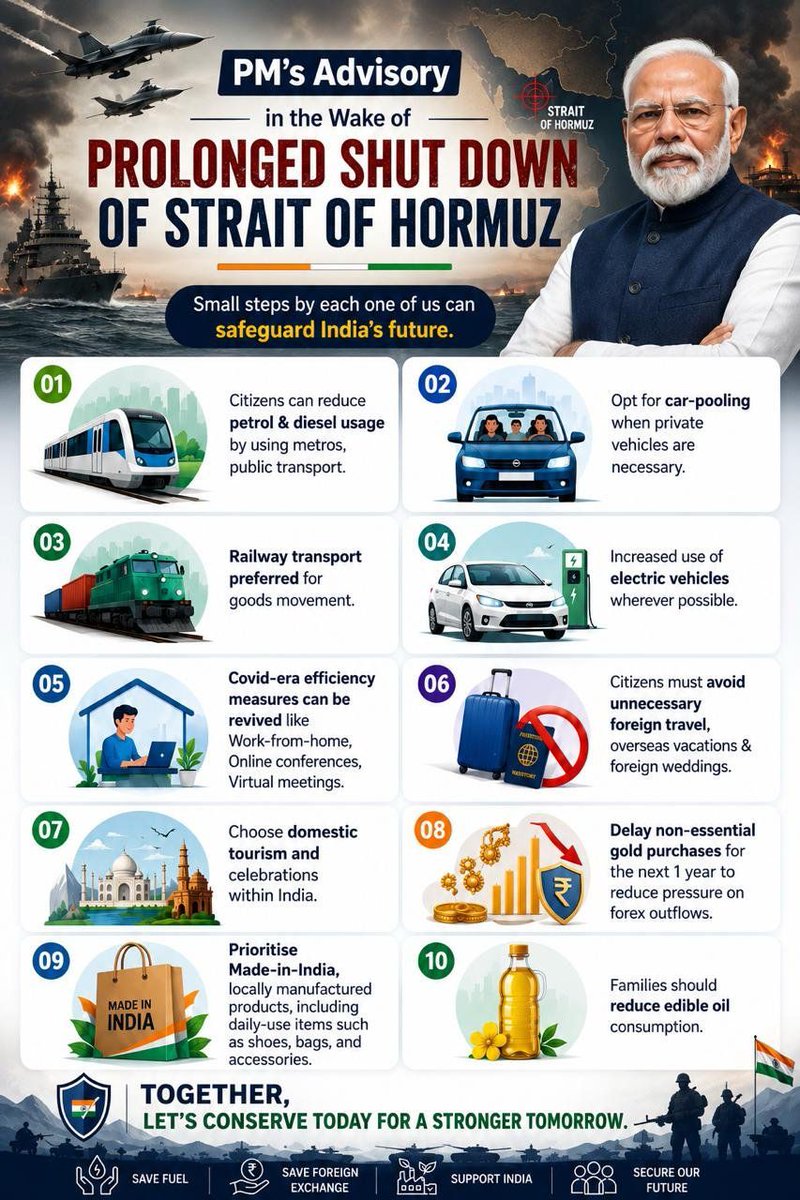
For short term, avoid discretionary International Travel eg: International Destination Weddings, holidays
Avoid buying Gold as it puts strain on forex reserves
Support the Nation 🇮🇳🇮🇳
Another post on personal finance by @kushallodha548 which is getting trolled with negative comments
Vijai @vijaimantrimf is one of most respected voices and concept of dollar cost averaging buying more units of underlying is being explained beautifully rather than the numbers
“At each of the last 40 Dhanteras, if you bought 10 grams of gold, you would have accumulated 400 grams of gold. Your total investment would have been around Rs. 8 lakh.”
“But if you had divided that Rs. 8 lakh into 40 equal amounts Rs. 20,000 every year and invested that fixed amount in gold, you would have accumulated around 1,111 grams of gold instead of 400 grams.”
“Why? Because in the first case, you bought a fixed quantity at changing gold prices. In the second, you invested a fixed amount, buying more gold when prices were lower and less when prices were higher.”
“This is the power of SIPs and rupee-cost averaging. The problem? It’s too simple. And human beings don’t like simple things.” 😄
- Vijai Mantri
There are quite a few negative comments to this post
Reality is Gajendra Kothari @gajendrakothari only shares numbers to help u realise that discipline, patience and right advise can help build wealth for each one of us
He is a true inspiration. Respect him and Etoca Wealth!
His name is Gajendra Kothari.
He does SIP of Rs. 52 Lakhs per month.
He has Mutual Fund corpus of Rs. 70 Crores.
He manages Rs. 3,000+ Crores in AUM.
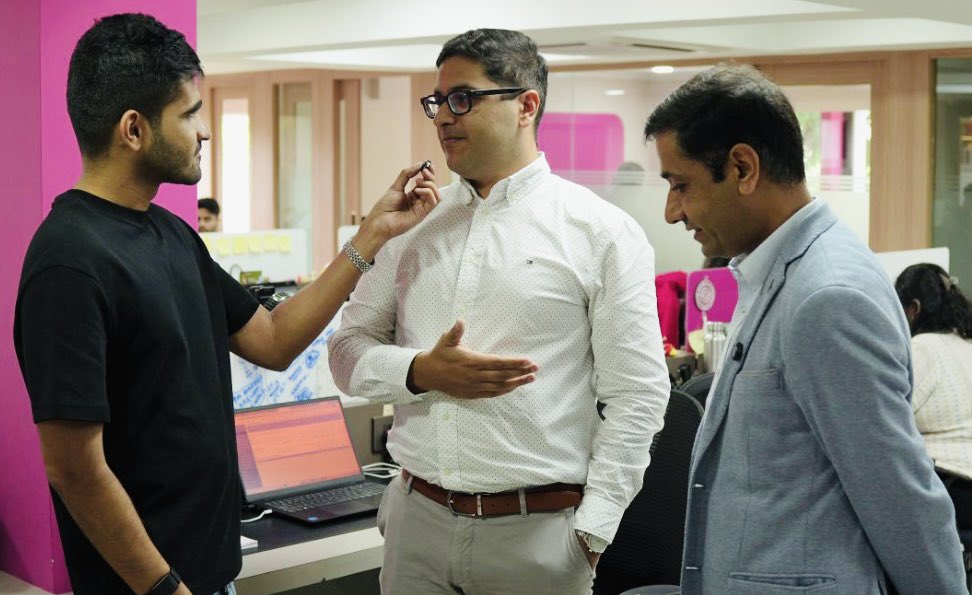
We went to his office - Etica Wealth Pvt. Ltd. , spoke to a few employees, and the stories were extremely inspiring.
There were people who were doing SIP of Rs. 25k pm, Rs. 50k pm, Rs. 80k pm and even Rs. 2L pm.
All of them started with just Rs. 500 or Rs. 21,000 pm SIP.
And all put together, their entire office must be doing an SIP of Rs. 2 Crores per month.
This is the power of investing, and compounding - wealth is created only in the long term.
The earlier you start, the more you grow!
@gajendrakothari@eticawealth
Rustomjee Crown - a new flagship premium residential complex in Mumbai under the hammer by BMC
It was constructed & sold "saying" that common areas in the lift lobby of around 300-700 sq feet can be enclosed within the house and was shown as "usuable" carpet area! Illegal!
BMC launches demolition action at the high profile Rustomjee Crown project at Prabhadevi. 128 apartments linked to politicians, bureaucrats under scrutiny. Case alleges encroachment of area around lift.
Strange, selective move given how common this is in Mumbai luxury projects.
Do read my new article
“Is it time now to invent a NEW God ?” on my blog and share your views ..
https://t.co/Pa42rP7VxZ
N.B. The above article is not against any Religion. The author respects all Religions..
Mukulism : A Point of View
@IncomeTaxIndia@IncomeTaxIndia
Got response from [email protected] that write to Efiling IT portal as no data recd from them
Accordingly sent email to [email protected]
Subject: Re: TDS RETURN TOKEN 770000386297295
Time stamp: 11:34 am Date 5th June 2026
Kindly help
Our Hon'ble PM Modiji @narendramodi has appealed to all Indian citizens to rise up to the occasion and do these 10 simple things to support our country and save Forex reserves
Let us all resolve to support the country and our PM by following these simple steps. 🙏🙏
Sandeep @sandeepjethwani Founder, Dezerv eloquently explains his strong rationale for 40 crore retirement figure
One can quarrel with higher retirement corpus and/or higher inflation of 9% taken in consideration
But one can't but reflect on strong rationale that he presents
If the 40 crore retirement number I shared shocked you, this post is for you.
Here is what I said. If you are 40 today, spending 2 lakh rupees a month, with no EMIs to service, and you want to retire at 60, you will need 40 crore rupees.
The comments had a lot of pushback. The number feels impossible. It is not. Let me show you why.
Two assumptions drive this number. Inflation and life expectancy. Both are higher than what regular retirement calculators assume. Both are right.
Start with inflation. Retail CPI in India is 5 to 6%. That is the inflation of atta, dal, and bus fare. It is not the inflation of an affluent household.
Private healthcare in India runs at 12 to 14% every year. Domestic staff wages in metros are growing at 10 to 12%. Premium school fees, international travel, club memberships. All of these inflate between 8 and 10%. Blend them and you get 9%. That is the real inflation rate of an HNI lifestyle.
Now life expectancy. Most Indians plan their retirement assuming they will live to 75 or 80. That is what national averages suggest. But national averages are pulled down by infant mortality and rural data. They have nothing to do with how long a healthy, affluent Indian actually lives. For a couple aged 65 today, there is a 71% probability that one partner reaches 85. A 44% probability that one reaches 90.
Now the math.
2 lakh rupees a month at 9% inflation becomes 11 lakh 20 thousand rupees a month at age 60. That is an annual spend of 1.34 crore.
Plan for 30 years of retirement. Your retirement portfolio which is focused on capital preservation (60% fixed income: 40% equity) earns 9%. Your Inflation is also 9%. Your real return is zero.
So corpus needed equals 30 multiplied by 1.34 crore. That is 40 crore.
Here is the good news. This number is not as far away as it looks. At 12% returns before retirement, 40 crore at age 60 translates to roughly 4 crore today for a 40 year old.
The point of this message is not to scare you. It is to make sure you understand the silent erosion of purchasing power that inflation causes.
Congratulations Sumaira! @Sumaira_SBIMF on your book release coming soon for the Indian women helpi g them with personal finances!
Knowing your depth of Personal finance knowledge, looking forward to it!
Wish you the very best!
Coming Soon To A Book Store Near You!
One conversation led to many & those many conversations led to this!
I am so excited to share that my book “The Indian Woman's Essential Guide to Investing and Building Wealth” by Aleph will soon be available at bookstores across India