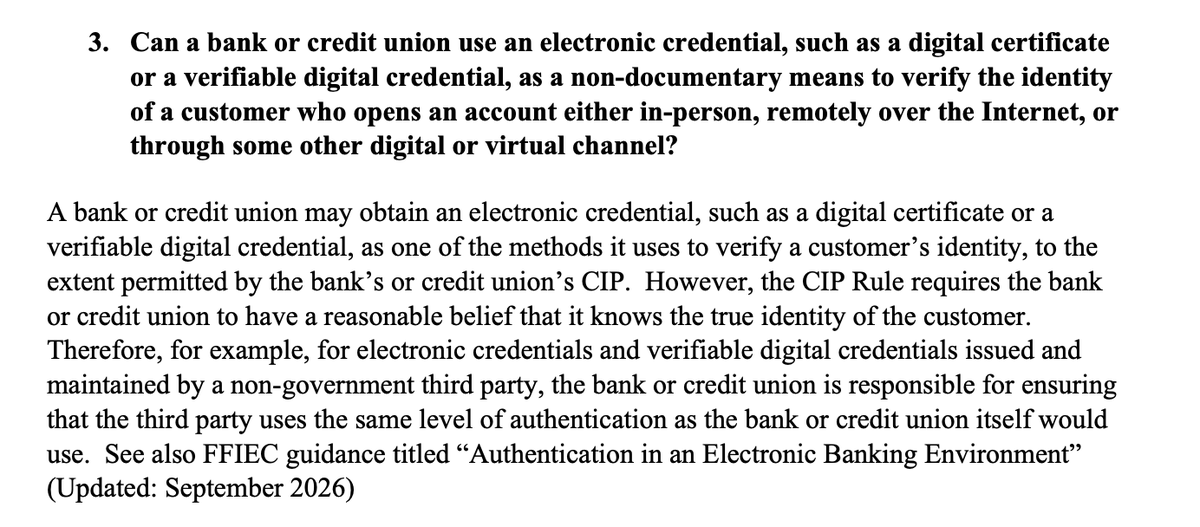
INTEL: KYC should collect less personal data and use zero-knowledge proofs to verify compliance without revealing names, income or addresses, SEC Commissioner Hester Peirce says
Verifiable Credentials (VCs) becoming the standard for KYC re-usability is one of idOS's core hypotheses from our initial thesis.
We have been building for this moment!
Some posts are a bit over-stated, but this is still a big step from US regulators to meet industry demands, and goes in line with what the EU is mandating in 2027 with eIDAS and QTSPs.
idOS is a decentralized identity layer that lets users store encrypted credentials once and reuse them across apps.
Their B1 Token Transparency Filing came back with only 2 gaps.
$IDOS live since March 5, 2026.
With the insane growth that @arbitrum and @RobinhoodCrypto chain are experiencing in the last days, most of us missed Arbitrum One's 5 year anniversary few days ago...
Happy to be part of the Arbitrum family!
"The challenge is no longer creating new rails. It's connecting them."
Exactly. And connecting rails isn't only a money problem. Every connection is a user crossing a perimeter: new onboarding, new KYC.
Money rails connect value, but also need to connect users. That's what we build.
The challenge is no longer creating new rails. It's connecting them.
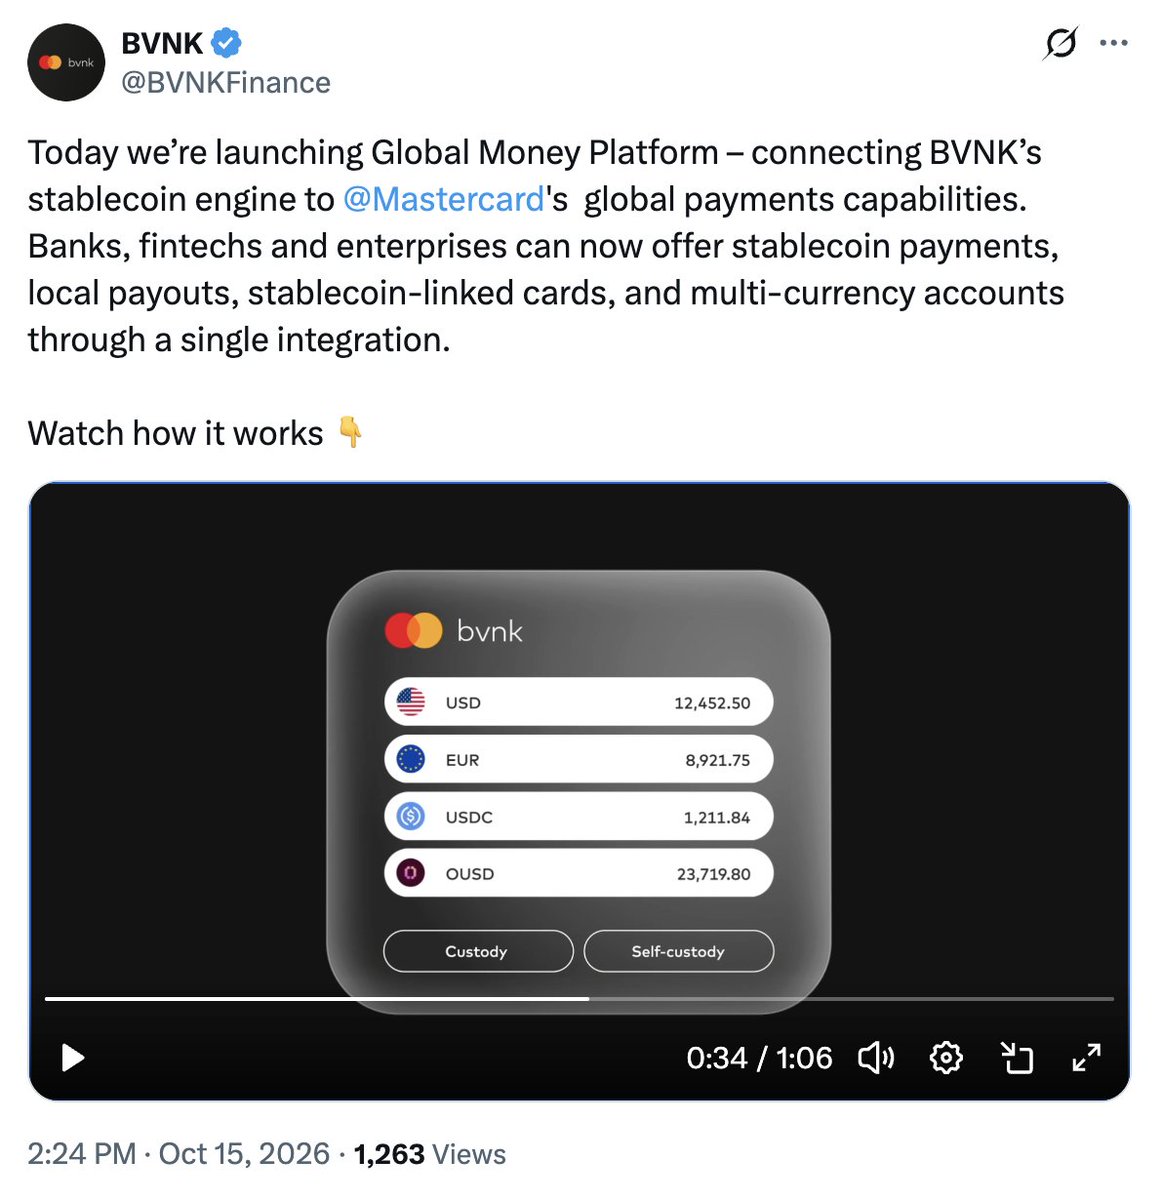
Today, Mastercard completed its acquisition of BVNK.
Together, we're helping customers connect digital and traditional forms of money through trusted infrastructure built for scale.
Learn more: https://t.co/8EhmFRcSDO
The Bank of Italy ran some tests comparing USDC vs traditional rails across 9 corridors. Verdict: "no systematic cost advantage" over traditional channels.
This conclusion is wrong, because their methodology is wrong, or at least outdated.
Read their cost table. The onchain leg averaged 0.4% of total cost (as low as 0.01%) and settled in under 15 minutes everywhere. Nearly everything else was fiat friction: funding fees, a 3.8% card surcharge, retail exchange spreads, withdrawal fees.
They tested the journey a CEX user faces today: bank transfer in, exchange trade, chain, exchange trade, bank transfer out. That architecture is exactly what onchain neobanks identified as the problem.
This is why virtual accounts/cards are becoming the ramp: fiat lands in your own named account, conversion happens inside the stack, exist via your self-custodial card. There are still fees, but they are much lower.
Hackathon Sponsor for the User Onboarding Track 📢
@idOS_network enables private and self-sovereign decentralized data storage, allowing us to share encrypted data with apps and businesses online — all while supporting compliance for regulated use cases.
https://t.co/Ks28tBYZa4
Over the last week we mapped 48 onchain neobanks: every licence, every module, every KYC check users go through.
90%+ of neobank products run on "rented" licences.
2 KYC providers verify almost all of them.
8 findings below. Full research in the article. AMA. 🧵
Japan's biggest card network is opening its rails to stablecoins.
JCB (140M users, 40M merchants) signed an MoU with @circle to explore USDC for cross-border payments and in-store purchases.
Everyday money onchain needs reusable identity.
JUST IN: @circle partners with JCB, Japan's largest card network, to bring $USDC to 40 million merchants across cross-border and everyday transactions.
Let's look at the data: supply is down, but transacted volume went up to record highs in the same period.
May-June, the US$ value of stablecoin transactions rose 63% to an ATH $1.78T (Visa/Allium).
Supply down, but real activity up - that's what shows real onchain usage.