@madmax3898 commentary in concall will be crucial. I m expecting bullish and clarity on future plans and pharmacy disinvestment. If they are able to maintain 30%+ EBIDTA margin growth, then good upside possible.
#ChandanHealthcareLimited
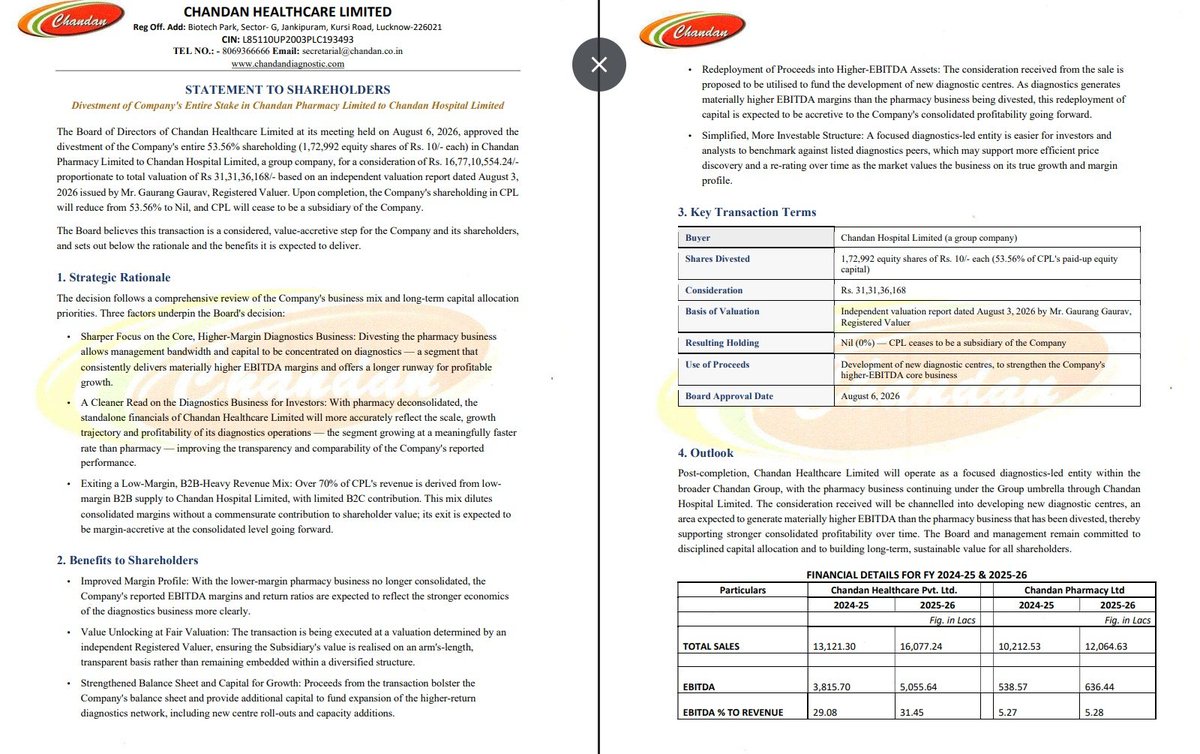
The Company announces strategic divestment of its stake in Chandan Pharmacy, sharpening its focus on the core, higher-margin diagnostics business.
Key Benefits:
• Improved consolidated margin profile
• Greater focus on diagnostics expansion
• Capital redeployment towards higher-EBITDA opportunities
• Simplified, diagnostics-focused business structure
#Diagnostics #Healthcare #BusinessUpdate #CorporateUpdate #IndianHealthcare
@RajStockWatch Going by Peer comparison, Chandan Healthcare should’ve been trading arnd 600-700 range. Due to CG issue & few negative publicity by Big HNIs, stock potential never discovered. Hwever, new SHP is promising. Hope CG issue resolves soon which nowhere connected to Chandan Healthcare
Chandan Healthcare Ltd | Q1 FY27 Operational Update | Decode
Company: North India focused integrated diagnostic services provider
Key Operational Metrics
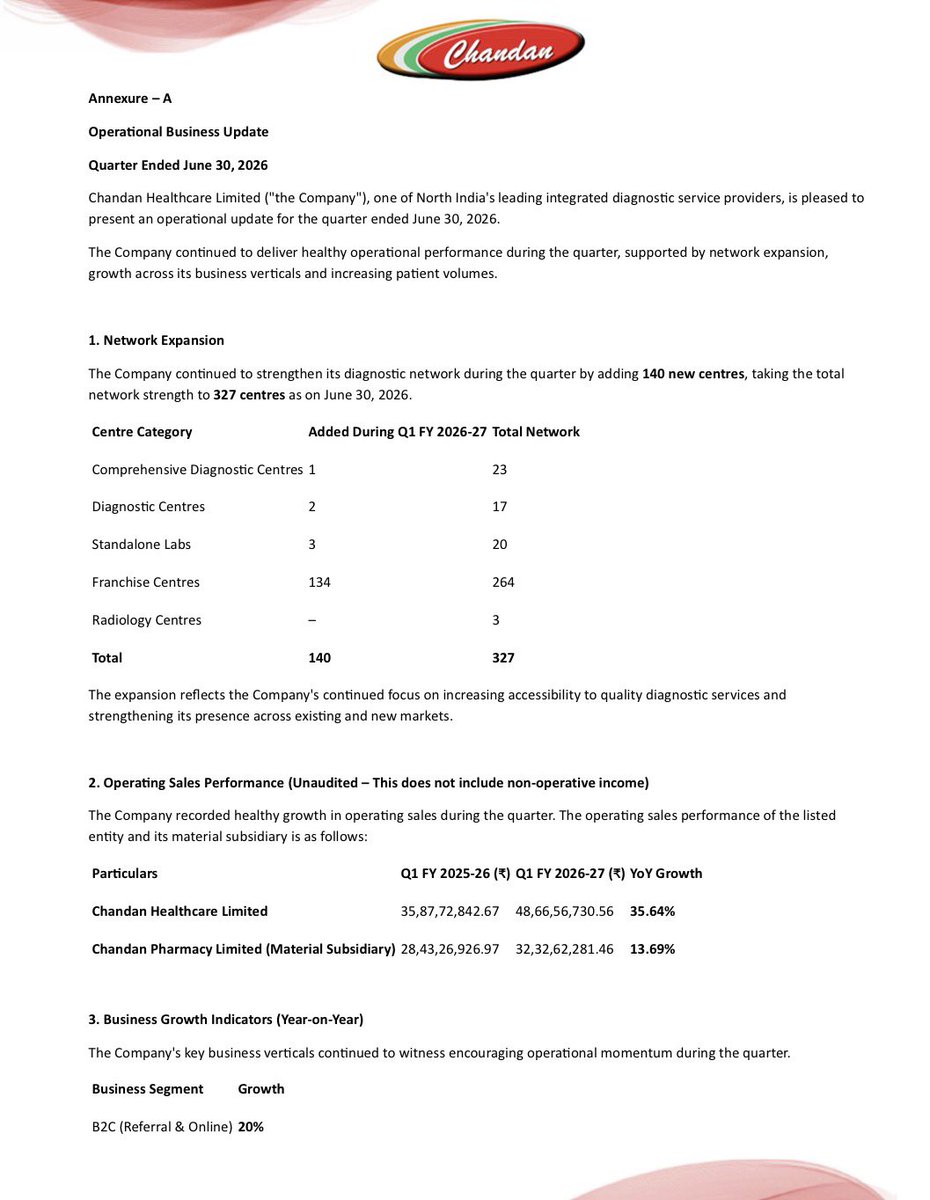
1. Network Expansion
Total network expanded from 187 to 327 centres, an addition of 140 centres in a single quarter.
Composition of additions:
Franchise Centres: 134
Standalone Labs: 3
Diagnostic Centres: 2
Comprehensive Diagnostic Centres: 1
The expansion is overwhelmingly franchise-led. Company-owned additions stand at just 6 centres.
2. Operating Sales (Unaudited, excludes non-operating income)
Chandan Healthcare Limited: ₹35.88 crore to ₹48.67 crore, up 35.64 percent YoY
Chandan Pharmacy Limited (material subsidiary): ₹28.43 crore to ₹32.33 crore, up 13.69 percent YoY
3. Segment Growth (YoY)
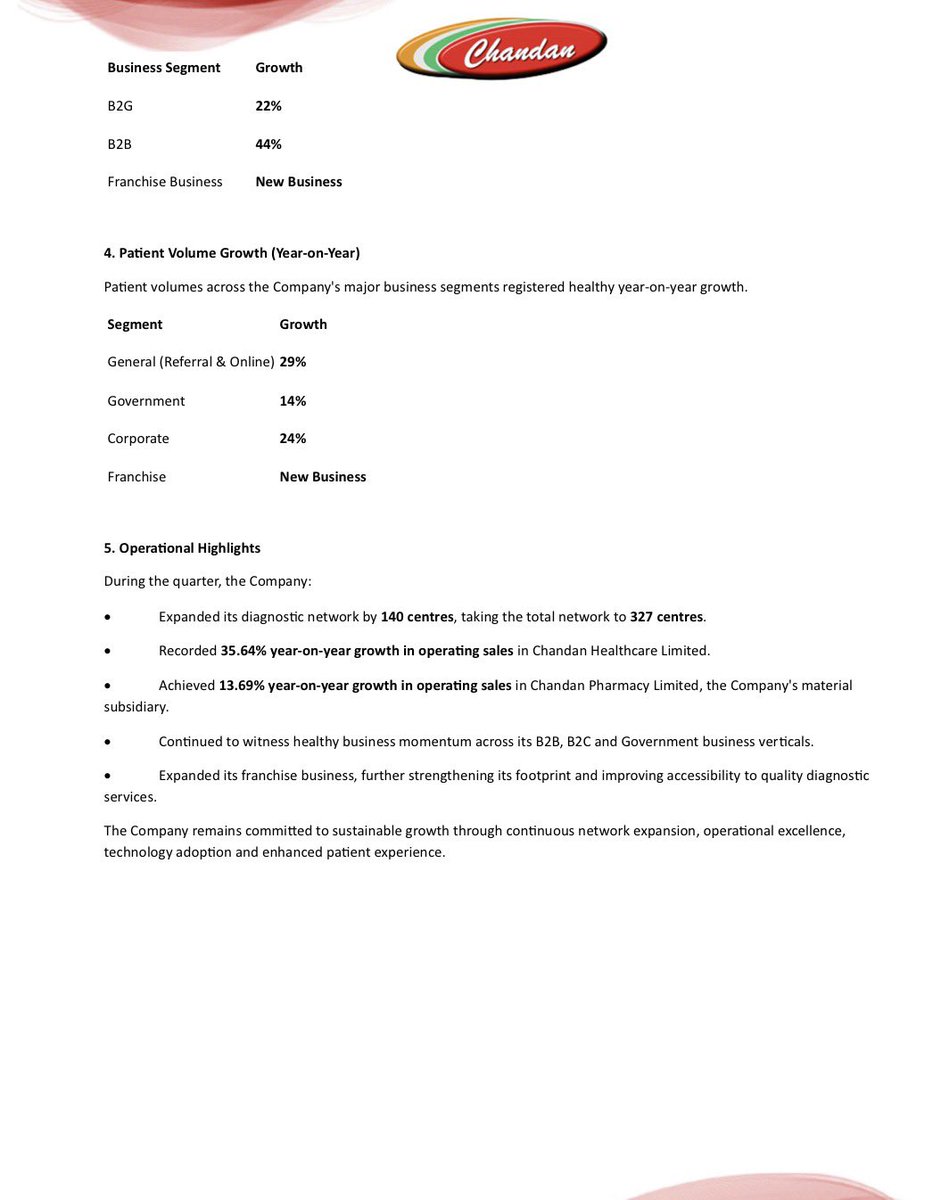
B2B: 44 percent
B2G: 22 percent
B2C (Referral and Online): 20 percent
4. Patient Volume Growth (YoY)
General (Referral and Online): 29 percent
Corporate: 24 percent
Government: 14 percent
Analytical View
The franchise-heavy expansion reflects an asset-light scaling strategy. Franchise centres require minimal company capex, act as collection points feeding hub laboratories, and allow rapid geographic penetration without stressing the balance sheet.
The 44 percent growth in B2B indicates institutional tie-ups are emerging as the primary growth engine, a segment that typically offers stronger volume visibility than walk-in retail.
Points of Caution
1. 134 franchise additions in one quarter is an aggressive pace. Franchise networks carry churn risk, and per-centre revenue contribution should be tracked over subsequent quarters.
2. This is an operational update, not financial results. Figures are unaudited and exclude non-operating income. Margins, working capital and profitability will only be visible when board-approved results are published.
3. Franchise-led revenue generally carries lower realisation per test than owned centres. Revenue growth and margin quality may diverge.
4. Government business (14 percent volume growth) carries receivable cycle risk, a recurring challenge across the diagnostics sector.
Assessment
Voluntary disclosure of detailed quarterly operational KPIs is a visibility-building signal. The operational narrative is strong on paper. The financial results for the quarter will be the true test of whether topline momentum translates into earnings quality.
Disclaimer: LNPR Capital is a SEBI Registered Research Analyst (RA No. INH000012953, BSE Enlistment No. 5843). This post is for educational and informational purposes only and does not constitute investment advice or a recommendation to buy or sell any security.
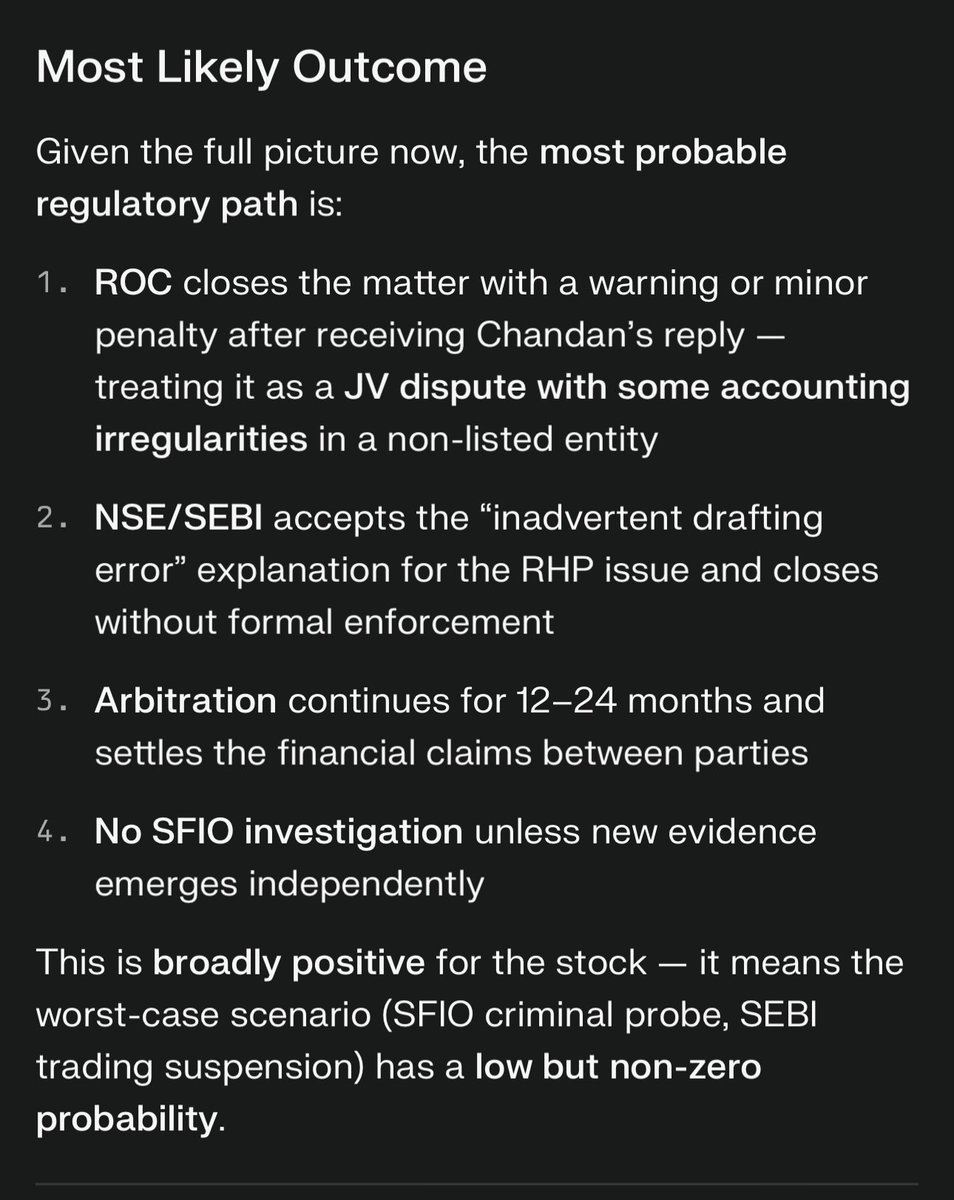
@vibhoreto Selective Quoting is dangerous. If you go thro the reply, you will find that DIMSL have to Pay Chandan not the other way around.
Chandan & Dayal Promoter made a MoU in 2021. Things didn’t work out. Chandan was shown the door but money invested by CIMSL was not refunded by DIMSL.
@RajStockWatch@Research_learn Uski saza hi toh stock ko mil rahi h… 358 se 206… Business wise as you rightly said its growing and continues to do so… still not getting PE close to their peers. Hopefully there are no more surprises left in the box.
📌 Chandan Healthcare Limited informed the exchange about the submission of a detailed reply in response to a complaint filed by Dayal Institute of Medical Sciences Limited regarding disclosures in the Red Herring Prospectus dated February 04, 2025. The company clarified that the description of shares as fully paid-up was an inadvertent clerical error and highlighted that the complaint is filed in the backdrop of active commercial disputes. #SME #CHANDAN ⚖️📄
@rajsum74 Dayal’s complaint is a promoter rivalry play… not related to chandan healthcare business… still wait and watch… they have to file response before june 19… 3 days trading session… Should resolve with proper justification ( as per their last concall).