this bull market feels like one where value investors actually get rewarded.
i'm the type of investor who finds a project i like and holds it for years. in past cycles, fundamentals and revenue were a meme.
that's changed with regulation passing and more projects producing real, sustainable revenue. holding high-quality projects should finally pay off.
so i built a fundamental value investing dashboard.
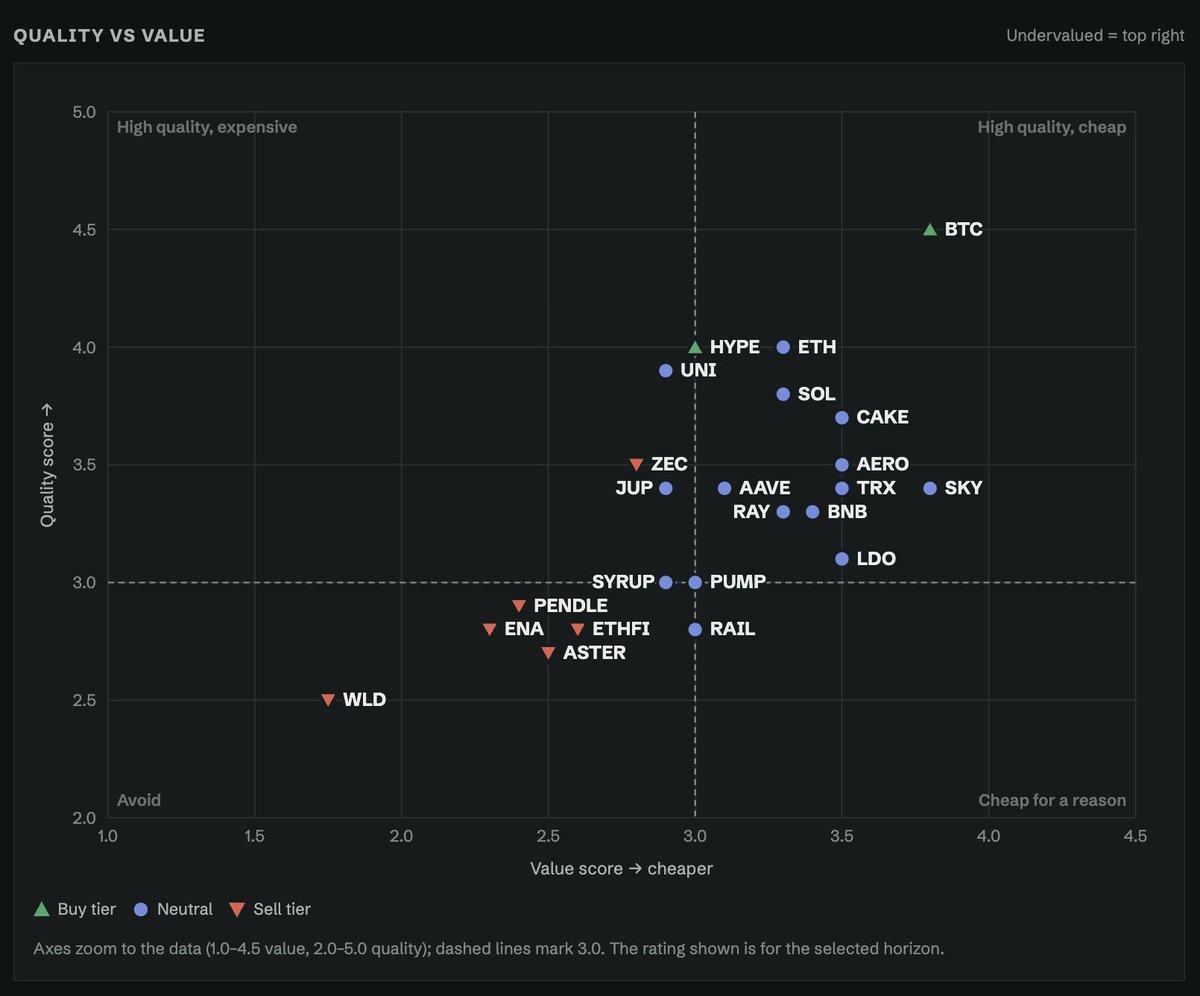
it ranks tokens mainly on tokenholder value accrual, then on product traction, team and governance, valuation, and dilution/supply.
each token gets bear/base/bull fair values, comps, a catalyst and unlock tracker, and technical analysis. it all rolls up into a quality vs value matrix.
of the 23 tokens in the first run, only $BTC and $HYPE make the buy tier on a 6-month time horizon.
it was built 100% on the @blockworks MCP: price, supply, unlocks, revenue, research, etc.
let me know if you'd want a live, interactive version, and which tokens i should add.
thanks for the continued replies and the constructive feedback.
the goal here isn't to FUD anyone's bag. it's to push for transparency and tokenholder value accrual, two things crypto has historically lacked. and it's important for people to disagree in public, bc that's how the conversation moves forward.
a few quick points, then i'll leave it here since we see some of this differently:
on the GPU math, that's fair - i used H100 prices, and if the fund buys B300s, the lab's share of hashrate would be smaller than i implied.
on disclosures, that's great to hear. if the team publishes its holdings and confirms the <5%, that answers a big part of my concern.
on the equity/token split, we'll have to disagree. at venice, the team decides whether cash flows go to tokenholders or equity. at pearl, there's no decision to make because nothing flows to tokenholders. that's the part i'd like to see change.
appreciate the debate ser & hope the team proves me wrong!
got some good pushback on my $PEARL fundraise post. here's my response to the main points, and how i think the team could fix them.
1) "this fundraise has been known for months."
no it hasn't. it's been a rumor, and an unverified one.
one of israel's largest business papers, @TheMarker, published the exact details yesterday ($55M in equity and a $75M GPU fund). that's the first time we’ve gotten actual numbers on it, and the team still hasn't confirmed it.
this goes back to transparency. why isn't the team announcing or confirming this? why do holders have to find out through rumors and business papers instead of directly from the team?
2) "pearl's whitepaper clearly states that difficulty was lowered for the first 10% of supply to fund operations."
the issue is again transparency.
that's 210M $PEARL, ~59% of today's circulating supply, or ~$380M at today's price.
we don't know how much of that the team mined, how much they still hold, or how much they've sold.
one reply says the team mined less than 5% of the network. maybe, but the team hasn't published anything that lets holders check that.
3) "they raised capital to build a GPU farm to add hashrate to their own network!"
yes, more hashrate is better. i agree.
but if that fund mines $PEARL (which it almost certainly will), it centralizes the network around the team even more than it already is.
the team ships the code and the upgrades. $75M buys roughly 2,500-3,000 H100s, which could make the lab one of the largest miners on pearl.
as someone put it, "whoever controls the majority of the network's hashrate ultimately decides which chain gets secured..."
so we're comfortable with the dev controlling a growing chunk of the hashrate, without disclosing how much? that takes away a lot of the credible neutrality and decentralization that make blockchains, and especially SoV assets, valuable.
4) "trying to accrue value to the token would invite additional valuation frameworks, which can only result in a lower valuation ceiling."
i disagree. $PEARL is a lot less credibly neutral than other PoW assets like bitcoin, zcash, or even monero. it's also missing what monetary assets need:
> low inflation (supply grows ~85% this year)
> deep liquidity (~$8M of daily volume)
> transparency from the team (undisclosed holdings + fundraise)
> years of evidence that it works (it's 6 months old)
so right now, the SoV case is weak, and a second source of value would help, not hurt.
look at ethereum. it's valued as an infrastructure token (it returns value to holders thru staking and burns) and as a monetary asset (it's the main collateral across DeFi, it's the gas currency for ethereum and most of its L2s, and ~$18B of it sits in spot ETFs).
a claim on value accrual gives a token fundamental support. monetary premium is the most fragile part of a token's price. when zcash's orchard bug was disclosed in may, $ZEC fell ~50% in two days even though nothing about its fundamentals changed.
5) “there is no equity/token split. pearl research labs is an equity business AI lab, completely separate from the token."
this isn't accurate.
they are not completely separate. the lab ships the code, the early low-difficulty window was set up to fund its operations, and its GPU fund will likely mine $PEARL.
and the part that is separate is the part that makes money. that's what an equity/token split is. here is the test i use:
> does the lab make money without the token? yes, it sells inference in USD.
> does the token share in that revenue? no.
> are any buybacks programmatic? no.
> could the lab keep growing while $PEARL falls? yes.
so the business and the token have to be valued separately.
if $PEARL went to zero tomorrow, the lab would lose its mining subsidy, but it could keep selling inference on its own GPUs.
the counter is that the team holds $PEARL, so their incentives are aligned with holders. but that only goes so far.
the team also owns equity in the lab, and so do VCs who may not hold any $PEARL. when the token and the business want different things, like whether inference gets sold for USD or $PEARL, the lab will answer to its equity holders. and we still don't know how much $PEARL the team holds, whether any of it is locked, or how much they've sold.
there are ways to fix this though:
1) TRANSPARENCY. disclose how much $PEARL the team and investors mined and hold, how much they've sold, who invested, and what share of the hashrate the lab controls. for a SoV asset, this is the most important thing a team can provide. it's why @blockworks has a token transparency framework.
2) FIX TOKENOMICS. accept $PEARL for inference, and burn the $PEARL that comes in instead of selling it. that adds demand for the token and helps offset miner selling. (i know. i know. "this is a SoV token, it doesn't need utility bro!!" but as i outlined above, it can/should have more than one source of value).
3) USE THE REVENUE FOR THE TOKEN, NOT THE TEAM'S AND VCs' POCKETS. most or all of the lab's inference profit should go to buying back and burning $PEARL. make it a fixed policy with burns sent to a published onchain address, not a verbal promise or something left to discretion.
4) CAP THE LAB'S HASHRATE. commit to keeping the lab's own mining under a set share of the network, and report it publicly.
5) TIME. supply growth drops to ~33% next year, ~18% the year after, and ~12% after that. by then the team could prove it's a credibly neutral dev, and $PEARL could have a real case as a SoV. bitcoin is 17 years old. zcash is 10. $PEARL is 6 months.
if the team addresses the first four, i'll revisit my bearish view.
not officially confirmed, but @TheMarker, israel's main business paper, is reporting that @prlnet's lab raised $130M from lightspeed, ribbit capital, and square peg.
$55M in equity and $75M for a fund to build out GPU infrastructure.
ribbit and lightspeed are also named as pearl backers on its profile in greenfield partners' disruptors 60 list.
if this is real, the $PEARL bear case gets a lot worse. here's why:
1) $PEARL traded on a "no VCs, fair launch" story.
pearl's code doesn't allocate tokens to founders or investors, and that part is probably still true. but the lab behind pearl is reportedly VC-backed, and nobody corrected the narrative while it pumped.
2) the value goes to the equity, not the token.
the lab sells inference and gets paid in USD, and the VCs own the lab. $PEARL holders don't get any of that revenue, just diluted by new supply.
so the investors can do well even if $PEARL goes to zero.
3) it goes against the "sovereignless bitcoin" pitch.
part of bitcoin's monetary premium is that no company controls it. pearl's upgrades are drafted by a VC-backed lab, including the FP8 fork that would tie mining more closely to inference, the same business the lab sells.
4) the $75M GPU fund.
we don't know if those GPUs mine $PEARL. if they do, the company is collecting a share of ~85% supply growth this year, on top of whatever insiders mined early.
remember that about 1/3 of today's supply was mined in the first 6 days.
5) zcash had investors too (20% of its early block rewards went to founders and investors) but that was public from day 1. everyone knew who got paid and how much.
pearl hasn't disclosed any of that.
holders deserve to know:
> who invested
> whether any investors or insiders hold $PEARL
> whether the GPU fund mines $PEARL
a fair launch shouldn't need a newspaper to tell you who's behind it.
i was a $PEARL bear on friday. i'm a bigger one now.
המעבדה שרוצה להוזיל את ה-AI - עם קריפטו
בלי הכרזה רשמית, מעבדת המחקר התל אביבית פרל גייסה 120 מיליון דולר ממשקיעים כמו לייטספיד, Ribbit Capital וסקוור פג.
מעבדת המחקר מציגה צוות עם קורות מדעיים מרשימים: המנכ״ל פרופ' עמרי וינשטיין, בעל דוקטורט במדעי המחשב מפרינסטון ויוצא אנבידיה ודסי; וסמנכ״ל הטכנולוגיות פרופ' אילן קומרגודסקי, עם דוקטרט במכון ויצמן, מרצה באוניברסיטה העברית וחוקר לשעבר ב-NTT. אליהם הצטרף היזם עידן שוגרמן.
לפרל יש צד ״קונבנציונלי״ שעוסק בייעול השימוש ב-GPU למשימות AI, אבל זה רק חלק מהחזון השאפתני הרבה יותר של החברה - להוזיל את עלויות ה-AI דרך שימוש בקריפטו.
פרל מתבססת על עבודה שפרסמו וינשטיין קומרגודסקי אשתקד, שמצאה דרך לשלב בין כריית מטבעות קריפטו לבין ביצוע חישובי AI. העבודה מצאה דרך בה משתמשים יכולים לבצע חישובי AI ללקוחות ובמקביל לבצע אבטחה של רשת הקריפטו, בלי לבזבז אנרגיה עודפת משמעותית . על העיקרון הזה בנויה רשת הקריפטו פרל, שהושקה באפריל על בסיס פרוטוקול שפיתחה המעבדה התל אביבית.
פרל היא ללא ספק אחד הסיפורים החמים ביותר בעולם הקריפטו כרגע והמטבע פרל עלה ב-500% בשלושת החודשים האחרונים. היא חתמה במאי הסכם עם הענן האמריקאי Together AI שמציע ללקוחות הנחה של 25% על משימות AI שמבוצעות על מודל משקולות פתוחים של גוגל, בתמורה לזה שהחברה כורה במקביל מטבעות פרל.
אבל יש גם סימני שאלה גדולים ביחס לחזון. המרכזי בהם הוא שרוב הפעילות במטבע פרל שייכת עדיין לכורים מתוחכמים שמריצים חישובי סרק על GPU כדי לקבל את המטבע.
האם יש לזה סיכוי?
הכתבה:
https://t.co/R1jksS0KIB
$PEARL isn't meant to be exposure to the lab, and i'm not arguing it should be.
but "completely separate from the token" isn’t right either.
per the whitepaper, difficulty was lowered for the first 10% of supply to fund operations. that's 210M $PEARL, ~59% of today's circulating supply.
the lab also still drafts the protocol upgrades, and may be adding a $75M GPU fleet that mines.
blockstream and lightning labs were built on bitcoin years after launch. neither was funded by bitcoin's issuance.
i don't have an issue with companies building on pearl. my issue is the lack of transparency. i want to know how much $PEARL the lab mined/mines, holds, and has sold.
@gaintheory_@brezshares@TheMarker@prlnet sure, $BTC doesn't have a claim on revenue either.
but then the whole value of pearl is the monetary premium, and that depends on knowing the supply and who controls it.
right now we don't know how much the team holds or whether the $75M GPU fund mines.
@brezshares@TheMarker@prlnet satoshi mined early too, but he disappeared, never moved his coins, and stopped writing the code.
if he had lowered difficulty to fund a company, raised VC for it, and kept writing bitcoin's upgrades, people would have a lot of questions.
the issue is transparency.
the whitepaper says difficulty was lowered for the first 10% of supply to fund operations. that's 210M $PEARL, ~59% of today's circulating supply.
but we don't know how much of that the team mined, how much they still hold, or how much they've sold.
the $55M equity raise and $75M GPU fund weren't announced either. they came out through a newspaper.
and if hashrate decides which chain gets secured, a $75M GPU fund gives the lab more control over the network, not less.
holders shouldn't have to piece this together from the whitepaper and press reports.
yup and i said so in point 1. the token launch itself can be fair.
that's the problem tho. it's another equity/token split.
the lab owns the inference business and the VCs own the lab. $PEARL holders own a token with no claim on that revenue.
we've seen how this goes. the equity captures the value and the token holders get rekt.
early $ZEC shows what high inflation does to holders, even when the network is growing.
in its first four months, zcash's market cap grew ~8x, from ~$3M to ~$22M.
over the same stretch, price fell 91%, from $328 to $30, because supply grew ~84x.
most of that came from zcash launching with a tiny supply, so $PEARL isn't there yet.
Pearl's supply grows ~85% over the next year, not 84x. but new supply still has to find buyers before price can go up.
i'm sure early ZEC holders had the same "but bitcoin had high inflation" arguments too.
then we agree on more than i thought. this is a monetary premium bet, not a compute bet.
the clouds hearing about pearl are the supply side. they're the ones getting paid in new $PEARL.
the crowd that took bitcoin to $2.5T came once supply growth was low. the high-inflation buyers paid under $10M. $PEARL is growing supply ~85% this year at ~$768M.
i think they wait for issuance to come down first.
appreciate the thoughtful response ser. going point by point:
1) fair, not 100% of emissions get sold. "a full market cap of new buying" is the worst case.
but even if only half gets sold, that's ~$1.1M/day of sell pressure, about 13% of daily volume, and ~$327M over the next year against a ~$768M market cap.
the precedent is different too. bitcoin miners in 2020/21 owned their machines. most pearl hashrate today is rented cloud GPUs, and renters have USD bills to pay.
2) i agree the team's lead on the kernel is real. but that's a moat for pearl research labs, which sells inference in USD. it's not clear (yet) how that lead accrues to $PEARL holders.
also id argue that right now the network effect is mostly miners following the subsidy, and that follows whichever chain pays best.
3) honest GPU operators have every reason not to attack. the risk is someone who owns nothing renting compute for a few hours and handing it back at full value. with ASICs, an attacker has to buy a fleet that loses its value if the attack works.
today the gap is also ~$36.6M/day of bitcoin subsidy vs ~$2.2M/day for pearl.
4) i'd flip this one. ZEC's current run came with ~4% annual inflation, after years of miner distribution. the alt SoV bid showed up once emissions were small.
pearl is asking the market to absorb ~85% supply growth this year. the "why now" can be right and still get diluted away.
no disagreement that the narrative is strong. that's why i said it can run. i just think the price is already paying for a lot of it.
$PEARL miners add ~$2.2M of new supply every day.
average daily volume over the last 10 days is ~$8.5M, so newly mined coins are worth roughly 25-30% of daily trading.
and most mining today runs on rented GPUs from clouds, so those miners have bills to pay.
over the next year, that's ~$654M of issuance against a ~$768M market cap.
the market has to find almost a full market cap of new buying just to hold the price.
the most common pushback on the $PEARL bear case is "bitcoin inflated like this too. would you not have bought it in 2011?"
bitcoin's supply did grow 85%+ a year until aug 2011. but for 40 of those 58 weeks, it was worth under $10M.
$PEARL is inflating at that same ~85% rate at a ~$768M market cap and a ~$4.6B FDV, 6 months in.
the early bitcoin trade worked because nobody knew how to price it. markets price new crypto much faster now, so that mispricing is already gone.