$INGN
Inogen - A turd in every glass served from the punchbowl of Q326 Inogen results
Wow, what an absolutely terrible quarter, one of the worst I recall ever seeing. CEO apparently but deservedly canned, no earnings call Q&A from the new but uncourageous CEO who was COO for Q3, no mention of new products. As I started digesting the release my reaction was the international decline in Q3 was the "turd in the punchbowl" but I started finding much more. They pretty much served a turd in every glass. Nice going $INGN. I sold some shares going into the release but now wished I had sold more.
So what were the other floaters?
1. Moving onto the third CEO in 5 years
2. They did not sell their biggest declining business segment after all. Yes they sold the rental business but the international segment went from 15% growth in Q2 to down 9% in just one quarter. That makes international the largest decliner. No mention of this in the Q3 outlook in early August, over a month into Q3.
3. What kind of growth I wondered before seeing the results will the continuing operations have? Selling rental made sense after all. Well here it is, the biggest turd in the punchbowl. Q4 revenue expectations of $65 - $68 million, a midpoint sequential decline of 14% in one quarter from Q3 26 results. That requires a chew.
4. Gross margin down 44.1% from 45.7%
5. AUP in a steady decline, $1487 in Q3 vs $1538 for the 26 YTD and vs $1638 for the 25 YTD.
6. Goodwill impairment of $10 million
7. Legal settlement of nearly $2 million
8. Share repurchases YTD of 1.8mm shares are not even reducing the WA share count - too many stock awards to under-performing executives.
9. They sold a turnaround story with the 9/30 rental sale announcement and saved all the turds for the 11/5 earnings release.
10. Inogen said on 9/30/26: "Inogen expects the transactions to increase both the revenue growth rate and adjusted operating income." One month later they reveal growth rates in both metrics were down for Q3 and will be down for Q4 and probably well into 2027.
Where is the mouthwash?
Inogen - A turd in every glass served from the punchbowl of Q326 Inogen results
Wow, what an absolutely terrible quarter, one of the worst I recall ever seeing. CEO apparently but deservedly canned, no earnings call Q&A from the new but uncourageous CEO who was COO for Q3, no mention of new products. As I started digesting the release my reaction was the international decline in Q3 was the "turd in the punchbowl" but I started finding much more. They pretty much served a turd in every glass. Nice going $INGN. I sold some shares going into the release but now wished I had sold more.
So what were the other floaters?
1. Moving onto the third CEO in 5 years
2. They did not sell their biggest declining business segment after all. Yes they sold the rental business but the international segment went from 15% growth in Q2 to down 9% in just one quarter. That makes international the largest decliner. No mention of this in the Q3 outlook in early August, over a month into Q3.
3. What kind of growth I wondered before seeing the results will the continuing operations have? Selling rental made sense after all. Well here it is, the biggest turd in the punchbowl. Q4 revenue expectations of $65 - $68 million, a midpoint sequential decline of 14% in one quarter from Q3 26 results. That requires a chew.
4. Gross margin down 44.1% from 45.7%
5. AUP in a steady decline, $1487 in Q3 vs $1538 for the 26 YTD and vs $1638 for the 25 YTD.
6. Goodwill impairment of $10 million
7. Legal settlement of nearly $2 million
8. Share repurchases YTD of 1.8mm shares are not even reducing the WA share count - too many stock awards to under-performing executives.
9. They sold a turnaround story with the 9/30 rental sale announcement and saved all the turds for the 11/5 earnings release.
10. Inogen said on 9/30/26: "Inogen expects the transactions to increase both the revenue growth rate and adjusted operating income." One month later they reveal growth rates in both metrics were down for Q3 and will be down for Q4 and probably well into 2027.
Where is the mouthwash?
I think it is a very smart move on management's part and to get it done by 9/30 to impact Q3 reporting. Sales would be up 5.6% in the first half of 2026 without the third year of declines from rentals. Discontinued ops treatment requires recasting the P/L showing better overall growth and improved profitability for the last three years which is important for the turnaround story.
Their remaining $37.5mm stock repurchase would retire 24% of o/s shares at current stock price but I bet they already used a chunk of this in Q3 which will be reported in about a month with Q3 results.
More significant is their TAM is up 9X in the last 12 months (Q2'26 transcript) to $3.4b. While their new products are very early in their growth, it diversifies the business and adds to its appeal. $INGN should start showing up on the radar for more investors and institutions. I'm buying.
@ColeMacro Really well constructed letter, thanks for taking the time to carefully construct it and share it. I think MSCI will choose to stay as relevant as possible to today’s financial markets and not continue down the exclusion path for DAT companies. $MSTR $ASST
$BROS is a clear buy at $38.50. Company has doubled revenue and EBITDA run rate from Q124 with only a 40% increase in stores and yet the stock is only up 16% over this time period. Traffic has held up well in the most recent quarter, in-line with the last 10 quarters with a median performance. There are concerns about MCD encroaching in their space which I believe are overblown, $MCD has its plate full, stock down almost 6% today after Investor Day and 31% from its 52 week high.
$CAVA is a screaming buy here, it is a big long for me. Restaurant stocks in general and CAVA especially are down way too much over inflation fears, gas prices, old food safety concerns not directly related to CAVA etc.. The reality is people have to eat and want to eat healthy and tasty so CAVA will continue to do well. In fact, if one looks at the last three big increases in US gas prices CAVA does great, often even better, in large part because people trade down from casual dining to CAVA and continue to move from less healthy dining options to CAVA. See the following last three big US gas price increases:
#1 12/21 to 6/22, gas $3.14 to $4.84 or 54% in 6 months, CAVA’s SSS averaged 7.9% for Q1-Q321
#2 12/22 to 8/23, $2.97 to $3.75 or 26% in 8 months, CAVA’s SSS averaged 19.7% for 2023
#3 1/26 to 5/26, $2.68 to $4.35 or 62% in 4 months, CAVA’s SSS averaged 9.35% for Q1 and Q2 of 2026, up significantly from .5% in Q425
Yes average ticket is some of the SSS but a small portion, most of CAVA's SSS is traffic driven.
The market has overreacted with CAVA down 7% YTD and down 44% from the high in 4/26. (CP $54.82 at time of post). CAVA is a multiyear grower. Yes one needs to still pay up for quality but it will be worth it in my view.
Source for gas prices: https://t.co/FJhGyo87Or
This is a good post. I observe that while 2025 was an off year for the company it is expected to put up about 30% revenue growth for 2024 and 2026 (estimated). Much higher that the posts' assumption of 20-25%. Actual growth was 32.5% for 24, 22.4% for 25 and analysts project 27.6% for 26. Note the company usually beats analyst estimates (Q126 was 32.2% and Q2 was 31.3%). Q3 will likely be lower due to the salad scare impacting others in space but the the stock is a screaming buy here.
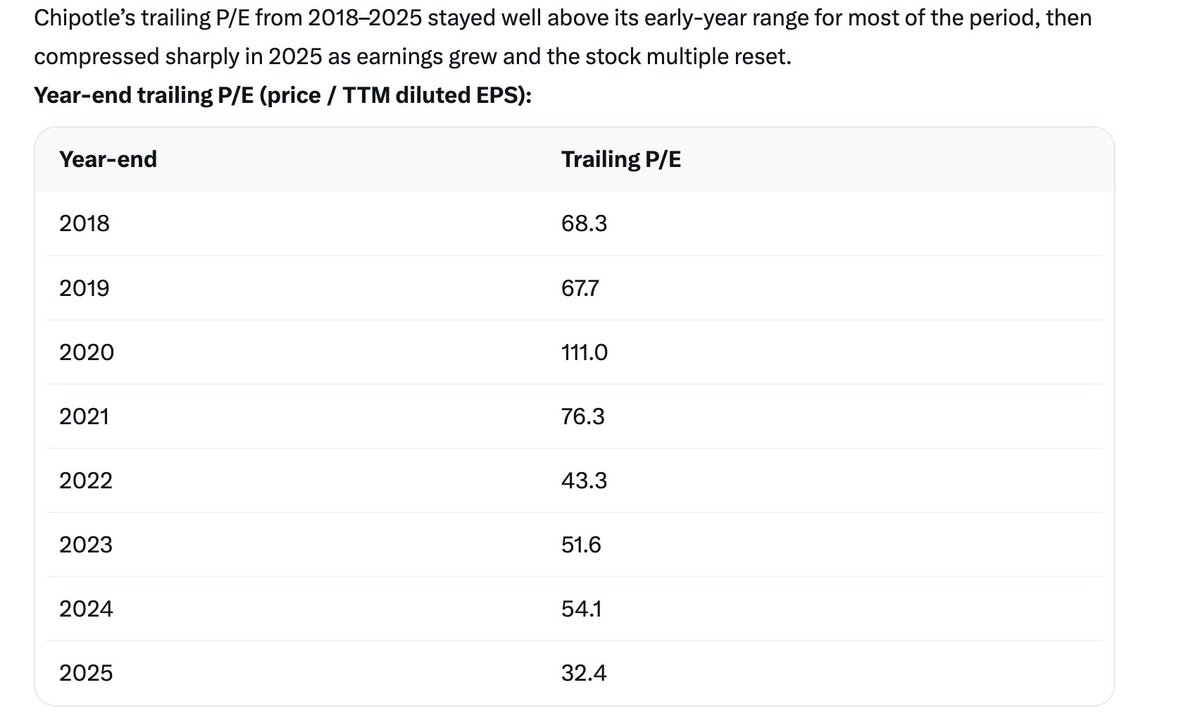
@RealJimChanos A much better comparison is CMG which went from $7 to $63 from 2018 to 2025 and carried a high PE during most of this time. Knee caps are beneath you. $CAVA
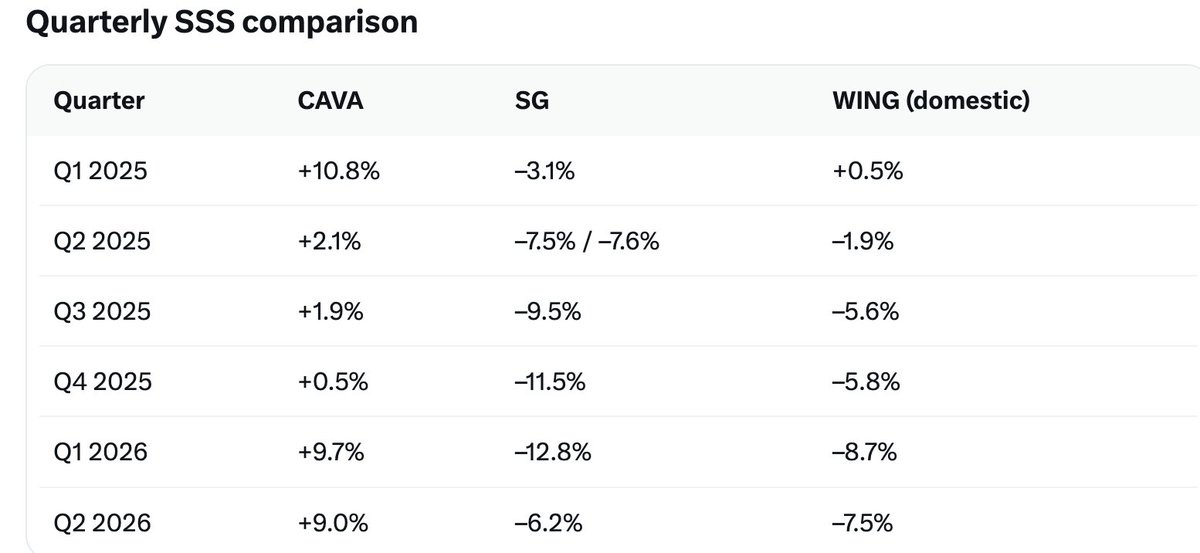
@RealJimChanos OK Jim, that's playing dirty. SG and WING are not in the same class of restaurant stocks. Here are SSS for the three stocks. You know Wall Street pays for growth. Don't be a Tonya Harding. If you are short $CAVA just say it.
I agree with those that this suit is a nothing burger - their SSS guidance for 2025 issued with their Q424 release in late 2/25 was 6-8% for the year after a 13.4% SSS in Q4. They did not comment on 2025 growth formally until then. Yes growth came in below that guidance at 4% but still better than nearly all other restaurant companies, the economy softened in 25, there is no protection from that, lawsuit or otherwise. Also of note they opened 72 stores in 2025 vs this same guidance of 64 and were within range on their rest. level margin 24.6% vs 25.0% (midpoint). Teamsters pension manager should have scaled into a stock that had gotten ahead of itself due much more to Wall Street. $CAVA
@ZiadMDaoud Trump is smarter than "we are about out of bullets", it is a head fake. Plus it takes two to Tango and this dance is far from over by the Iranians. Does it really matter if both bombs and boats are stationary? #OOTT
@MoloWarMonitor Trump is smarter than "we are about out of bullets", it is a head fake. Plus it takes two to Tango and this dance is far from over by the Iranians. Does it really matter if both bombs and boats are stationary? #OOTT
Thanks, so help me understand the X-axis. The EIA has reported since the start of the war, non-SPR inventories are down about 50mm barrels (SPR down another 100mm). Why does your X-axis show what appears to be a build in inventory of the same amount? What is your normalized stocks compared to to arrive at a build of 50mm or what are the units of the X-axis?
This is like saying you’re on a two engine jet and both engines went out and can’t be restarted for at least an hour. You’re at 40,000 feet altitude and you’ve only lost 2000 feet in the last three minutes and you’re saying you’re not gonna worry about it until the low elevation alarms go off at 1000 feet. It’s about inevitability not cushion. #OOTT