You wouldn't believe how easy it is to sleep on a multi-million position once you risked-off 50% early on.
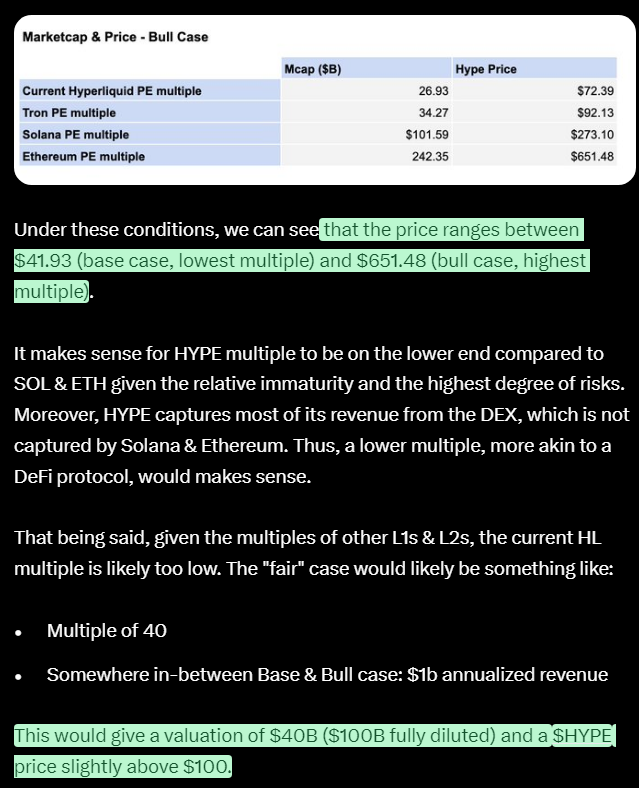
My $HYPE target for this cycle has been $25 ($25B FDV), as I believe it takes time post-TGE for a project to establish its position: tokens have to exchange hands from airdrop farmers to long-term holders, the market has to digest the presented information and draw comparisons to other projects through metrics, etc.
This target has been hit today, but I didn't risk off another 10% as I initially intended to.
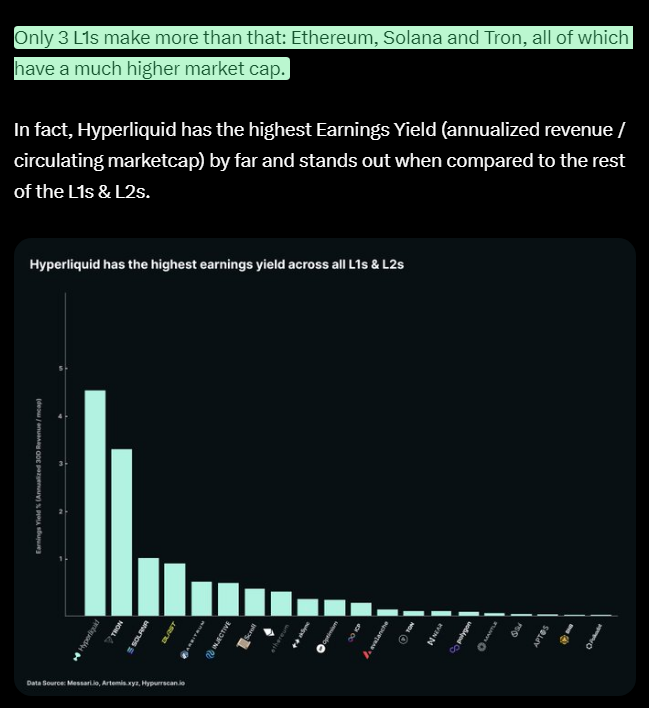
IMO Hyperliquid is a lot closer to Ethereum, Solana, and BNB than any other project that currently exists on the market, hence the current premium (24B).
The community/early adopters literally own the majority of the circulating supply, and history has been written through the greatest airdrop wealth generation event since inception —— yet price is up-only.
With Hyperliquid, you get a combination of:
▫️ Ultrasound Money - Burn + Fixed Supply
▫️ Money Printer - Platform fees (Perps + Spot), Auctions (akin to Binance Listings), EVM Fees (soon)
▫️ Complete decentralization by distributing 1/3 of its supply to early adopters
▫️ Founders who are already rich, hence they didn't have to take a single penny from VCs while redistributing revenue through HLP (maybe through $HYPE staking soon?)
▫️ A cult that has been formed by rewarding early adopters adequately and making them rich in the process
▫️ An incredible flywheel by reserving 38.88% of the ENTIRE supply for future emissions and community rewards. Keep in mind that this is on top of the already distributed 31% Airdrop #1 supply. The community will literally own 70% of the $HYPE supply.
This is a lot bigger and truly one of a kind —— give me staking so I can lock up my remaining $2.6M bag and only touch the passive income through staking rewards.
The market has been longing for a project that fully embodies everything Crypto stands for since Ethereum launched, and very likely has now found it through Hyperliquid.
Hyperliquid.
PERSONAL UPDATE - I’m starting a crypto media company
BUT before we get into that, thank you to everyone reading this for following and supporting me all these years. No man is an island.
Over the last 2+ years, I’ve interviewed nearly every DePIN founder out there on @builtnpublicpod along with @DAnconia_Crypto@MoneroMahesh at @EV3ventures.
Over the last year, we’ve really stepped up the quantity and quality of episodes and I’ve realized I really enjoy the work. I like being analytical AND creative - using my left and right brain at the same time.
When thinking back to who my parents are and how they raised me, this makes a ton of sense. My mom danced ballet on Broadway and is a sought-after commercial actor. My dad is one of the smartest, most logical, legal and business brains I know. Big thanks to them here for their support on this and every journey I’ve taken.
Even though I’ve only recently realized how much I like doing media work, I’ve known crypto (esp. DePIN) is the topic I would most like to cover for years now. And you’ve seen me do it.
So, as to what specifically I’ll be doing:
Proof of Coverage (@PoC__media) is the company I’m founding. It’ll have a podcast network consisting of @builtnpublicpod (founder interview pod) and @allocators_pod (investor interview pod) to start. I’ll do consulting/advisory, help projects get exposure via sponsorships, and run events and other media company things.
Hope you’re ready to see a lot more of me (and your favorite founders and investors) on your timeline soon 😉.
Some of the content will resonate with you, some won’t, I just ask that you share the stuff that does. Listens and views will be the primary metrics by which I solicit feedback and decide which formats, guests, sectors, etc to produce or cover. My DMs are always open for comments, guest or topic ideas, or just to connect.
Thanks again for your support. I’m excited to build this with you, for you, and in public. Media is currently undervalued in crypto. Let’s change that.
- Connor
Big shoutout to @RichhomieconE who announced today he’ll be working with the @iotex_io team.
Got to work a lot with Connor during his days at Hexagon, he’s one of the brightest minds the DePIN space has to offer.
The gov’t has about 48 hours to fix a-soon-to-be-irreversible mistake. By allowing @SVB_Financial to fail without protecting all depositors, the world has woken up to what an uninsured deposit is — an unsecured illiquid claim on a failed bank. Absent @jpmorgan@citi or @BankofAmerica acquiring SVB before the open on Monday, a prospect I believe to be unlikely, or the gov’t guaranteeing all of SVB’s deposits, the giant sucking sound you will hear will be the withdrawal of substantially all uninsured deposits from all but the ‘systemically important banks’ (SIBs). These funds will be transferred to the SIBs, US Treasury (UST) money market funds and short-term UST. There is already pressure to transfer cash to short-term UST and UST money market accounts due to the substantially higher yields available on risk-free UST vs. bank deposits. These withdrawals will drain liquidity from community, regional and other banks and begin the destruction of these important institutions. The increased demand for short-term UST will drive short rates lower complicating the @federalreserve’s efforts to raise rates to slow the economy. Already thousands of the fastest growing, most innovative venture-backed companies in the U.S. will begin to fail to make payroll next week. Had the gov’t stepped in on Friday to guarantee SVB’s deposits (in exchange for penny warrants which would have wiped out the substantial majority of its equity value) this could have been avoided and SVB’s 40-year franchise value could have been preserved and transferred to a new owner in exchange for an equity injection. We would have been open to participating. This approach would have minimized the risk of any gov’t losses, and created the potential for substantial profits from the rescue. Instead, I think it is now unlikely any buyer will emerge to acquire the failed bank. The gov’t’s approach has guaranteed that more risk will be concentrated in the SIBs at the expense of other banks, which itself creates more systemic risk. For those who make the case that depositors be damned as it would create moral hazard to save them, consider the feasibility of a world where each depositor must do their own credit assessment of the bank they choose to bank with. I am a pretty sophisticated financial analyst and I find most banks to be a black box despite the 1,000s of pages of @SECGov filings available on each bank. SVB’s senior management made a basic mistake. They invested short-term deposits in longer-term, fixed-rate assets. Thereafter short-term rates went up and a bank run ensued. Senior management screwed up and they should lose their jobs. The @FDICgov and OCC also screwed up. It is their job to monitor our banking system for risk and SVB should have been high on their watch list with more than $200B of assets and $170B of deposits from business borrowers in effectively the same industry. The FDIC’s and OCC’s failure to do their jobs should not be allowed to cause the destruction of 1,000s of our nation’s highest potential and highest growth businesses (and the resulting losses of 10s of 1,000s of jobs for some of our most talented younger generation) while also permanently impairing our community and regional banks’ access to low-cost deposits. This administration is particularly opposed to concentrations of power. Ironically, its approach to SVB’s failure guarantees duopolistic banking risk concentration in a handful of SIBs. My back-of-the envelope review of SVB’s balance sheet suggests that even in a liquidation, depositors should eventually get back about 98% of their deposits, but eventually is too long when you have payroll to meet next week. So even without assigning any franchise value to SVB, the cost of a gov’t guarantee of SVB deposits would be minimal. On the other hand, the unintended consequences of the gov’t’s failure to guarantee SVB deposits are vast and profound and need to be considered and addressed before Monday. Otherwise, watch out below.
understand how a token could build intrinsic value over time. Two examples may help to explicate my view: @helium created a global Wi-Fi network used by @limebike and others to track devices globally as well as for other uses which benefit by access to global Wi-Fi networks.
Apple has raised the price of its music and video streaming services, in the latest example of streaming products getting more expensive in recent months https://t.co/HaeD3O9EgY
Big Problem considering that 70-80% of Home Purchases are financed with a Mortgage.
High Rates + Declining Housing Market has Buyers on ice. It's a total Boycott of the Housing Market.
Prices need to come down substantially to entice buyers back in.
Europe’s long-standing gambit on cheap Russian gas could backfire into one of the worst energy crises on the continent since the 1970s.
Here’s what to expect with the upcoming winter. 🧵 https://t.co/Bunxq04YnB