Indexing has fundamentally changed how investors access public equities. Yet broad exposure to U.S. home prices remains difficult to access, despite housing being one of the world’s largest asset classes.
Great to chat with @JReedRosenthal on The Investment Memo about why that gap persists and what the team at @Index_inds is building to address it.
One of the largest asset classes in the US doesn’t have a liquid index.
@Index_inds’ tech is powering a new investable index product for the US housing market. Co-founder and CEO @JReedRosenthal joined Lightspeed Partner @jmover on The Investment Memo to expand on what they’re building.
Index Industries’ first offering will be the U.S. Home Price Index (USHP Index), a proprietary benchmark for U.S. home prices. Calculated daily, it integrates data from the major housing indices into a single national measure, and will serve as a reference for the USHP token, which is issued by USHP Limited. USHP is a first-of-its-kind liquid index product backed by housing-related assets.
Josh explained why he feels USHP is so necessary in today’s market: Advanced blockchain capabilities, a more open regulatory environment, and a generation that has increasingly felt they couldn’t afford owning a home.
His goal is to broaden access to the housing market as an asset class. “Every home is a unique snowflake. You need deep expertise in specific markets, specific home types, and so on and so forth,” Josh says.
00:00 Meet Josh Rosenthal, CEO of Index Industries
01:45 From Investor to Co-Founder and CEO
03:29 The Ticker for the US Housing Market
05:19 On Traditional ETF Infrastructures
06:44 Blockchains as a Sandbox for Financial Innovation
10:17 The $300T Real Estate Asset Class
12:36 Tokenization Meets Real Estate
18:58 Building the Team
19:54 Five-Year Vision for US Housing
We’re thrilled to announce coming out of stealth with a $50M raise to transform how the world accesses real estate markets.
Real estate is the largest asset class in the world, worth $300 trillion, so why hasn’t it evolved with the rest of finance? It remains one of the hardest to access, both directly and through traditional financial products.
The first application of Index Industries’ technology is @USHP_Official: a first-of-its-kind liquid, investable index referencing the U.S. housing market.
The U.S. housing market finally has a ticker.
A truck carrying $11.4 million in Nvidia hardware disappeared after leaving Oakland, as organized cargo thieves increasingly target expensive computer equipment destined for the data centers powering the AI boom.
https://t.co/ng0DZn60Dz
We’re excited to triple down on Casap in its $56M Series B.
Casap uses specialized AI agents to help financial institutions resolve disputes faster, reduce fraud losses, and deliver better customer experiences.
For decades, the quality of service a financial institution could deliver was limited by resource constraints and costs. Resolving a disputed transaction or investigating suspected fraud required specialized coordination across fragmented systems.
Casap’s technology aims to fundamentally change that equation.
Since we first backed co-founders @shanthi_peace and Saisi in 2024, the team has grown revenue 10X in the last year alone and expanded to work with 100+ financial institutions.
With this new funding, Casap is bringing its agentic approach beyond disputes to fraud, collections, claims, and more.
Congratulations to the entire team!
Cc: @arfrank, @jmover,and @seisler1
There are a few times in the broader capitalist and Silicon Valley / tech timeline where I am happy I spent time on a cap markets desk, specifically with structured products… this is certainly one of them…
Bloomberg: "A new anxiety is gripping Wall Street as it bankrolls the vast network of data centers and chips behind the artificial intelligence boom: Early signs suggest that the credit market is approaching the limits of how much more debt it can absorb.
One after another, yields are soaring into the double digits on bonds and loans funding the AI infrastructure buildout. Bankers are finding it more difficult to offload risk to insurers and other investors."
#economy #markets #debt #ai #ArtificialIntelligence #bonds
Stripe Crypto brings together everything needed to enable agentic commerce.
From stablecoins on @tempo to secure non-custodial wallets powered by @privy_io, here's what's powering Link balance for AI agents, starting with @instinct. https://t.co/yn07R9uE1F
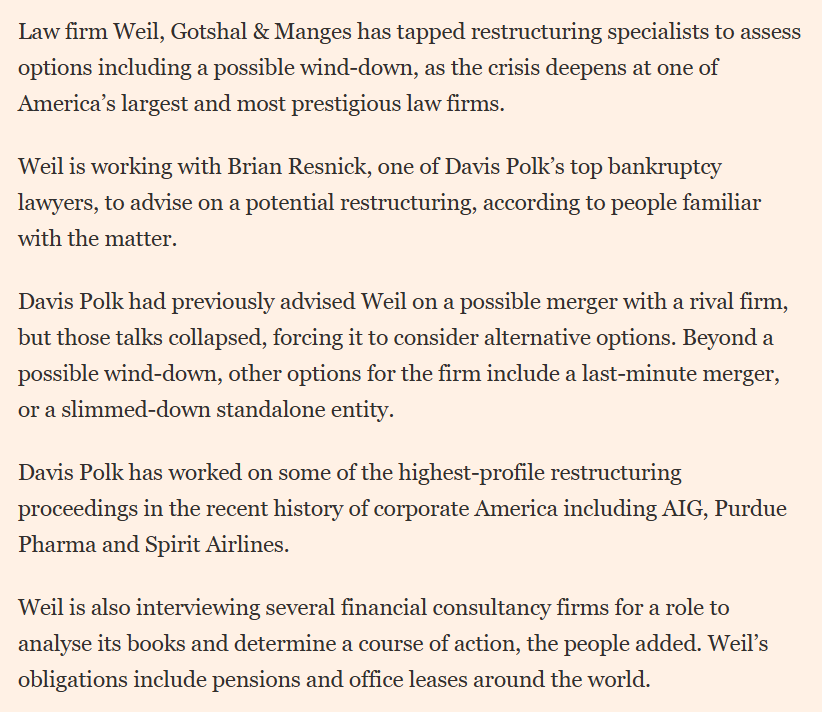
NEW: Brian Resnick from Davis Polk restructuring team now on scene at Weil and wind-down now being actively discussed among options:
https://t.co/DwqUvE9bwj
Has Coreweave management considered *buying* their stock for a change? You do it by clicking the big green button right next to the red one for a change.
Proud to finally share that @lightspeedvp is leading @warpsciences’ $215M Series A.
We’re at a fascinating point in AI drug discovery. AI can help scientists design promising molecules, but making and testing them still takes time and skilled lab work.
By combining AI, robotics and chemistry in US labs, Warp wants to accelerate drug discovery while generating the real-world data that could help AI get better at chemistry.
We’ve known @kevinweil for nearly two decades and have great respect for him. Together with @dpatil, @manohar_paluri, and Sol, the team brings deep experience at the frontiers of science and technology from OpenAI, Meta, Terremoto, Devoted Health and the White House.
Congrats to the entire team! Thrilled to be your partners from inception.
CC: @ravi_lsvp, Dr. Shelley Chu, Dr. Jonathan Macquitty
“AI is going to take the old business models of ads and subscriptions and just annihilate them. Something will replace it, and I think there’s a good likelihood it’s going to be built on stablecoins.” - @eastdakota
Was incredibly prescient of Matthew Prince (@cloudflare) with @benmilne (@bralexyz) at @averystableconf in March of this year. Can't wait to tell you what @ay_o@kerrykellogg and I are working on for next year!
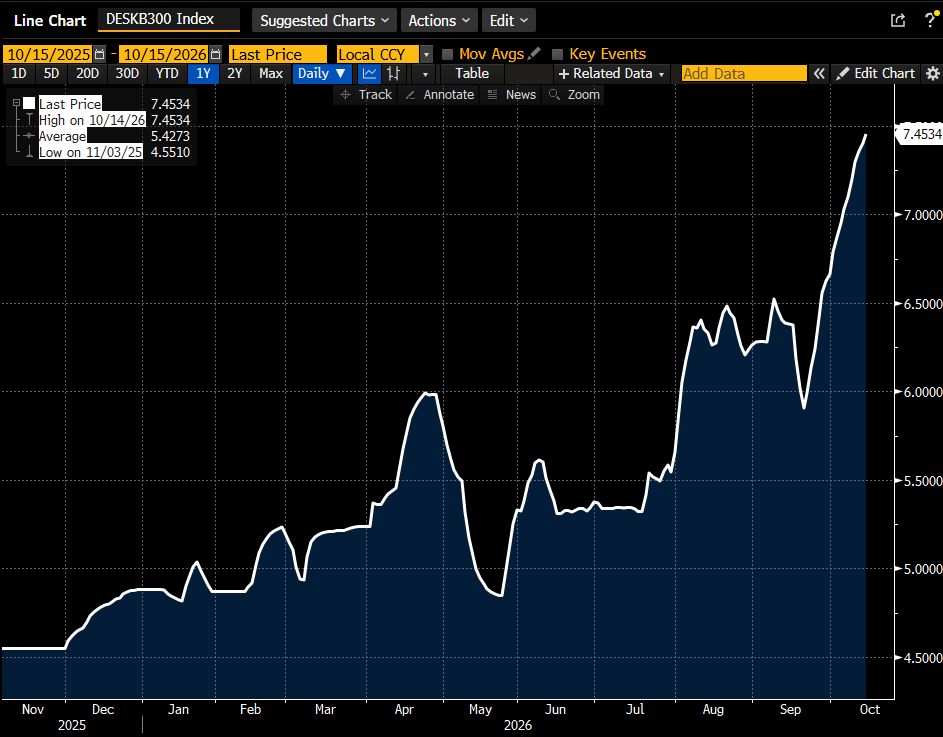
Blackwell Ultra (B300) GPU rental prices up 17 consecutive days to a new all-time high, according to Compute Desk's index of verified transactions from U.S. neoclouds.
Joe is asking a good question, but if you look a little closer, things are responding in a relatively rational manner.
The front end of the yield curve is staying rather fixed. This means the market is suggesting that the Fed will hike and hold even as systemic risk is increasing (neoclouds).
The net impact of that is to decrease growth and inflation expectations further out the curve, which causes forward rates like 5y5y to rally.
Moreover: tighter fiscal conditions, relative to risk factors, increases the value of volatility and convexity, which would cause forward rates again to be supported.
This is exactly what we are seeing.
There are of course flows to go alongside this: if people have hedged the duration exposure of their core weave holdings, then a sale of such holdings would cause a backend rally.
BC
There are a legion of posters now putting out AI quant trading models. Most are crap.
Here’s a quote from this post: “Betting Against Beta, a classic from every textbook: minus 7.78% a year while the market rose 14.86%. A corpse.”
Of course I can’t find how it’s constructed or what period he’s referring to (or what paper he claims to base this design on).
Welp… There is no period starting from today and looking back any decent amount of time that has BAB significantly down (available on our website). It’s been flattish in the USA for a bit but still good global ex USA. Its long-term record is still great. The chief challenge to BAB comes from Robert Novy-Marx where he says it’s empirically subsumed by the profitablity. This is an interesting debate (we still prefer a portfolio of both, partially as the economic story for BAB is better than the one for profitability). Again, economics not just AI. Economics with AI can be super powerful. AI w/o economics, or any understanding of the literature, in a “small data” problem like investing *at all by high frequencies) is a recipe for silliness. Like the post below.
I suspect what has happened here is a mistake I’ve pointed out in other papers. The BAB factor needs a hedge ratio. You short less than you long as the shorts are (this is the point) much higher beta. If you do it dollar neutral you are running a very short the market position, and not doing the BAB factor as anyone serious has learned in the large literature. Thus in a bull market you wrongly think it stinks.
Or they just did it all wrong in some other way. They don’t explain a lot.
This is why AI in the hands of people who don’t know economics, haven’t read the literature, etc., is handing a nuclear weapon to those who should only have a butter knife if they pass a test and get a license.
And it’s why I think these people are suppliers not consumers of alpha for the foreseeable future.
One day that may change. Hopefully whoever takes over for me at AQR in my coming dotage (not for a while!) can deal with that.
Oh, and “corpse.” Rude as well as wrong. Cool graphics though.
The NFL is $24B annual rev biz and generates the largest $s of bets of the big 4 pro leagues (NFL, MLB, NBA, NHL) in the US (some data reports that NFL betting handles exceed all other U.S. sports combined).
I'd expect the other leagues to follow, but this is a heavy voice jumping in the convo.