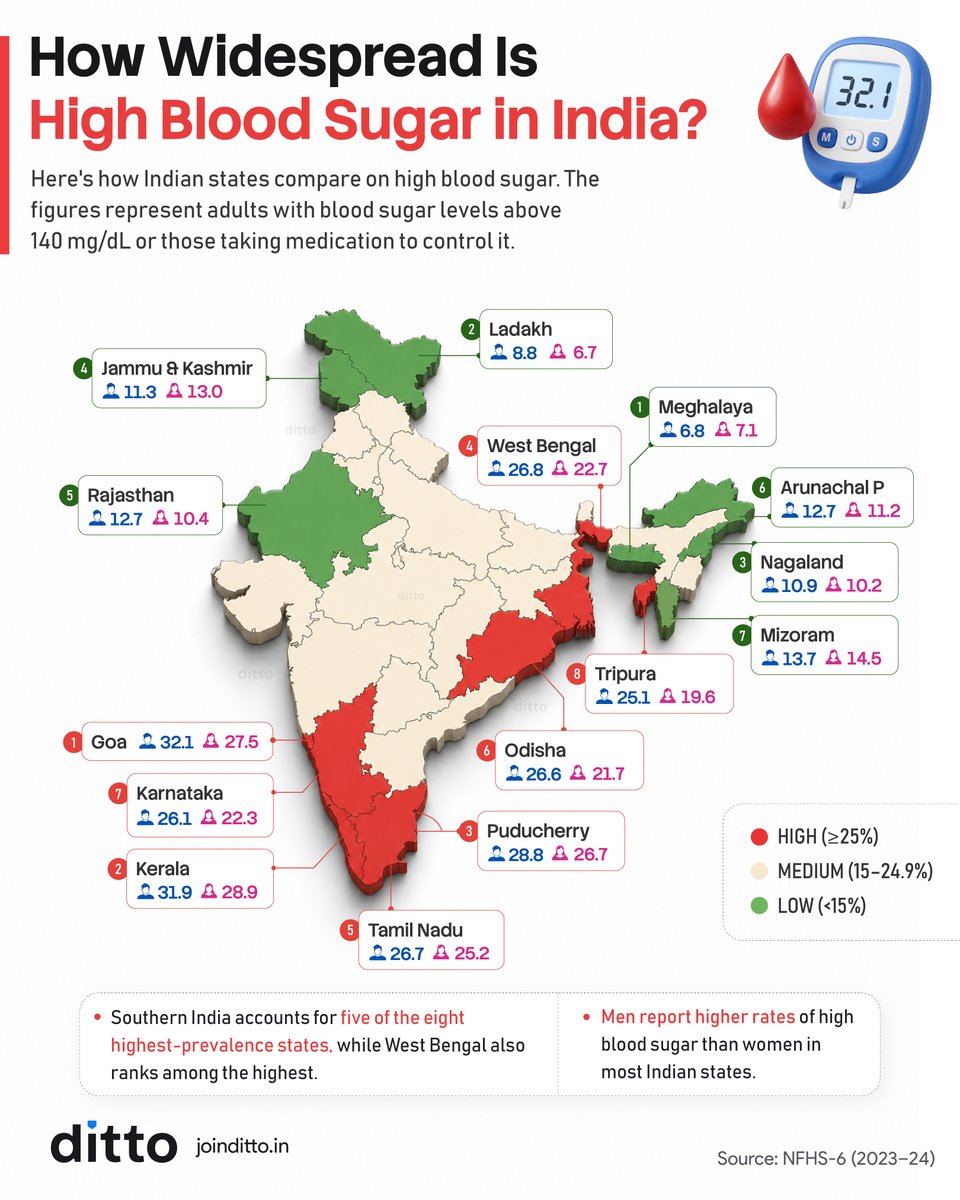
89.8 million adults in India have diabetes and nearly half of them don't even know it yet.
What makes it scarier is how quietly it shows up. The early signs don't feel like a medical crisis, they just feel like life.
And most people brush off the signs like feeling tired all the time, being more thirsty and peeing more often, until it’s too late.
And in India, the odds are stacked higher:
We're more prone to insulin resistance, and it hits us younger.
Stress, irregular sleep, and sedentary lifestyles are normalized.
Family history compounds the risk.
What doesn’t get talked enough about is how one late diagnosis can spiral into years of complications and costs that most people aren't prepared for.
I'm not saying this to scare you, but because awareness matters, and catching things early actually changes outcomes.
If you have health insurance, check if it includes preventive health checkups. Most policies do, and a simple annual checkup can flag rising blood sugar before it becomes a problem.
Use it, because it's already paid for. And for more health with your health insurance, book a free call with Ditto Insurance now.
#Diabetes #Healthcare #India
@Sushma_Kol Hi Sushma,
Apologies for the delayed response and the inconvenience caused. Kindly share your registered contact details with us via DM, and our team will reach out to assist you further.
Aura Points. Green Flags. GOAT
Yep, these are health insurance terms now.
Gen Z terms have officially entered the health insurance chat.
They’re actually part of a health insurance plan from ICICI Lombard called Vibe, launched in September 2026.
And instead of only stepping in when you’re hospitalised, this plan tries to be part of your everyday health too.
From rewards to wellness benefits, here’s how it actually works.
Vibe covers hospitalisation, day-care procedures, listed modern treatments, eligible AYUSH care and road ambulance expenses.
It also rewards you with Aura Points for staying claim-free, which you can redeem for activities like badminton, football and pickleball.
There are six variants of Vibe, and they don’t all come with the same benefits.
You have:
Value → Rookie → BasicFit → Upgrade → Flex → GOAT
The differences in each variant affect things like your room eligibility, restoration benefit, Green Flag Bonus, Aura Points and mental health sessions.
So, where does Vibe stand?
The wellness benefits definitely make it interesting.
But don’t pick a variant just because it has Aura Points or is called GOAT.
Look at the things that actually matter when you need to use your policy:
Waiting periods. Room eligibility. Restoration. Coverage. Add-ons. Premium.
P.S. If you're looking to buy health insurance and need help figuring out your options, book a free call with Ditto using the link in our bio.
#Insurance #Health #GenZ
@sharath_cb@HDFCERGOGIC Hi C B Sharath,
We sincerely apologise for the inconvenience caused. Kindly share your registered contact details with us via DM, and our team will reach out to assist you further.
@samarthbhargva@abhealthin Hi Samarth Bhargava,
We sincerely apologise for the inconvenience caused. Kindly share your registered policy number and/or contact details with us via DM, and our team will reach out to assist you further.
Your insurer can reject your claim just because of the hospital you chose to get treated at.
Yes, it's important to know which nearby hospitals you can go to. But what's actually more important is knowing which hospitals you shouldn't go to.
Unfortunately, most people don't think about this until it's too late.
Insurance companies often blacklist hospitals that have been flagged in the past for inflated billing, fraudulent claims, or unethical practices. And once a hospital is on that list, your insurer may not pay a single rupee for treatment there.
One important nuance: In an emergency, you can be taken to any hospital. But once you're stable, you may need to be shifted to a network hospital for the insurer to consider the claim.
We've seen customers who did everything right, had the policy, paid their premiums on time, and submitted all the required documents yet still ended up paying lakhs out of pocket simply because the hospital was blacklisted.
You already know which hospitals to go to. But if you don't know which ones to avoid, none of that may matter.
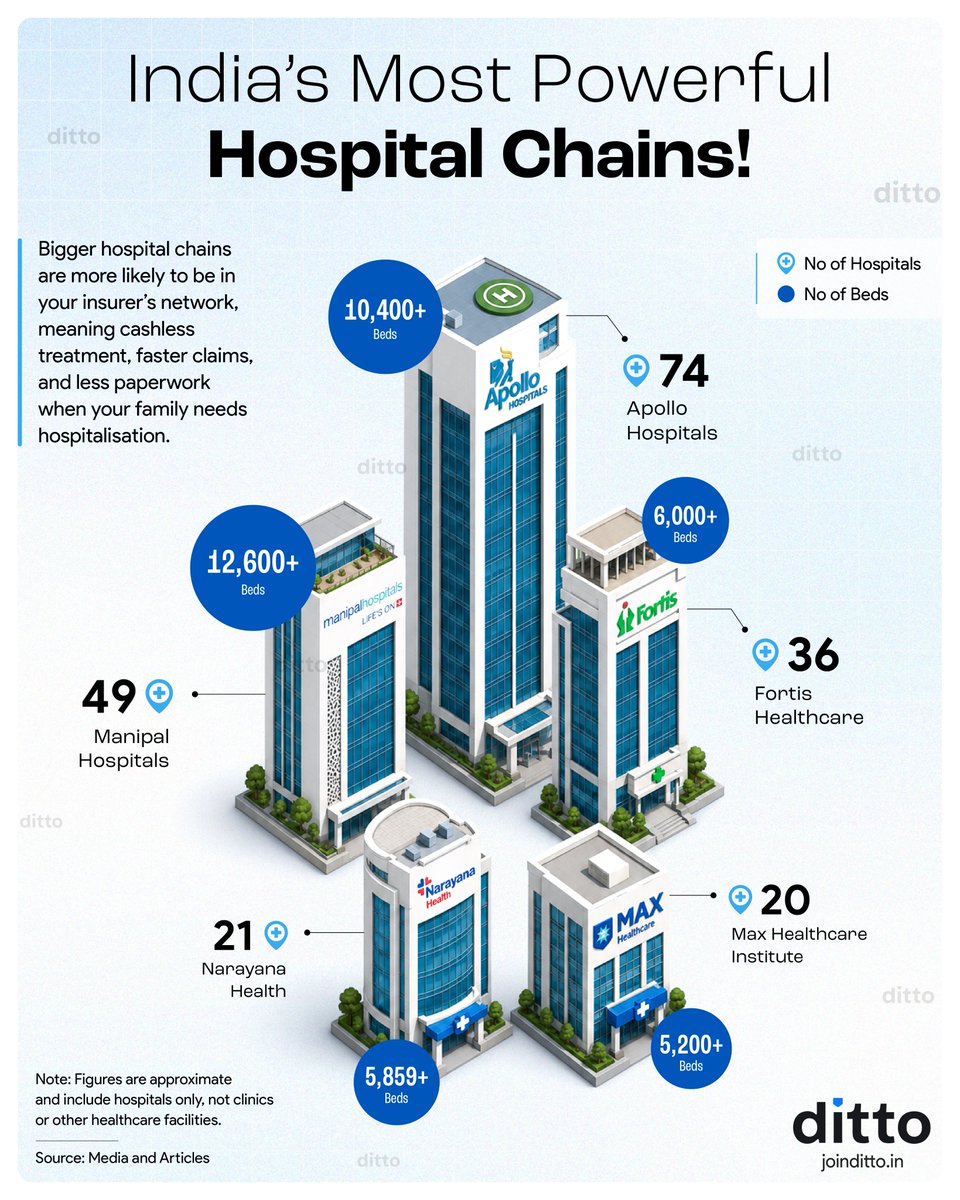
That is why hospital chain size matters more than most people think. A bigger network can mean better access, smoother cashless treatment, and fewer claim-related headaches when you need care fast.
Having said that, being part of a large hospital chain doesn't automatically mean it can't be blacklisted by your insurer.
This is why smart decision-making matters. A good policy is not only about the premium you pay but also about the hospital network you get, the ease of cashless treatment, and how smoothly the claim process works when life takes an unexpected turn.
**
PS: At Ditto Insurance we help you understand your policy and avoid gaps that lead to claim denials. Book a free call with us now.
Activ Yuva vs Activ One MAX: Which one would you bet on?
Aditya Birla Health Insurance offers several health plans, but we're comparing two today: Activ Yuva and Activ One MAX.
Here's how they stack up on the benefits that matter.
Who can buy it?
Activ Yuva: Individual entry up to 35; family floater up to 45, with at least one member below 36.
Activ One MAX: No maximum entry age.
MAX offers more flexibility if you're covering older family members.
How much cover can you get?
Activ Yuva: ₹5 lakh to unlimited cover.
Activ One MAX: ₹5 lakh to ₹2 crore.
Want unlimited base cover? Yuva has the edge here.
What about waiting periods?
Activ Yuva: Up to 2 years for pre-existing diseases.
Activ One MAX: Up to 3 years, but its Chronic Care add-on can reduce waiting periods for seven specified conditions.
Yuva wins on the general waiting period.
Need maternity or OPD cover?
Activ Yuva: Both are available through add-ons.
Activ One MAX: No maternity cover in the base plan or dedicated OPD wallet.
Yuva offers more options for these expenses, but the add-ons cost extra.
What happens when you claim?
Both plans offer unlimited restoration, but there's a catch.
Activ Yuva: Restoration starts from Day 1.
Activ One MAX: Restoration starts after the first claim of the policy lifetime.
Yuva gives you access to restoration sooner.
Which plan builds more cover?
Activ Yuva: Yuva Credit adds 100% of your base sum insured every year, up to a cap of 1000% over 10 renewals.
Activ One MAX: Super Credit caps at 500%, subject to applicable limits.
Yuva has the higher bonus potential.
So, which one should you pick?
Activ Yuva: Better suited to younger buyers wanting unlimited cover, optional maternity and OPD, and higher bonus potential.
Activ One MAX: Worth considering for older family members and specified chronic conditions.
Your needs determine the winner.
Still can't decide?
Book a free call with our IRDAI-certified advisors, and they’ll help you out. The link is under the profile!
#insurance
@sh1newow Hi SH1NE,
We sincerely apologise for the inconvenience. Kindly share your contact details with us via DM, and our team will reach out to assist you further.
1/ IRDAI is looking at letting you borrow against your life insurance so you don’t have to cancel it.
We have often seen people cancel when money is tight and get back less than if they had waited.
Here is what IRDAI has in their mind [a thread]
Your health insurance can now cover your dog, too!
You know how we say our pets are family? Bajaj General has taken that quite literally.
Its My Health Complete plan lets you cover yourself, your spouse, your children and your dog or cat under one policy.
And this isn't just a pet add-on; the human cover ranges from ₹5 lakh to ₹5 crore, with no co-pay, hospitalisation cover and several other standard health insurance benefits.
Your pet gets medical cover, too.
Eligible dogs and cats can get coverage for hospitalisation, surgery, pre and post-hospitalisation expenses, and more, subject to policy terms.
But the catch is that your family and your pet share the same sum insured.
So, if your dog needs an expensive surgery, that claim could eat into the cover your family relies on, too.
And not just that, a pet claim can also affect your cumulative bonus. Unlimited reinstatement helps, but it doesn't change the fact that your family and pet are drawing from the same cover.
That said, it's not just the medical cover that's interesting.
There's support for emergency pet boarding if you're hospitalised, help with finding a missing pet, and eligible third-party liability cover if your pet injures someone or damages property.
But do these extra benefits make it worth combining your family's and your pet's cover?
Not necessarily.
With separate policies, your pet's medical bills won't eat into your family's health cover or affect its cumulative bonus.
With one policy, you get the convenience of managing both under the same plan.
So, you're essentially choosing between convenience and keeping the two covers separate. Before you decide, compare both and follow ditto for more such information!
Note: Ditto's advisory services are limited to health and term life insurance. This post is purely informational and is meant to help you understand what pet insurance is and whether it makes sense for you.
#Insurance #pets
@taylenashowgirl@irdaindia Hi,
We sincerely apologise for the inconvenience caused. Kindly share your registered contact details and/or policy number with us via DM, and our team will reach out to assist you further.
@ThisisNaveen28@careinsuranceIN Hi Naveen,
If you’ve purchased the policy through Ditto, kindly share your registered contact details and/or policy number with us, and our team will reach out to assist you further.
You're overpaying for your insurance!
Many people end up paying more for the exact same term insurance cover.
Not because of the insurer or the plan, but because of the premium payment option they choose.
When buying term insurance, you usually get two payment options.
Regular Pay means paying throughout the policy term.
Limited Pay lets you finish paying earlier while your cover continues for the full policy term.
For example, a 25-year-old non-smoker buying ₹1 crore cover for 40 years would pay:
5 Pay: ₹2.09 lakh
10 Pay: ₹2.19 lakh
15 Pay: ₹2.58 lakh
In total premiums.
Now, a 5 Pay Limited Pay option costs ₹2.09 lakh, while Regular Pay costs ₹3.94 lakh.
That's a difference of ₹1.85 lakh, or nearly 47%, for the same cover.
So why doesn't everyone choose Limited Pay?
Because the yearly premiums are much higher. You may save more overall, but only if your current cash flow can comfortably handle those larger payments.
Limited Pay could be a good fit if you have a stable income, can afford higher premiums today, and want to finish paying for your policy much earlier.
Whichever option you choose, what matters most is buying term insurance early.
Because premiums generally increase with age, future health conditions could make getting the same cover more expensive or even more difficult.
There's no one-size-fits-all answer. The best payment option depends on your budget, income and financial goals.
#Insurance
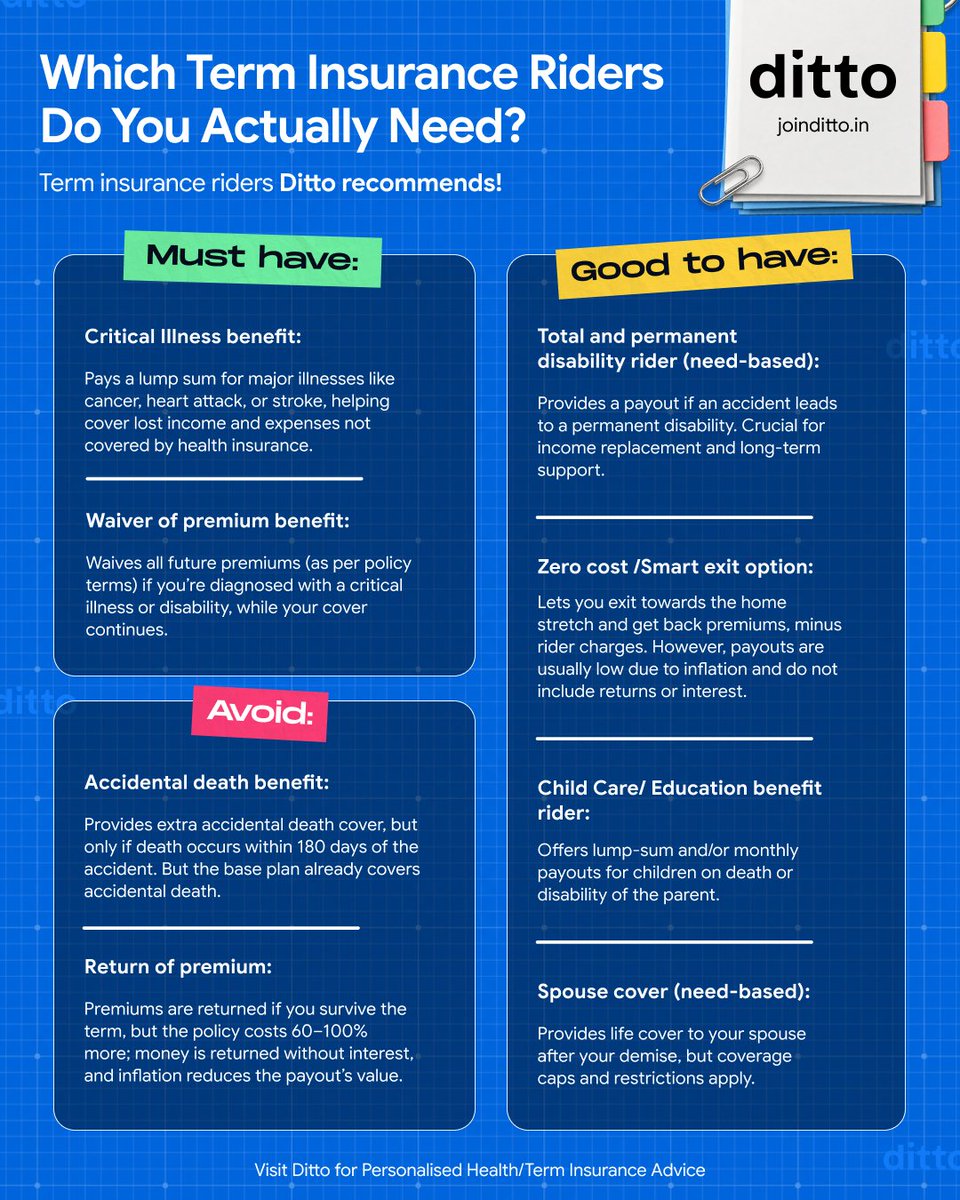
Your term insurance riders could cost you as much as your base policy.
According to IRDAI, health-related and critical illness riders can cost up to 100% of your base policy premium. For all other life insurance riders combined, the limit is 30% of the base premium.
And paying more doesn't always mean getting more cover. A rider’s sum assured generally cannot exceed your base policy’s sum assured. There’s just one exception: accidental death benefit riders can offer up to three times your base policy’s sum assured, subject to policy terms.
Before adding a rider, make sure you understand both the protection it offers and what it costs. If you're unsure what you need, book a free call with our IRDAI-certified advisors. The link is under the profile!
#Insurance
@koustavd12@ICICILifeIns Hi Koustav Das,
We sincerely apologise for the inconvenience caused. Kindly share your registered contact details and/or policy number with us via DM, and our team will reach out to assist you further.
Your ₹10 lakh cover may pay only ₹1.5 lakh for a cardiac procedure!
This is one of the most common gaps we flag at Ditto.
A client has a ₹10 lakh sum insured and assumes the full amount is available for a heart condition.
But when the ₹3 lakh bill arrives, the insurer settles only ₹1.5 lakh.
The reason is a disease-wise sub-limit.
It caps how much your insurer pays for a specific illness, separate from your overall sum insured.
So even with a ₹10 lakh cover, cardiac care, cataract, knee replacement and kidney stone removal could each have a smaller limit.
Insurers use these caps to limit their risk. Policies with sub-limits often have lower premiums because the insurer’s maximum payout per illness is fixed in advance.
They also help curb inflated hospital billing, since most treatments have a well-known cost range and a cap keeps claims within that range.
They protect the insurer from claims that run far above what a procedure typically costs.
This is often why people opt for these policies in the first place. A sub-limited plan can look identical to a comprehensive one at first glance, except the premium is noticeably cheaper.
Most buyers pick the cheaper option without checking what sits underneath it.
But there's a catch. Your policy paper still shows ₹10 lakhs as your cover.
Your insurer, though, has quietly set aside a much smaller limit for that specific illness, say ₹1.5 lakhs. It won't pay beyond that.
Most people discover this gap only when the final bill arrives, leaving them to pay the difference.
However, there are two situations where a sub-limit may make sense:
1. If you have a pre-existing condition, insurers may only offer policies with one.
2. As a senior citizen, a sub-limited plan may be your only option.
In both cases, some cover is better than none. Outside these situations, there’s little reason to choose a policy with disease-wise sub-limits.
Plans without them are available at reasonable premiums.
Ask your advisor which treatments have sub-limits and their caps.
If you need help finding a policy without these restrictions, book a free call with Ditto. The link is under the profile!
#Insurance
@Santoshmnv@NivaBupa Hi Santosh,
Apologies for the inconvenience caused. Kindly share your registered contact details and/or policy details with us via DM if the policy is purchased through us. Our team will connect with you to assist further.