Behari Lal Engineering
#BehariLal#BLEL
Good Q1FY27 with decent EBITDA margin expansion
Decent QoQ and YoY uptick across all parameters, adj for other income QoQ
Lower other income QoQ
Rev at 152cr vs 128cr⏫18% YoY
Q4 at 131cr⏫16%
Other income at 2cr vs 7cr QoQ
EBITDA at 28cr vs 23cr⏫21% YoY
Q4 at 24cr⏫18% QoQ
PBT at 26cr vs 21cr⏫24% YoY
Q4 at 22cr
PAT at 19cr vs 15cr⏫25% YoY
Q4 at 16cr
Milky Mist Dairy Food
#MilkyMist
Press release:
#Q1FY27
Record quarter with extremely strong YoY growth and decent QoQ growth
Good QoQ and excellent YoY growth across all parameters
Rev at 973cr⏫44%
Gross profit at 333cr⏫56%
GPM at 34.2% vs 31.46%
EBITDA at 145cr⏫75%
PBT at 74cr⏫900%
PAT at 65cr⏫890%
Paneer remained the largest contributor
Paneer rev⏫34%
Cheese rev⏫38%
Curd rev⏫27%
Ice cream rev⏫60%
Yogurt rev⏫153%
Higher volume growth
Improved product mix
Pricing ability
Operational efficiencies led to
EBITDA growth and OPM expansion
During Q1FY27, company commissioned a new Cheddar Cheese plant with installed capacity of 120 MT per day
Milky Mist Dairy Food
#MilkyMist
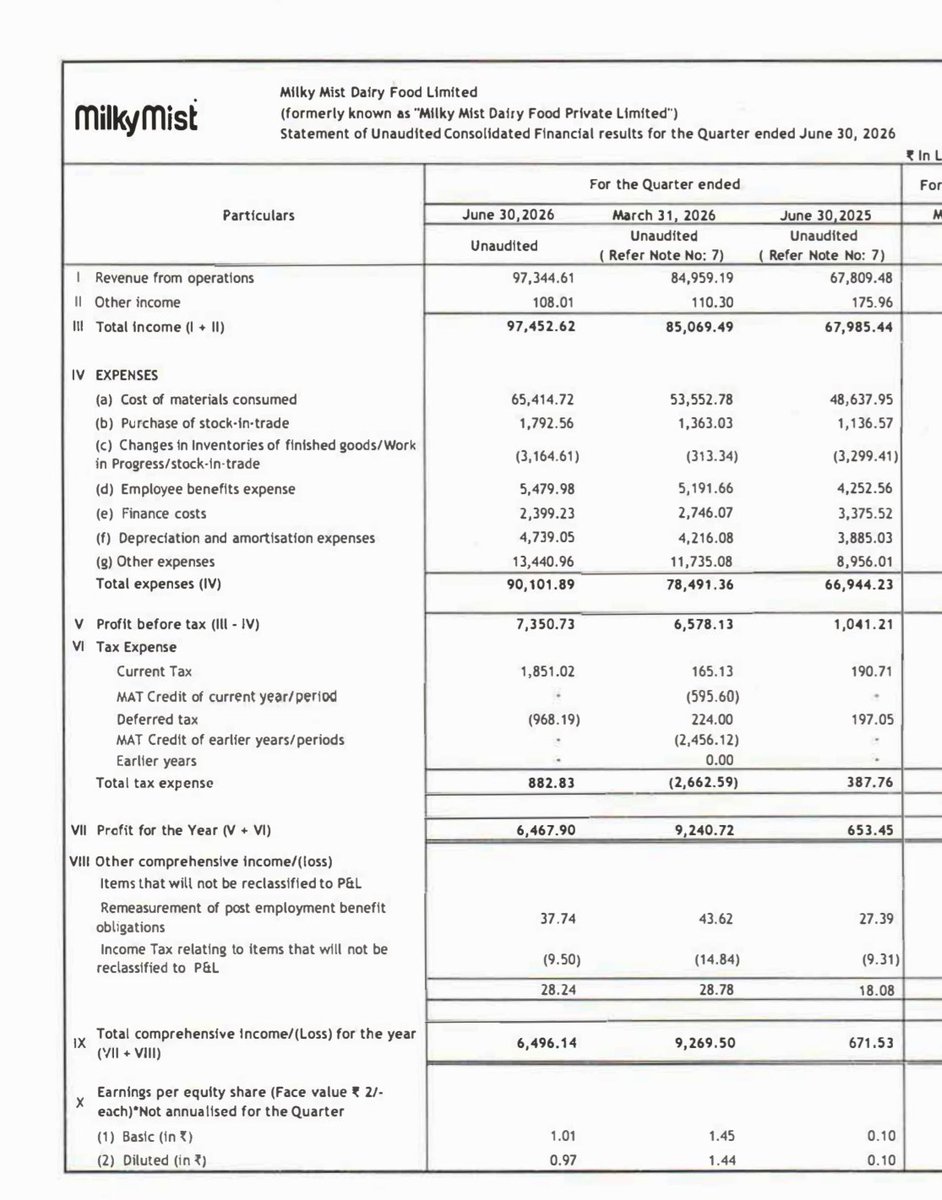
Very Good Q1FY27 with good QoQ and YoY uptick across Rev, EBITDA and PBT
PAT is optically down QoQ due to 27cr tax credit in Q4FY26
Best among peers in terms of growth
Rich valuations , but superior growth when peers are struggling with margins and profitability
Rev at 973cr vs 678cr⏫44% YoY
Q4 at 850cr⏫15% QoQ
EBITDA at 144cr⏫77% YoY
⏫8% QoQ
OPM at 15%⏫278 bps YoY, down 104bps QoQ
PBT at 74cr vs 10cr⏫7.4x YoY
Q4 at 65cr⏫14% QoQ
PAT at 65cr vs 6.5cr⏫900%
Q4 at 92cr due to 27cr tax credit
Lohia Corp
#LohiaCorp#LCL
Q1FY27 concall highlights:
Guidance:
30-35% growth guidance for FY27 with 20%+ OPM
20-25% CAGR from FY28 onwards
Record Q1FY27 with big uptick
Operating leverage playing out well
20% margins are sustainable
Further expansion possible with increasing exports mix
Orderbook at 1800cr almost
6-9 months execution timeline for outstanding orders
FY27 guidance of 2200-2300cr revenue
Which is 32-35% higher than FY26
FY28 onwards
20-25% CAGR possible on higher base of FY27
Pricing power
10-12% higher pricing vs competition
Disciplined execution
Aims to increase global market share
Current utilization at 70%
Scope to move it to 85%
Minimal capex requirement
80-90cr capex requirement for incremental 500cr revenue addition
Overall, an amazing concall with great clarity and strategic objectives
#LCL
Lohia Corp Limited | Earnings Call Summary (Extract) - Jun-2026 Qtr | Disc: AI generated, please verify
Management Guidance and Outlook
■ Revenue Growth: Management expects to grow in the range of 20-25% annually, driven by the increasing applications for their machine's end products and a strong order book.
■ Profitability: The company aims to maintain EBITDA margins around the 20% level, viewing it as the new normal. They indicated that a higher share of exports in the future could provide an upward lift to this margin, supported by operating leverage.
■ Market Focus: While the domestic market is currently strong, the company expects exports to rebound and contribute around 50% of revenue going forward.
■ CapEx: No major CapEx is planned in the immediate future, as current capacity can support revenue up to INR 2,400-2,500 crores. Future CapEx will be light, with an estimated INR 80-100 crores needed for every INR 500 crores of turnover beyond that threshold.
■ Strategic Initiatives: The company will continue to invest selectively in product development, automation, digitalization, and its emerging recycling and monofilament solutions, all while maintaining financial discipline.
Lohia Corp
#LCL#LohiaCorp
Inv PPT:
Q1FY27:
Rev at 503cr vs 315cr⏫60%
EBITDA at 100cr vs 36cr⏫180%
OPM ⏫840bps YoY
PAT at 66cr vs 17cr⏫292%
15.4% global market share in Woven Raffia machines by value
40.7% Indian market share in Woven Raffia machines by value
100 countries served
Exports focused
2000+ customers served
42% revenue from exports in FY26
41% RoCE
37% RoE
Net D/E at 0.2x
Net debt/EBITDA at 0.4x
Last 3 years:
Revenue:
FY24 1166cr
FY25 1377cr
FY26 1717cr
EBITDA:
FY24 98cr at 8.4%
FY25 219cr at 15.9%
FY26 319cr at 18.6%
PAT:
FY24 30cr
FY25 118cr
FY26 193cr
Pending orderbook at 1359cr as of March 2026
Orderbook at 1778cr after Q1FY27
More than 400cr addition in 3 months
6-9 months execution cycle
FY26 OCF at 325cr vs 141cr
WC days at 84
Good #Q1FY27
19/8/2026
Couple of newly listed companies
Xtranet Technologies (#Xtranet)
Lohia Corp (#LCL)
Lohia Corp
#LCL#LohiaCorp
Solid Q1FY27 with big YoY growth with almost 900bps margin expansion
Exponential growth YoY
Small downtick QoQ which is absolutely fine
Rev at 503cr vs 315cr⏫60%
Q4 at 510cr
EBITDA at 100cr vs 36cr⏫176%
Q4 at 103cr
OPM at 20% vs 11%, stable QoQ
PBT at 91cr vs 23cr
Q4 at 97cr
PAT at 66cr vs 17cr⏫292%
Q4 at 71cr
Xtranet Technologies
#Xtranet
Looks like there is a seasonality in the business
Q4 was very big vs Q1
Rev at 50cr vs 46cr
Q4 at 161cr
EBITDA at 10.4cr⏫91%
PBT at 7.4cr vs 4.1cr
Q4 at 31cr
PAT at 6cr vs 3.3cr
Q4 at 24cr
FY26 PAT was 41cr out of which 24cr came in Q4 itself
DAM Capital on Milky Mist Diary Food
Initiate coverage with a BUY rating
Target price of Rs.175
-Revenue grew at 31.3% CAGR over FY24 to FY26 to Rs 3140cr, the fastest among listed peers
-Value Milky Mist at 35x forward earnings as stock commands a premium to listed dairy peers, with GPM at ~700 bps ahead of the peers
-Milk procurement economics and cooperative competition anchor the business to dairy, even as brand equity, premium positioning and growth optionality align it with packaged foods
Indo MIM Ltd
#IndoMIM
Recently listed company
Good Q1FY27 with solid margin expansion QoQ and YoY
Rev at 1219cr vs 1114cr⏫9% YoY
Q4 at 1048cr⏫16% QoQ
EBITDA at 406cr vs 327cr⏫24% YoY
Q4 at 200cr⏫103% QoQ
OPM at 33.4% vs 29.4%⏫404bps YoY
Q4 at 19.1%⏫1422bps QoQ
PBT at 325cr vs 245cr⏫32% YoY
Q4 at 171cr⏫88% QoQ
PAT at 240cr vs 182cr⏫32% YoY
Q4 at 139cr⏫73% QoQ
Good #Q1FY27-09/08/26
Sky Gold and Diamonds
#SkyGold
Solid Q1FY27 with highest ever revenue, EBITDA, PBT and PAT in comps history
Good QoQ and YoY uptick across all parameters
Rev at 2012cr vs 1131cr, Q4 at 1912cr
EBITDA at 157cr⏫120% YoY, ⏫ 12% QoQ
PBT at 135cr vs 59cr, Q4 at 118cr
PAT at 105cr vs 44cr, Q4 at 86cr
Expects 180-225cr OCF for FY27
FY27 guidance revised upwards:
Rev target of 8100cr with OPM at 7-7.5%
FY30 target:
Rev of 18,000-19000cr with 5.25% NPM
Quality Power Electrical Equipments
#QPower
Rev at 232cr vs 176cr, Q4 at 280cr
Gross profit at 121cr vs 87cr⏫40%
Other income at 24cr vs 17cr, Q4 at 29cr
EBITDA at 41cr vs 31cr⏫32% YoY, ⏫ 35% QoQ
OPM steady at 17.5%
PBT at 59cr vs 44cr, Q4 at 53cr
PAT at 47cr vs 37cr Q4 at 51cr
Orderbook at 1946cr
Knack Packaging
#Knack
Solid Q1FY27 with good QoQ and YoY uptick across all parameters
Rev at 262cr vs 186cr, Q4 at 214cr
EBITDA at 57cr vs 38cr⏫51% YoY, ⏫ 65% QoQ
PBT at 45cr vs 28cr, Q4 at 33cr
PAT at 30cr vs 20cr, Q4 at 24cr