Didn't know this.
Blinkit launched its free ambulance service for the public in January 2025, starting with 5 ambulances in Gurugram.
The aim was to provide quick, free access during medical emergencies.
So far, 42,000 cases handled, including 20,000 emergencies.
But people started using it for routine check-ups and non-emergency transfers.
Today, @deepigoyal announced -
- Genuine emergencies - FREE
- Non-emergencies - ₹2,500
Misusing good services makes everyone suffer. Are we becoming a low trust society?
@DC_Gurugram@palakagarwal04 Aur poocho bhar gaye address ab kal se leke time lo 10 days ka and visit each address provided and share video proof of action taken against violator
@DC_Gurugram
Thanks for your attention
#SME#Mach#MachTravel#MachTravelSolutions
Mach Travel Solutions H1 FY27 Concall Highlights:
👉H1 FY27 & Future Outlook :
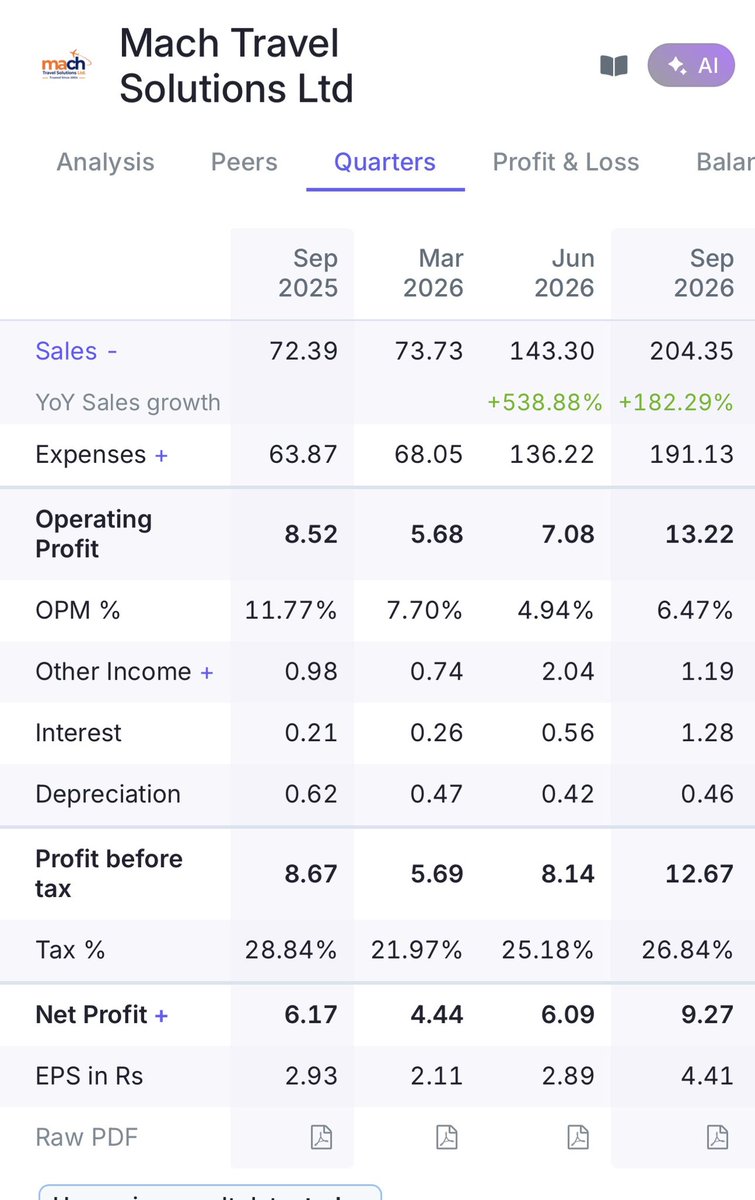
▫️H1 FY27 consolidated revenue ₹348.86 Cr, +259.4% YoY from ₹97.08 Cr; highest-ever first-half revenue since 2004 and above entire FY26 revenue
💠EBITDA (incl. other income) ₹23.62 Cr vs ₹11.34 Cr (+108.3%); margin 6.71% vs 11.49%
💠PAT ₹15.42 Cr vs ₹7.82 Cr (+97.2%); margin 4.38% vs 7.93%; basic EPS ₹7.32 vs ₹3.70
💠GMV ₹784.54 Cr (₹252 Cr in Q1 and ₹532.54 Cr in Q2); disclosed since Q1 FY27
▫️Q2 FY27 revenue ₹204.53 Cr, +174.7% YoY from ₹74.46 Cr and +41.7% QoQ from ₹144.33 Cr
💠EBITDA ₹14.39 Cr vs ₹9.67 Cr (+48.8% YoY), +56% QoQ from ₹9.23 Cr; margin 7.00% vs 12.81% YoY and 6.30% in Q1 (~69 bps QoQ)
💠PAT ₹9.26 Cr vs ₹6.30 Cr (+46.9% YoY), +50.2% QoQ from ₹6.16 Cr; margin 4.50% vs 8.35% YoY and 4.21% in Q1
💠Basic EPS ₹4.40 vs ₹2.97
▫️FY27 revenue target revised upwards to more than 2.5x FY26 revenue
💠Pipeline and order book described as very strong; order book not quantified
💠FY27 growth termed exceptional
▫️Growth beyond FY27: ~25% YoY targeted
💠MICE to remain the largest revenue generator for years
💠Mix across verticals in coming years not predicted
▫️Margins: PAT margin lower as the company is aggressively acquiring customers and businesses after the revamp about six months ago
💠Absolute PAT has risen; PAT margin expected to improve gradually as the structure settles
💠Employee cost ₹10.45 Cr in Q2 vs ₹3.36 Cr; ₹19.36 Cr in H1 vs ₹6.38 Cr
💠Other admin expenses ₹4.36 Cr in H1 vs ₹2.33 Cr
💠Team scaled from 70-90 people over the last three years, when revenue was ₹220-230 Cr a year, to 350 now
💠First-six-month PAT equals last year's full-year PAT
💠Existing offices can seat ~1,000 people; Noida office (13,000 sq ft) fits 250-275 vs ~110 now; all seven offices hold 90+ each, so costs stay similar as the team ramps up
👉Order book / projects and pipeline:
▫️Management guided for FY27 revenue above 2.5x FY26 and ~25% growth thereafter
▫️Revenue mix for the ~₹350 Cr in H1:
💠MICE ~60-65%
💠Government and institutional ~15-20%
💠Corporate travel ~10%
💠Leisure (incl. visa) and B2B make up the rest; leisure ~5-7% and B2B ~3-4%, as B2B books only commissions on a large volume business
💠Exact bifurcation not available
▫️Corporate travel:
💠Dedicated vertical launched April 2026; 140+ clients onboarded for ticketing and the self-booking tool (SBT) as of 30 Sep 2026, from 100+ in Q1 and zero on 31 March
💠Spans automotive, engineering, pharma, financial services, technology, healthcare, education, FMCG, infrastructure, media and manufacturing
💠Long-term enterprise agreements; covers booking, approval, ticketing, invoicing and reporting with dedicated account management
💠Cross-sell route into MICE, hotels and leisure for the same clients and their employees
💠One MICE client of 8-9 years has now signed for corporate ticketing and the SBT, with a limit created
▫️Government and institutional projects:
💠Recognised by Ministry of Tourism (NIDHI) as an Experienced MICE Tour Operator; supports participation in tenders
💠Empaneled by Madhya Pradesh State Tourism Development Corporation under the Mukhyamantri Teerth Yatra Scheme after 15 October; ~10,000 pilgrims
💠Also empaneled with IRCTC and a Karnataka government undertaking; applications submitted in Bihar and Uttar Pradesh; discussions on with Bihar and UP governments
💠Other wins include international and domestic trips; one group trip to NASA, USA taken with 80% advance
💠Margins better than other players because of buying power from volumes; little cross-selling in this vertical
💠Government work takes time to qualify on technical bids, unlike corporate where large business can come quickly
▫️Inbound travel:
💠First three inbound groups from France, Belgium and the USA, 71 international travellers
💠Plans to attend fairs such as Dubai and WTM London
💠Small dedicated team; growth expected to show in the next six months
▫️B2C platform (https://t.co/4tHCMBS1nH and Mach Travel app):
💠Open for public beta from 31 August 2026; covers flights, hotels, holidays, MICE, cruises and visa
💠Employees, friends and family testing and reporting glitches; no commercial launch date given
💠New partnerships under way with airlines, consolidators and hotels
▫️Technology: corporate SBT and the B2C OTA platform are the two main initiatives; operational software also in use
▫️Offices: Noida, New Delhi, Mumbai, Kolkata, Bengaluru, Bhubaneswar and Ahmedabad; 2 more offices upcoming
👉Q&A :
▫️Finance cost:
💠Q2 ₹1.28 Cr vs ₹0.21 Cr; H1 ₹1.84 Cr vs ₹0.39 Cr
💠Higher turnover raised the need for funds; no fund raise planned now
💠May raise funds after migration to the main board, which is about 9-10 months away
▫️Margin concern raised by analyst (EBITDA margin ~11.5% to ~6.7%):
💠Management said building a customer base takes priority and the added customers will lift margins over time
💠A doubling of PAT on a pro-rata basis was mentioned but no commitment made
▫️Government payment cycle:
💠Yatra programme running since April; some payment delays but management comfortable with the cycle and focused on recovery
▫️MICE business continues with its team undisturbed; focus remains on MICE alongside the new verticals
👉 Others :
▫️Balance sheet at 30 Sep 2026:
💠Shareholders' fund ₹137.48 Cr (equity capital ₹21.04 Cr; reserves ₹114.77 Cr; minority interest ₹1.67 Cr)
💠Borrowings: long-term ₹3.92 Cr and short-term ₹3.87 Cr
💠Trade receivables ₹109.88 Cr vs ₹49.03 Cr at 31 Mar; trade payables ₹55.36 Cr vs ₹23.41 Cr
💠Cash and bank ₹32.89 Cr; short-term loans and advances ₹52.88 Cr
▫️Industry:
💠India MICE market USD 37.75 Bn in 2025, projected at USD 66.91 Bn by 2030 (12.13% CAGR); India ~5.7% of global MICE, ambition of 10%
💠India corporate travel market USD 10.4 Bn in FY24, projected at USD 20.8 Bn by FY30
💠India online travel market USD 23.34 Bn in 2025, projected at USD 38.58 Bn by 2031
▫️Next investor call in January or first week of February