Follow the link below to claim the credit or run /claim-credit in the CLI. You’ll need GitHub connected to start a session. Claim by Oct 7. Terms apply.
https://t.co/TzoO6fzJHB
*Why FIIs Are Continuously Selling India — The Real Reason*
FIIs have been continuously selling in India, and that's why Nifty has been underperforming for the last few years.
When the Government was re-elected in June 2024, the Union Budget in July 2024 made a major blunder. Not only was STT increased, but the biggest hit was:
*LTCG increased from 10% to 12.5% and STCG from 15% to 20%.*
Look at the result in the last 2 years — Nifty has given almost 7-8% negative return on a post-tax basis and has massively underperformed, even when global markets, especially the US, are trading at an all-time high. Why?
Because India is still a small-cap market compared to a large-cap market like the US. If a large-cap market like the US is giving 12-14% CAGR post-tax, and a small-cap, high-risk market like India is giving negative or just 8-10% pre-tax return — and then you deduct STT, LTCG, STCG, plus USD-INR depreciation — why will any FPI/FII put money in India?
Risk is too high here, especially with constant regulatory risk. Every day a new sector is targeted.
*So what will work now?*
In my view, Nifty large-caps will continue to underperform. Real outperformance will come from quality Midcaps, Smallcaps and Microcaps — where India still has growth.
*My Definition of Long-Term:*
Long-term does NOT mean "buy and forget."
Long-term means reviewing your stocks every quarter, like a regular health check-up. It means doing a detailed sector and stock rotation review and checking performance consistently.
And booking profits on a regular basis.
In a nutshell — a long-term FD will never beat inflation. But a smart investment strategy will surely beat inflation and help you achieve your long-term vision and goals.
Introducing Claude Opus 5.5, the first model in our new Claude 5.5 family.
It performs at the level of Claude Fable 5.1 for most tasks, and costs 40% less to run than Opus 5.
The Tax Authority issues Decision No. 189/2026 amending certain provisions of the Regulations of the Value-Added Tax Law, which include the issuance of tax invoices in an approved and secure electronic format that ensures their integrity and retention.
https://t.co/nWup3lS9bW
Claude for Excel, PowerPoint, and Word are now generally available, and Claude for Outlook is in public beta.
As Claude moves between your Microsoft apps, it carries the full context of your conversation.
@AbhasHalakhandi@AbhasHalakhandi in case of 0 B2B supplies, will the GSTN allow filing as HSN B2B section will be blank. As there is gstn validation to provide HSN B2B details.
🔥🚨BREAKING NEWS: Bill Gates announced that he will be giving 99% of his $200 billion fortune to Africa and other charities over the next 20 years, while leaving only 1% to his children.
[BIG News] Telcos entitled to CENVAT credit on tower parts, shelters and chairs: Supreme Court
The Supreme Court on Wednesday allowed appeals filed by telecommunication companies such as Airtel, Vodafone Idea and Tata telecommunications challenging orders that held that they were not entitled to Central Value Added Tax Credit (CENVAT credit) on tower parts, shelter, printers and chairs [M/S Bharti Airtel Limited v. Commissioner of Central Excise, Pune III].
The judgment was passed by a Division Bench of Justices BV Nagarathna and N Kotiswar Singh.
"We have allowed the appeals in the main matter as well as connected matters by the companies. We have upheld the 2021 Delhi High Court decision and have set aside the Bombay High Court decision of 2014 in Bharti Airtel," Justice Singh said, while reading out the operative portion of the judgment.
A copy of the detailed order is awaited.
From 1st September, many changes in the GST Act will take place that will impact your GST Returns filing!
✅Notification No. 12/2024 (10 July 2024): From September 2024, if a supply's value is above Rs. 1 lakh, it must be reported in GSTR-1's Table B2CL.
✅Notification No. 12/2024 (10 July 2024): Taxpayers can now report negative liability in GSTR-3B's Table No. 3. The negative liability will be automatically adjusted in the next month's return, making the reconciliation process smoother.
✅Blocking of GSTR-1 for Non-Furnishing of Bank Account Details: From 1st September 2024: If you haven't added and validated your bank account details in your GST registration, your GSTR-1 /IFF will be blocked.
✅GSTR-9 and GSTR-9C: Forms GSTR-9 (Annual Return) and GSTR-9C (Reconciliation Statement) will be active on the GST portal.
🛑💥 The CBIC issued various circulars on the 53rd GST council recommendations.
CBIC issued Circular on reduction of Government Litigation – fixing monetary limits for filing appeals or applications by the Department before GSTAT, High Courts and Supreme Court [Circular No. 207/1/2024-GST]
Read More at: https://t.co/9HaBXm7jSe
CBIC issued clarifications on various issues pertaining to special procedure for the manufacturers of the specified commodities [Circular No. 208/2/2024-GST]
Read More at: https://t.co/JgtKXOeWrj
CBIC issued clarification on the provisions of clause (ca) of Section 10(1) of the IGST Act relating to place of supply of goods to unregistered persons [Circular No.209/3/2024-GST]
Read More at: https://t.co/opdlLXd5vv
CBIC issued clarification on valuation of supply of import of services by a related person where recipient is eligible to full input tax credit [Circular No.210/4/2024-GST]
Read More at: https://t.co/jO4Q38My5f
CBIC issued very Important clarification on time limit under Section 16(4) of CGST Act, in respect of RCM supplies received from unregistered persons [Circular No. 211/5/2024-GST]
Read More at: https://t.co/q7nij03S8I
CBIC issued Circular on Mechanism for providing evidence of compliance of conditions of Section 15(3)(b)(ii) of the CGST Act, by the suppliers [Circular No.-212/6/2024-GST]
Read More at: https://t.co/Ojl2srBaNm
CBIC issued Clarification on the taxability of ESOP/ESPP/RSU provided by a company to its employees through its overseas holding company [Circular No. 213/07/2024-GST]
Read More at: https://t.co/P7O4YAgGsv
CBIC issued clarification on requirement of reversal of input tax credit in respect of the portion of the premium for life insurance policies which is not included in taxable value [Circular No. 214/8/2024-GST]
Read More at: https://t.co/xflS6U8Kgv
CBIC issued clarification on taxability of salvage/ wreck value earmarked in the claim assessment of the damage caused to the motor vehicle [Circular No. 215/9/2024-GST]
Read More at: https://t.co/lMzQW7REGc
CBIC issued clarification in respect of GST liability and input tax credit (ITC) availability in cases involving Warranty/ Extended Warranty [Circular No. 216/10/2024-GST]
Read More at: https://t.co/ba0CTJ9eYx
CBIC issued Circular on entitlement of ITC by the insurance companies on the expenses incurred for repair of motor vehicles in case of reimbursement mode of insurance claim settlement [Circular No. 217/11/2024-GST]
Read More at: https://t.co/VF9803JKnN
CBIC issued clarification regarding taxability of the transaction of providing loan by an overseas affiliate to its Indian affiliate or by a person to a related person [Circular No.218/12/2024-GST]
Read More at: https://t.co/E3UDsOWNpL
CBIC issued clarification on availability of input tax credit on ducts and manholes used in network of optical fiber cables (OFCs) in terms of section 17(5) of the CGST Act [Circular No. 219/13/2024-GST]
Read More at: https://t.co/T7CCCTF52h
CBIC issued Clarification on place of supply applicable for custodial services provided by banks to Foreign Portfolio Investors [Circular No 220/14/2024-GST]
Read More at: https://t.co/m0KYVNJmPV
CBIC issued clarification on time of supply in respect of supply of services of construction of road and maintenance thereof of NHAI in HAM model [Circular No.-221/15/2024-GST]
Read More at: https://t.co/wCBj4oGebo
CBIC issued clarification on time of supply of services of spectrum usage and other similar services under GST [Circular No. 222/16/2024-GST]
Read More at: https://t.co/fE7acD70O7
#GST #GSTwithbimaljain #a2ztaxcorpllp #GSTUpdates
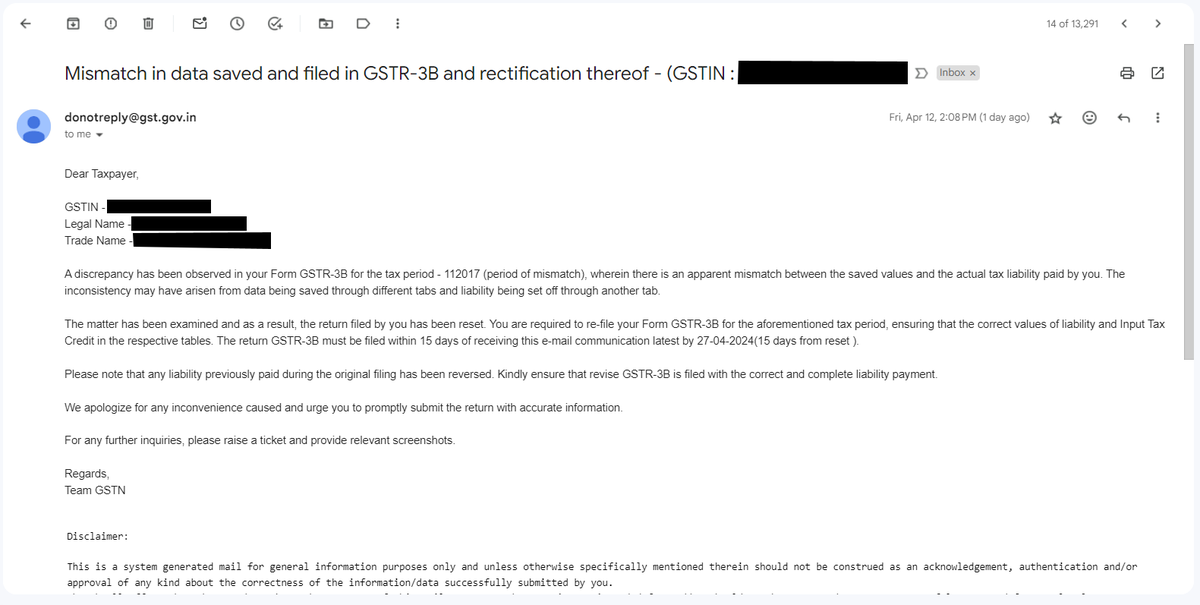
GSTIN asks to Re-Efile GSTR-3B & make rectification for the period 11/2017 in April 2024- Almost after 6 Years
Assessee furnished GSTR-3B for 11/2017 and due to technical glitch in the System Short paid Tax of Exact Rs 600000/-
During 2022, DGGI issued a summon in a separate case to the assessee. During the course of Investigation, the assessee on own motion paid the Differential Tax thru DRC-03 against which the Department as already issued DRC-04 aknowledging the payment of above Tax.
Now how will the assessee rectify when the tax has already been paid.
@cbic_india@AbhasHalakhandi@abhishekrajaram@BimalGST
📛💥 𝗜𝗺𝗽𝗼𝗿𝘁𝗮𝗻𝘁 𝗨𝗽𝗱𝗮𝘁𝗲 𝗼𝗻 𝗦𝗲𝗰𝘁𝗶𝗼𝗻 𝟭𝟲(𝟰) 𝗼𝗳 𝘁𝗵𝗲 𝗖𝗚𝗦𝗧 𝗔𝗰𝘁;
📢 𝗧𝗶𝗺𝗲 𝗟𝗶𝗺𝗶𝘁 𝘁𝗼 𝗮𝘃𝗮𝗶𝗹 𝗚𝗦𝗧 𝗖𝗿𝗲𝗱𝗶𝘁 𝘂/𝘀 𝟭𝟲(𝟰) 𝗼𝗳 𝘁𝗵𝗲 𝗖𝗚𝗦𝗧 𝗔𝗰𝘁 𝗖𝗵𝗮𝗹𝗹𝗲𝗻𝗴𝗲𝗱 𝗶𝗻 𝗦𝗖; 𝗡𝗼𝘁𝗶𝗰𝗲 𝗜𝘀𝘀𝘂𝗲𝗱 𝘁𝗼 𝘁𝗵𝗲 𝗥𝗲𝘃𝗲𝗻𝘂𝗲 𝗗𝗲𝗽𝗮𝗿𝘁𝗺𝗲𝗻𝘁
✅ The Hon’ble Supreme Court of India in the SLP filed in the case of Shanti Motors v. Union of India & Ors. [SLP(C) Dy. No.4695/2024 dated February 09, 2024], wherein the constitutional validity of Section 16(4) of the Central Goods and Services Tax Act, 2017 (“the CGST Act”) is challenged, which imposes a time limit for availing of Input Tax Credit (“ITC”), as being violative of Articles 14, 19(1)(g) and 300A of the Constitution of India.
The Hon’ble Supreme Court has admitted the SLPs and issued Notices to the Respondents, along with interim reliefs.
💐💐 Representing the Petitioners for Shanti Motors, Mr. Sujit Ghosh, Sr. Adv., 𝗠𝗿. 𝗕𝗶𝗺𝗮𝗹 𝗝𝗮𝗶𝗻, 𝗔𝗱𝘃., Ms. Mannat Waraich, AOR, Mr. Ajinkya Tiwari, Adv. and 𝗠𝗿. 𝗞𝗲𝘀𝗵𝗮𝘃 𝗝𝗮𝘁𝘄𝗮𝗻𝗶, 𝗔𝗱𝘃.
📌 𝗧𝗵𝗲 𝗻𝗲𝘅𝘁 𝗱𝗮𝘁𝗲 𝗼𝗳 𝗵𝗲𝗮𝗿𝗶𝗻𝗴 𝗶𝘀 𝗙𝗲𝗯𝗿𝘂𝗮𝗿𝘆 𝟭𝟵, 𝟮𝟬𝟮𝟰.
🔖 The Order can be accessed at: https://t.co/Q4GgJtpDk7
For services notified u/s S.9(5) i.e. Restaurant Services , Passenger Transport supplied through E-Comm operator (Swiggy, Zomato,Ola etc.)- E-Comm operator shall be treated as Supplier liable for Paying Tax.
-So E-commerce operator has the responsibility of generating Invoice also.
-If Supplier is liable for generating E-Invoice (i.e. crossing threshold, then E-Commerce operator shall generate E-Invoice on behalf of Supplier for supplies liable for E-Invoicing (B2B,Exports).
-Facility has been provided to E-comm operator for generating E-Invoice on behalf of supplier
Form more details check following information from GSTN:-
https://t.co/ttCGzE4dc4