Partner of NNS & Associates,is a professionally managed Chartered Accountant firm experts in audits
Co-Founder of Bizoptima Solutions
Co-Founder of Cleo Academy
🚨Most Important Post - Kindly Pay Attention
Year-End GST Compliance – Don’t Ignore This Before 31 March
Many GST notices start from year-end mismatches.
Before closing your books, check these 10 critical GST points 👇
🧵 Thread
CA Certificate Required for Wheat Exports
Under new DGFT notifications, wheat and wheat flour exports now require a CA-certified export turnover statement for the preceding five financial years — opening new certification work for practicing CAs
From 1 April 2026, ICAI is enforcing a strict limit of 60 tax audits per member, monitored via the UDIN portal for compliance. ICAI also launched a UDIN Mobile App (for Android and iOS) in February 2026, enabling members to generate and verify UDINs from their phones anytime. New field-level checks have been introduced while generating UDINs for GST and tax audit reports.
#WATCH | Chennai, Tamil Nadu: Subramania Bharathi, son of a daily wager working in a brick manufacturing unit, cleared the UPSC exam with the help of the State government's Naan Mudhalvan scheme.
Sharing his experience, he says, "My journey has been rather miraculous... This is my first attempt... With the support of Naan Mudhalvan, I was able to succeed in my very first attempt. I owe a lot to the government’s Naan Mudhalvan scheme and to the service coaching center. They were instrumental in my preparation. I started this journey when I was just 18 years old, without any guidance. My mother and father were my first inspiration, and they motivated me to serve my nation in the best way possible. I chose civil services as the best platform to contribute to the people at the grassroots level, like us..." (11.03)
Section 90: Applies when India has a Double Taxation Avoidance Agreement (DTAA) with a foreign country. It allows for bilateral relief, which can be in the form of either a tax credit (offsetting foreign taxes paid against Indian taxes) or a tax exemption (excluding the foreign income from Indian taxation, depending on the DTAA terms).
#TDSONRENT | #SEC194IB|#EmployeeHRA|#rentdeduction
If your monthly rent exceeds Rs 50,000, the tenant must deduct 2% TDS under Section 194-IB before paying the landlord and deposit it with the government.
The deduction is made by 31st March and must be deposited within 30 days. So for FY26 the deadline effectively runs around April-end after deduction.
The rule was introduced to address a common mismatch:
Tenants claiming large HRA deductions while landlords did not report rental income.
Non-compliance can be costly.
• 1% monthly interest for non-deduction
• 1.5% monthly interest for non-payment after deduction
• Late filing fee of Rs 200/day
• Penalties up to Rs 1 lakh #TDS #rent #March31
•If the landlord does not provide their Permanent Account Number (PAN), the TDS rate increases to 20% (as per Section 206AA)
Payment and Filing Process:
•Use Challan-cum-Statement Form 26QC to deposit the TDS online via the TIN-NSDL portal or authorized banks.
•Deposit within 30 days from the end of the month in which TDS was deducted.
•Issue Form 16C (TDS certificate) to the landlord within 15 days of filing Form 26QC
New initiative.
We've built https://t.co/vCWOrCwsLS, an AI tool to instantly map old Income Tax Act 1961 sections to the New Act.
Search in Hindi + English. More features coming soon.
It's early stage. We need YOUR feedback.
https://t.co/tNb0ZTnY3w
DM with suggestions!
When Filing Becomes Mandatory Even for Exempt/Agricultural Income
Under the seventh proviso to Section 139(1) (introduced in Finance Act, 2019, and unchanged in 2025), filing is compulsory if any of these high-value transaction conditions are met during FY 2024-25, even if total taxable income is zero or below the exemption limit:
Bank Deposits: Aggregate deposits exceeding ₹1 crore in one or more current accounts (e.g., business accounts common for nursery/plant sales).
Aggregate deposits exceeding ₹50 lakh in one or more savings accounts.
Foreign Travel Expenditure: More than ₹2 lakh (for self or others).
Electricity Consumption: Expenditure exceeding ₹1 lakh.
Other prescribed conditions (e.g., business turnover > ₹60 lakh under Section 44AB, or if claiming TDS/TCS refunds).
TAX AUDIT APPLICABILITY – AGRICULTURAL INCOME / EXEMPTED INCOME
#Agriculturetax#Incometax#Exemptedincome#Sec44AB#Taxaudit
No, tax audit under Section 44AB of the Income Tax Act, 1961, is not applicable to purely agricultural income, even if sales or turnover exceed ₹2 crore (or any other threshold like ₹1 crore or ₹10 crore).
Key Reasons Based on Latest Provisions (as of AY 2025-26):
- Agricultural income exemption: Under Section 10(1), agricultural income (as defined in Section 2(1A)) is fully exempt from tax. This includes income from nursery and plant sales if it qualifies as agricultural (e.g., derived from land-based cultivation in India without significant commercial processing).
- Section 44AB applicability: This section requires a tax audit for persons carrying on business if total sales/turnover/gross receipts exceed ₹1 crore (or ₹10 crore if cash receipts/payments ≤ 5% of total transactions, per the proviso to clause (a)). For professions, the limit is ₹50 lakh.
However:
- Agricultural activities are not treated as “business” under Section 2(13) (which defines business as trade, commerce, etc.). Agriculture is separately defined and exempt, so its turnover is excluded from the audit threshold calculation.
- If the income is solely agricultural and exempt, Section 44AB does not apply, regardless of the amount. This is affirmed in the ICAI’s Guidance Note on Tax Audit under Section 44AB (Revised 2025), which states that agricultural receipts are not included in turnover for determining audit limits, and pure agriculturists need not undergo tax audit.
No changes in recent Finance Acts: The Finance Act, 2025, and CBDT updates up to 2026 did not alter this position. The thresholds remain the same, and no new provisions mandate audits for exempt agricultural income.
63,000 restaurants will get email intimation Saksham Nudge to file updated returns and pay penal tax for supress the sales. !
Which Industry is Next Target, Any Guess?
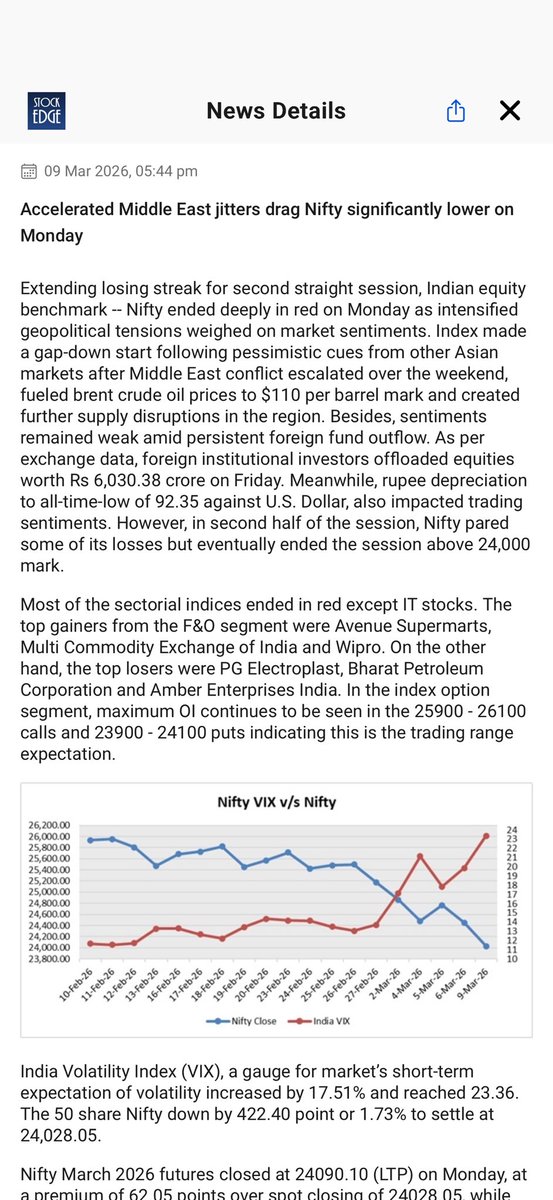
The Nifty Put-Call Ratio (PCR) measures market sentiment by dividing the total number of traded/open put options by call options. A PCR < 1 suggests a bullish outlook (more calls), while > 1 suggests a bearish outlook (more puts). Traders use it to identify market trends, overbought/oversold levels, and potential reversals.
Key Aspects of Nifty PCR:
- Meaning:
- PCR > 1: Indicates high put volume/open interest, signaling bearishness or hedging.
- PCR < 1: Indicates high call volume/open interest, signaling optimism or bullishness.
- PCR around 1: Represents neutral or balanced market sentiment.