U.S. VP JD Vance:
“We have tried for 21 hours, but we are returning to the U.S without an agreement. And I think that's bad news for Iran much more than it's bad news for the USA. They have chosen not to accept our terms."
Aletheia Capital Raises $LITE PT to $1,225 from $500 - Buy
Analyst comments: "We now forecast earnings to quadruple in fiscal years 2026E–2028E, driven by 2.5x to 3x top-line growth and 15 percentage points of margin expansion over the same period. The surge in LITE’s business is fueled by three structural tailwinds: (1) stronger-than-expected EML laser demand, with a 75% to 80% compound annual growth rate, from the rapid migration to 200Gbps diodes, effectively doubling content value; (2) ongoing market share gains, with LITE commanding about 90% share at 200Gbps; and (3) massive scaling of OCS sales in fiscal years 2026E–2027E, by a factor of 8x to 10x. With this explosive growth outlook, we now rank LITE among the fastest-growing artificial intelligence supply chains, if not the fastest, and retain the stock in our Alpha Portfolio. Risks are demand, execution, and geopolitics."
Analyst: Skye Chen
2/11 Daily Review:
- The $MU news this morning before the open got the memory names back to healthier areas on their charts. All closed above their 10 days $MU $SNDK $WDC $STX
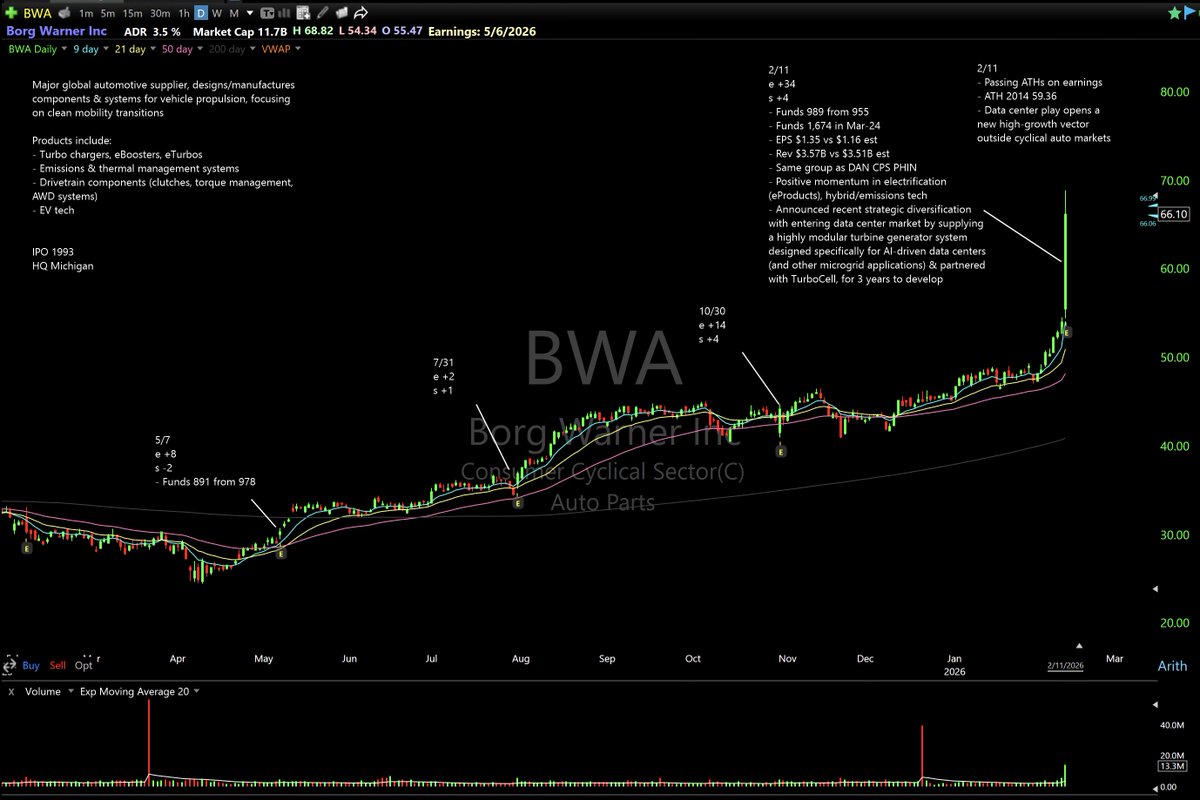
- Earnings of note from today $VRT $BWA $AEIS $SOLS (SOLS is a $HON spinoff)
- Metals showing conducive action $FCX $COPX $SLV $GDX $GLD etc.
- Oil/gas names continue to stand out $XOM $RIG $SLB $CVX $SLB $XLE $OIH etc.
- Strong names continuing to show strength $GLW $TER $CAT $DE $LITE $GEV etc.
- I'm remaining patient with my four main holdings right now $SNDK $LITE $GEV $BE as the market continues to be a bit choppy
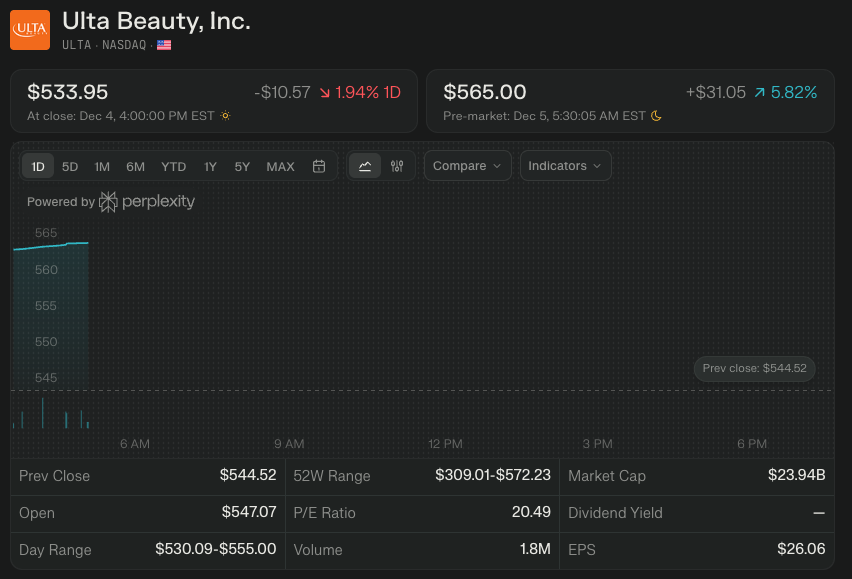
$ULTA is trading higher after a clean 3Q beat: comps +6.3% vs ~3.5% expected, EPS $5.14 vs ~$4.6 and gross margin up to 40.4%.
Mgmt raised FY25 comp/EPS and now guides FY26 margins at or above 12.3–12.4%. DA Davidson lifted PT to $650 and Goldman to $642 on the back of this.
Holy shit... this might be the next big paradigm shift in AI. 🤯
Tencent + Tsinghua just dropped a paper called Continuous Autoregressive Language Models (CALM) and it basically kills the “next-token” paradigm every LLM is built on.
Instead of predicting one token at a time, CALM predicts continuous vectors that represent multiple tokens at once.
Meaning: the model doesn’t think “word by word”… it thinks in ideas per step.
Here’s why that’s insane 👇
→ 4× fewer prediction steps (each vector = ~4 tokens)
→ 44% less training compute
→ No discrete vocabulary pure continuous reasoning
→ New metric (BrierLM) replaces perplexity entirely
They even built a new energy-based transformer that learns without softmax no token sampling, no vocab ceiling.
It’s like going from speaking Morse code… to streaming full thoughts.
If this scales, every LLM today is obsolete.
OpenAI reportedly plans a potential $1 TRILLION IPO in 2027.
For their sake, I hope they still have some market share left by then.
$GOOGL and Anthropic are eating their lunch 👇
The entire word relies on China for rare earths:
Brazil imports 97% of all its rare earths from China, the most among major global economies.
Turkey follows with 93%, while Germany and the UK import 91% and 89%, respectively.
Korea relies on China for 80% of its rare earth supply, while the US depends on China for 78%.
This comes as China’s estimated rare earth reserves have reached 44 million metric tons, 23 TIMES larger than the US.
China’s dominance in rare earths is quickly becoming one of the most powerful dynamics in the global economy.
The world needs China.
BREAKING: The average cost of a family’s annual health insurance premium has jumped +6% YoY in 2025, to nearly $27,000, an all-time high.
This marks the 3rd consecutive annual increase, following 2023 and 2024 gains of +7%.
In other words, premiums are now rising faster than inflation for the 3rd year straight.
Since 2000, the average health insurance premium has surged +350%.
Small businesses are seeing the largest health-rate increases, with over half reporting +10% or more premium hikes in 2025.
Health insurance costs have never been higher.
BREAKING: Demand for the Fed’s Reverse Repo (RRP) facility has fallen to $4.1 billion, the lowest since April 2021.
RRP usage, one of the financial system’s key excess liquidity metrics, has declined -$2.5 trillion since its December 2022 peak.
Meanwhile, bank reserves at the Fed dropped below $3.0 trillion, a level that many Fed officials consider the red line between abundant and scarce reserves.
Such a low level can strain the financial system, making it harder for banks to lend money, and can cause spikes in market volatility or even bank failures.
As a result, Fed Chair Powell just said that the end of QT may be approaching in the coming months as liquidity conditions tighten.
Market liquidity appears to be at a critical point.
The car market bubble is bursting:
Subprime auto loan delinquency rates have now surpassed 5% for the first time in history.
The 60-day delinquency rate for subprime auto loans has more than DOUBLED over the last 3 years.
Delinquency rates are now ~1.5 percentage points above the 2008 Financial Crisis peak.
At the same time, prime auto loan delinquencies rose to their highest in 15 years.
Meanwhile, the total value of auto loans in the US jumped $13 billion, to a record $1.66 trillion in Q2 2025.
An auto debt crisis is brewing.
The UK's bond market is collapsing:
Today, the yield on a 30Y Bond in the UK rose to 5.64%, its highest level since 1998.
Yields in the UK are now 15 TIMES higher than they were at the 2020 low, just 5 years ago.
What is happening? Let us explain.
(a thread)