Founders of the top investment firms tend to absorb new ideas and react quickly. They care less about hierarchy or credentials and more about whether someone sees where the world is going before consensus forms. The best investors will listen to an intern, famous founder, or outsider alike if the insight is real.
Firms that follow the market often over-index on status, pedigree, and consensus validation, which can cause them to miss larger shifts underneath the surface. You can usually tell who the real players are within just a few interactions.
Why is this important? Because the biggest investment opportunities often emerge when the prevailing narrative turns out to be wrong. Investors who are too attached to their beliefs risk missing those shifts entirely.
Being less ideological doesn't mean lacking conviction. It means having conviction without becoming attached to being right.
As investors, our job is to seek the truth, even when it challenges our own beliefs. We believe you can learn something from anyone, especially those with different perspectives. One principle we come back to repeatedly is truth > ideology, as Charlie Munger articulated so well:
“Another thing I think should be avoided is extremely intense ideology because it cabbages up one's mind. […] This business of not drifting into extreme ideology is a very, very important thing in life if you want to have more correct knowledge and be wiser than other people. A heavy ideology is very likely to do you in.”
— Charlie Munger, USC Gould School of Law Commencement Address, May 13, 2007.
Have we lost the plot?
The actual role of a VC is being a founder or an idea’s biggest hype person when no one else is ready to be.
Instead, the current system rewards a cohort obsessed with status, consensus, winning paper markup games, and frankly, their own hype.
Being someone's biggest hype person might actually help them become who they want to be.
Believe in their potential. Encourage their goals. Help them get there.
There's actual research on this. It's called the Michelangelo phenomenon.
Wanted: Mavericks.
mav·er·ick /ˈmav(ə)rik/ noun
An independent-minded person who refuses to conform to conventional ideas, rules, or expectations.
Venture capital was built by mavericks. Here’s to the next generation.
Incredible time at the Bridge Asia Summit in Singapore meeting LPs and GPs from across Asia. Many great conversations on geopolitics, shifting capital allocations, and more!
Perpetual Dissatisfaction
We see it in the most enterprising investors, too. It’s what makes the AUM debate complicated: some of the best managers can keep landing new opportunities and expanding them without losing their original edge & hunger.
@gokulr describes two patterns he has seen in founders: persistent dissatisfaction and expanding ambition.
Reaching a milestone can redefine the next goal.
From Tech Fit Talks with Ethan Lockshin.
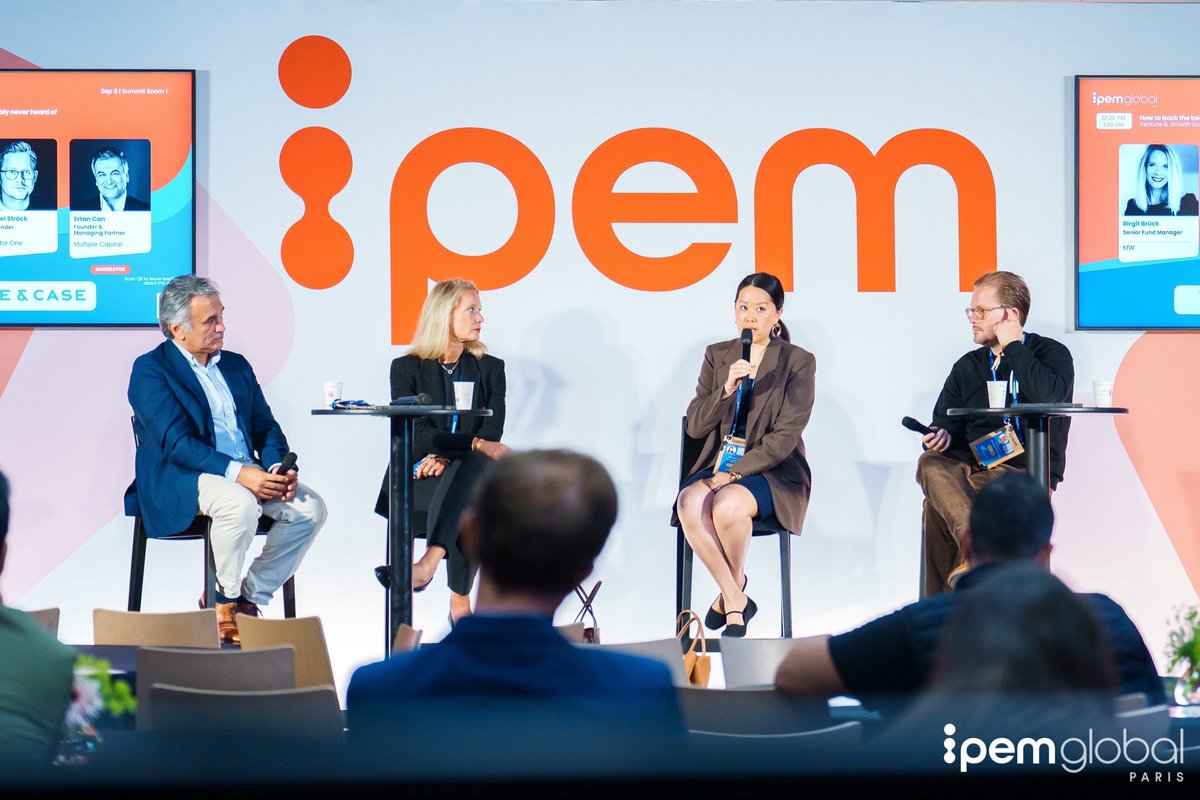
Great first @IpemMarket in the books! It was so much fun participating in the Venture & Growth Summit in Paris and joining a panel on backing emerging managers in venture capital globally.
Super interesting to hear so many of the same themes we’re thinking about in venture capital, from liquidity, secondaries, AI to better alignment between LPs & GPs, echoed across private markets.
The next decade belongs to the innovators
Are private markets becoming more idea constrained than capital constrained? We think so.
The best investors never seem to run out of ideas about the future. As competition crowds in, they reinvent themselves and, better yet, create what’s next.
The next decade belongs to the innovators
Are private markets becoming more idea constrained than capital constrained? We think so.
The best investors never seem to run out of ideas about the future. As competition crowds in, they reinvent themselves and, better yet, create what’s next.
The Illusion of Easy SPV Returns
Many investors overestimate their ability to pick winning co-investments and SPVs. If it were easy, every venture fund would be returning a 3–5x.
Remember, a unicorn valuation is not an exit. According to PitchBook, nearly 40% of U.S. unicorns have been held for at least nine years. And per Crunchbase, at the 2025 pace of exits, it would take 30 years for the current backlog of U.S. unicorns to go public or be acquired!
The following truism was drilled into our heads in finance class. It is more relevant than ever in venture capital today, especially when you account for survivorship bias.
Many fortunes were built when the industry had only a dozen serious players. Today, thousands of investors are competing for the same limited number of consequential deals each year.
At @MainCharacterHQ, we are looking for pioneers creating new games, not repeating old playbooks.
The game of venture capital and the game of backing venture capital funds are both power law games. If a 5x outcome seems out of reach, it may be worth asking whether you're playing the right game. A deal-by-deal SPV strategy may be a better fit than venture fund management.
Investor Tiers: True or false?
S-tier players want more S-tier players. They aren't threatened by excellence; they know it elevates everyone's game.
A-tier players track S-tier players closely. They study them, mirror them, and sometimes mistake proximity for mastery.
B-tier players regurgitate information, repackage it as "unique insight," and confuse curation with insight. They optimize for popularity & visibility.
C-tier players become flying monkeys. They amplify narratives, uphold the idea du jour, and attack others without ever stepping into the arena themselves.
To all the Main Characters whose best moves are still ahead. Here’s to making the next twenty years your highest scores yet. We can’t wait to see what you do next.
How do we move more people from market followers to category creators?
By changing incentives. By rewarding originality.
Originality is one of the rarest assets in investing. It takes the imagination to envision a different future, the judgment to distinguish possibility from probability, and the courage to commit while the evidence is still incomplete.
In this day and age, it can sometimes be hard to remember the purpose of venture capital.
At @MainCharacterHQ we believe the objective is simple:
1. Deliver superior returns to LPs.
2. Back important innovations before the rest of the market believes.
3. Repeat the process at scale without compromising either of the first two.
Everything else, the logos, the SPVs, the fees is a means to that end.
Access vs Selection
The last decade of VC was defined by access. The next decade (age of AI) will be defined by discernment and selection. All of us are drowning in access to SPVs & startups. What you pay an elite fund manager for is their superior filtering, due diligence and risk taking engine built up from years of trial and error & pattern recognition.
Risk taking is required: Not too much, not too little, just right!
Top quartile is table stakes. In venture capital, the real challenge is identifying managers capable of top 5% outcomes. The dispersion gap between top-decile and top-5% performance is often so substantial that it rivals the gap between average and top-decile managers.
Courtesy of @carta