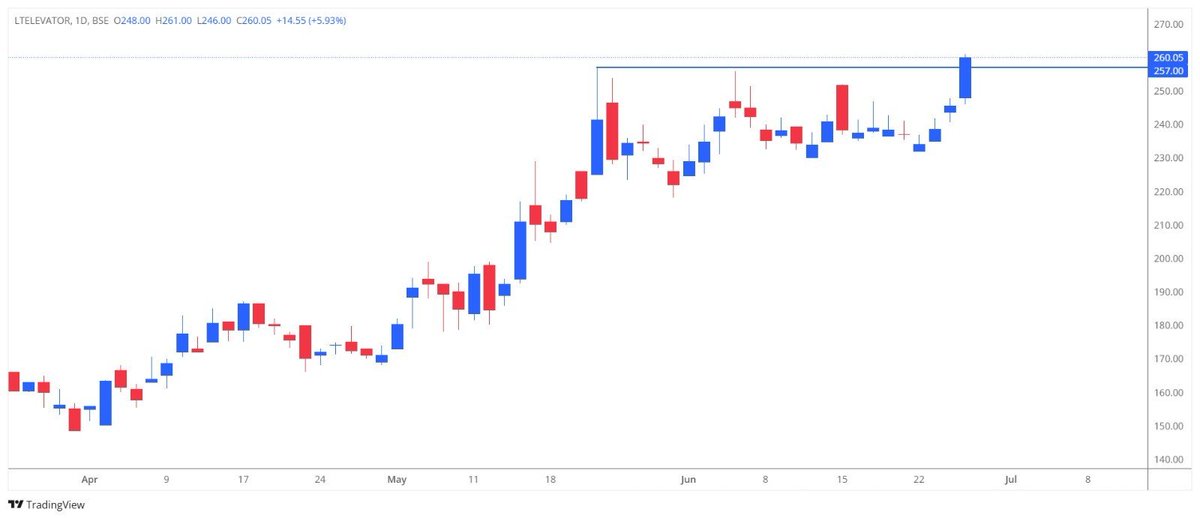
#LTElevator has kicked off FY27 with a bang!
The company has successfully raised ₹50 crore, backed by two marquee investors—Motilal (₹20 crore) and Bandhan Fund (₹20 crore). Capital will be deployed towards an unidentified acquisition, strengthening its inorganic growth strategy.
Now stock chart is showing a strong technical breakout, adding to the positive momentum.
Management has guided for 70–80% revenue growth in FY27 and reiterated its vision of crossing ₹400 crore in revenue by FY29.
#SME
Disc Invested since Listing
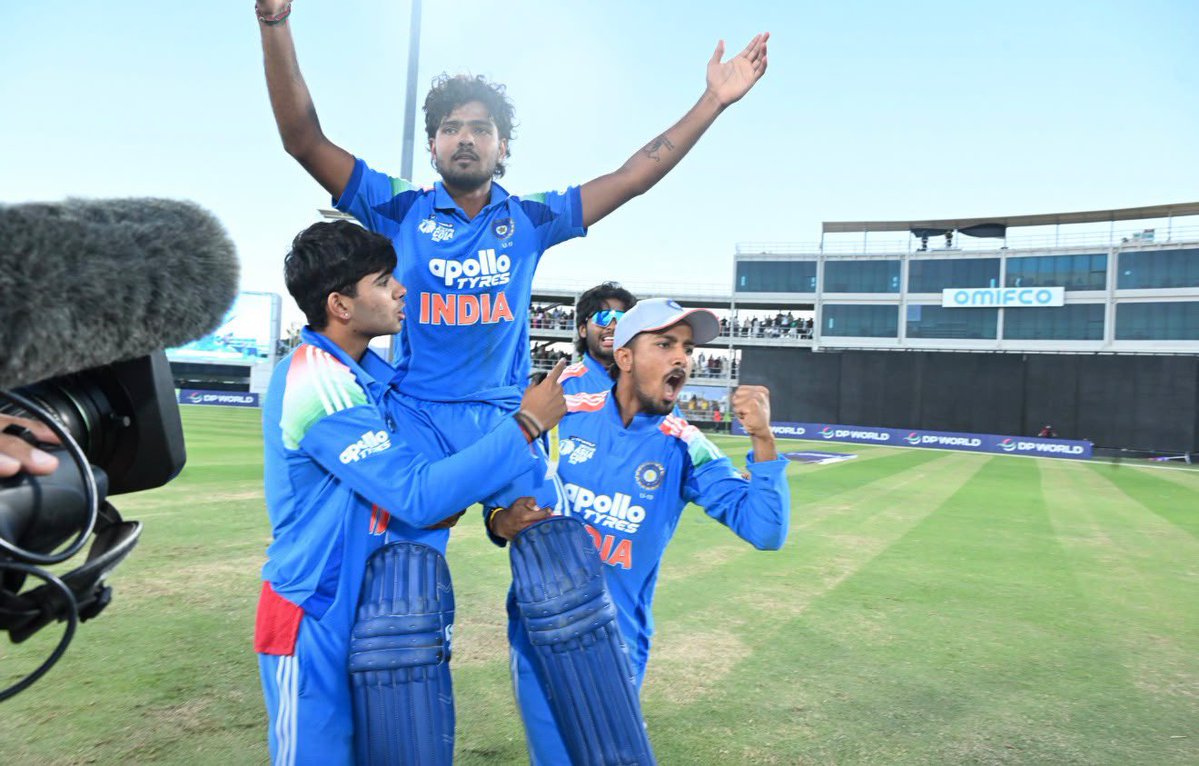
What a match! What a finish!
To beat Pakistan in an U19 Asia Cup final chasing 338 takes some serious character.
Lakshya’s 80, Aaryavir’s 58, and then Manal Chauhan and Mohit Ulva’s Jalwa when we needed a miracle. What a unbelievable victory.
Proud of these young Champions! 🇮🇳🏆
Vegorama Punjabi Angithi #HarResultKuchKehtaHai#GOOD
H1 CFO surged to ₹12.08 Cr, beating PAT after last year's cash conversion lag
👉 Food delivery demand across Delhi and NCR helped revenue reach ₹100.06 Cr for the half year as the kitchen network expanded. While costs for dairy inputs like paneer and cream rose, overhead expenses grew much slower than sales, which helped OPM improve to 13.85%.
👉 The most meaningful operational change is in cash generation. After converting very little profit into cash last year, CFO jumped to ₹12.08 Cr, running ahead of reported profit and removing concerns about money getting locked up in working capital.
👉 Fresh funds from the recent listing leave the balance sheet with substantial bank deposits and minimal debt. Management is deploying this money into building new cloud kitchens and a large banquet hall in Gurgaon, aiming to expand beyond pure online deliveries.
👉 The main obstacle remains extreme concentration on food delivery platforms, with Swiggy and Zomato accounting for 91.7% of sales in recent annual data. Until physical restaurants and banquet halls begin contributing meaningfully, profitability remains sensitive to any changes in platform commission rates.
👉 Growth catalyst: Deploying ₹20.49 Cr in unspent IPO funds to expand from 27 to 37 kitchens and open the 16,400 sq. ft. Gurgaon banquet hall targeted during FY27
👉 Road blocker: Swiggy and Zomato captured 91.7% of revenue and took ₹40.12 Cr in commissions, leaving margins exposed to aggregator fee hikes until offline dining scales, with no deadline set
Public NSE/BSE filings · Not Investment Advice
#VPAL #Q2FY27 #StockMarket #Earnings
𝐀𝐩𝐬𝐢𝐬 𝐀𝐞𝐫𝐨𝐜𝐨𝐦 𝐇𝟏𝐅𝐘𝟐𝟕 𝐂𝐨𝐧𝐜𝐚𝐥𝐥 𝐍𝐨𝐭𝐞𝐬-
- FY28 Topline Guidance- 80 Cr
- FY28 Topline can strech to 90-95 Cr
[with vertical integration]
- EBITDA margins guidance remains 35%.
[no dip for atleast next 2 years management said]
- PAT margins guidance- 23-25%
- At FY28 end[in next 15 months] we stand let’s say at 85 Cr topline & 19 Cr PAT then p/e comes to 29x fwd at 590 Cr Macap.
[Standard Aerospace & defense p/e runs at- 50-60x]
-Easy 2x i see in next 15-18 months.
[just my maths! ignore it don’t touch this stock if you feel pumped or something.]
Important note- no recommendations. your risk apetite, your allocation in portfolio, do read, do listen concall, see demand growth & trust on management. dyor.
Apsis Aerocom concall on 14th Nov!✔️
notes from previous concall-
- Targeting a topline of 500 cr in the next 5 years. [FY26 sales- 31 Cr]
- Order book was at 40 Cr & Another 100 Cr in the pipeline for FY27.
- Margins sustainable management said 35-40%.
let’s see how good this concall goes!!
Zelio E-Mobility🔥 🚀
H1FY27 Results
Amazing set ⚡
👉🏼Sales up by 120% YOY and 69% HOH
👉🏼Operating profit up by 144% YOY and 90% HOH
👉🏼OPM expanded to 12.6% vs 11.4% YOY and 11.2% HOH
👉🏼Profit up by 164% YOY and 90% HOH
Valuations 💲
👉🏼TTM EPS: 22.71
👉🏼TTM P/E: ~50
Already 3.2x from buying price.
A company which was repeatedly called fraud when price fell down in Mar 27.
#SME#MAHARAJA#SPEEDEX#MaharajaSpeedex#MaharajaAndSpeedexIndiaLimited
Maharaja & Speedex India H1 FY27 Concall Highlights:
👉H1 FY27 & Future Outlook :
▫️FY27 revenue growth of more than 45% guided (H1 FY27: +36% YoY)
💠H1 growth was held back by Q1 plant shifting and the ramp-up of lines added in February
💠No seasonality in the business; H2 gets festival and winter demand
▫️Medium-term growth: capacity +40% and revenue at least +50% a year, excluding complementary products
▫️EBITDA margin of ~19-19.5% expected to be stable
💠Economies of scale to be reinvested in brand marketing
💠Employee cost to be ~0.5% higher as a share of sales on senior hires and marketing team; no dilution expected in overall margin
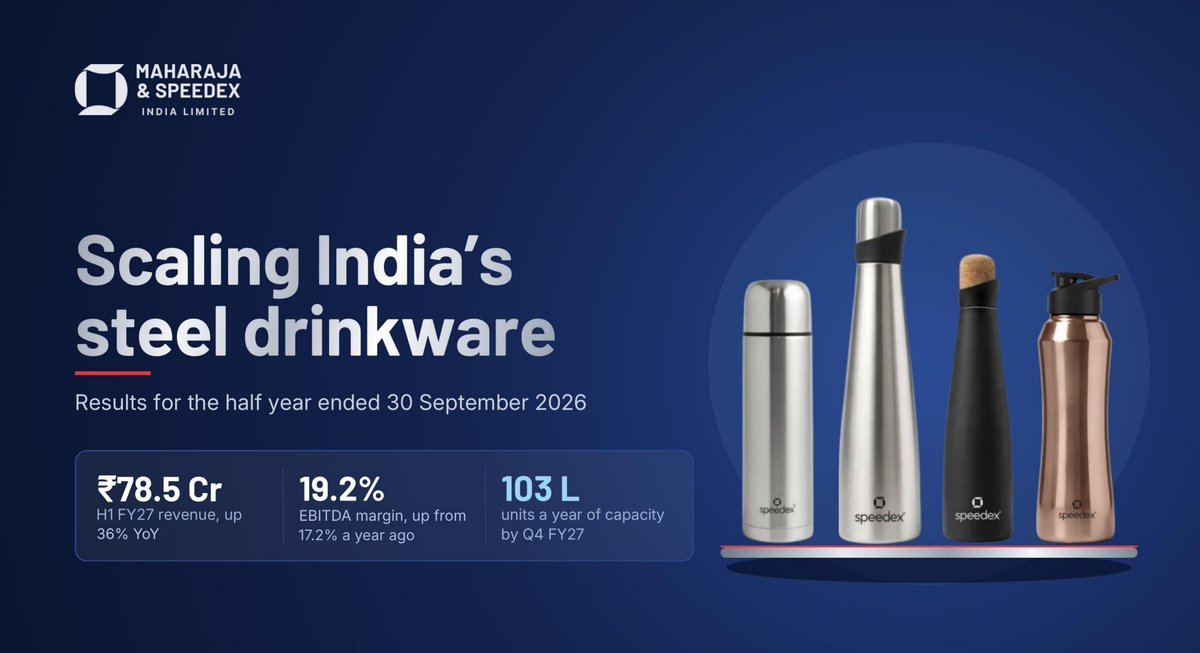
▫️H1 FY27 revenue ₹78.5 Cr, +36% YoY (H1 FY26: ₹57.6 Cr), +21% HoH
💠EBITDA ₹15.1 Cr, +52% YoY; margin 19.2% vs 17.2%
💠PAT ₹9.9 Cr, +50% YoY (12.5% margin)
���️Margin drivers in H1:
💠Outsourcing cut to ~6.5% of products from 11-12%, adding ~2% to gross margin
💠In-house coloring, printing and polishing job work added ~1.5% to gross margin
💠Value-added and novelty products rose to 23%+ of mix from 19%
💠~8% price increase taken on the war-related cost pressures
▫️Long-term vision: ~10% market share by FY31 (FY26: ~2% of a ₹5,700 Cr organised market; market projected at ₹9,400 Cr by FY31)
💠Share gain of 1-2 points a year
▫️Channel mix to shift to 65% own brand from ~45% in 3-4 years
👉Projects and pipeline:
▫️Capacity expansion:
💠Capacity at 72 lakh units a year, up from 63 lakh in March 2026, with the 9 lakh addition funded by internal accruals
💠IPO-funded 31 lakh unit addition goes live in Q4 FY27, taking capacity to ~103 lakh units a year
💠New lines take ~2 months to reach 85-90% efficiency; February lines were at 90% by early May and are at ~95% now
💠November monthly revenue run-rate of ~₹16 Cr
💠~₹23-24 Cr monthly revenue potential at 103 lakh units
💠Further 30-40% capacity possible from existing space with ₹20-25 Cr; new lines go live in 4-5 months
▫️Online (Speedex Online):
💠14.5% of H1 revenue vs ~10% last year
💠20-22% targeted by end of FY27 and ~25-30% by mid to end of next year
💠Currently on Amazon, Flipkart and Blinkit; more platforms to be added and the full category range launched by end of next quarter
▫️Distribution: ~100 distributors now; more than 150 by end of FY27
💠A distributor is counted only after three months of activity
💠Penetration in Tier 2 and Tier 3 cities to be increased
▫️New products:
💠More SKUs in the back-to-school category in H2
💠Insulated tiffin and bento boxes to launch in H2 next year through trading partners
💠In-house manufacturing lines for them to be set up once they cross ~5% of revenue
👉Q&A :
▫️Segment-wise EBITDA margin: OEM/ODM ~18%, distributor network ~20%, online ~21%
▫️OEM/ODM business:
💠~54-55% of revenue; 50+ customers including legacy brands, online players and regional players
💠No customer above ~10-11% of revenue; some customers have asked for 30-50% of capacity
▫️Competition (Cello, Borosil capacity additions):
💠No impact on demand or pricing expected
💠Competitors need long runs of ~40,000 pieces a time and would depend on OEM players like the company for the rest of their SKUs
💠Legacy brands that imported from China with 200+ SKUs now run 20-25 SKUs
▫️Import substitution:
💠Anti-dumping duty raised import costs by 20-25%, with BIS norms, higher dollar and freight adding to it
💠Imports from other countries are small and costlier
▫️Moat: 200+ SKUs from 60 ml to 2,200 ml, 5 design patents on feeding bottles and gym shakers; only big organised player in these categories
▫️Replacement cycle: not more than 6 months in most cases, driven by usage and trends
👉 Others :
▫️Balance sheet: all ₹22.7 Cr of short-term borrowings repaid; debt to equity 0.04
▫️Manufacturing: ~89% of products made in-house at two Sonipat units run by subsidiary Dewdrop Bottles
💠Presence in 17+ states with 101 distributors
▫️Listed on BSE SME in September 2026 via an ₹80 Cr IPO, subscribed ~30x
Look for comp delverng strong H1 performance, maintaining flat HoH numbers while posting gud YoY growth. Dese are the ones worth accumulating.
Also, keep a close watch on funda companies witnessing temp dips in revenue or margins if the mangement provides a convincing explnation.