Please stop being rational. You need to accept that everyone understands more than the ceo's of the memory co's. Macro econ 101 supply and demand doesn't apply any longer because "the market is effecient" @michaeljburry
Memory is on track to become nearly half the entire semiconductor industry reaching 48% by 2027 while capturing ~71% of all incremental industry growth.
That demand is already showing up in procurement, with $NVDA commitments jumping from $119B to $279B largely around memory while LTAs give $MU, $SKHY and Samsung a ton more visibility than prior cycles.
$MU is expected to make ~$35 Billion of profits THIS quarter!
There are only 4 other US companies in that ballpark: $NVDA, $AAPL, $GOOGL, and $MSFT. Their valuations are $5.4 Trillion, $4.6 Trillion, $4.2 Trillion and $3.7 Trillion respectively.
$MU is valued at $1.1 Trillion.
One of these is not priced like the others!
After $MU's last earnings, my view was that I don't see why this stock is trading under $1,800. Even at $1,800, it would be trading at forward PE of ~12, roughly a 40% discount from the S&P 500 forward PE of ~20.
The reasoning for my view on Micron's stock price is simple: $MU (and memory/storage companies in general, like $SKHY and $SNDK) are now selling their capacity as much as 5 years in advance with minimum price guarantees and very large pre-payments to guarantee supply.
Since this video, my conviction on Micron has only strengthened as we got an earnings report from $SNDK who also reiterated the 5-year customer contracts and supply shortages for the foreseeable future. Plus $AAPL is back praising their Micron partnership, and the Micron management team continues to emphasize the industry supply shortage for as long as they can see, despite having new facilities coming online in 2027 & 2028.
No company's revenues are guaranteed, but ironically, because of the historical nature of memory having caused PTSD, the memory companies might be the only companies that have airtight guarantees for a significant portion of their future revenues!
What made memory companies so volatile in the past, might be the key reason why they won't be as volatile for the foreseeable future.
https://t.co/0J7M15HbeK
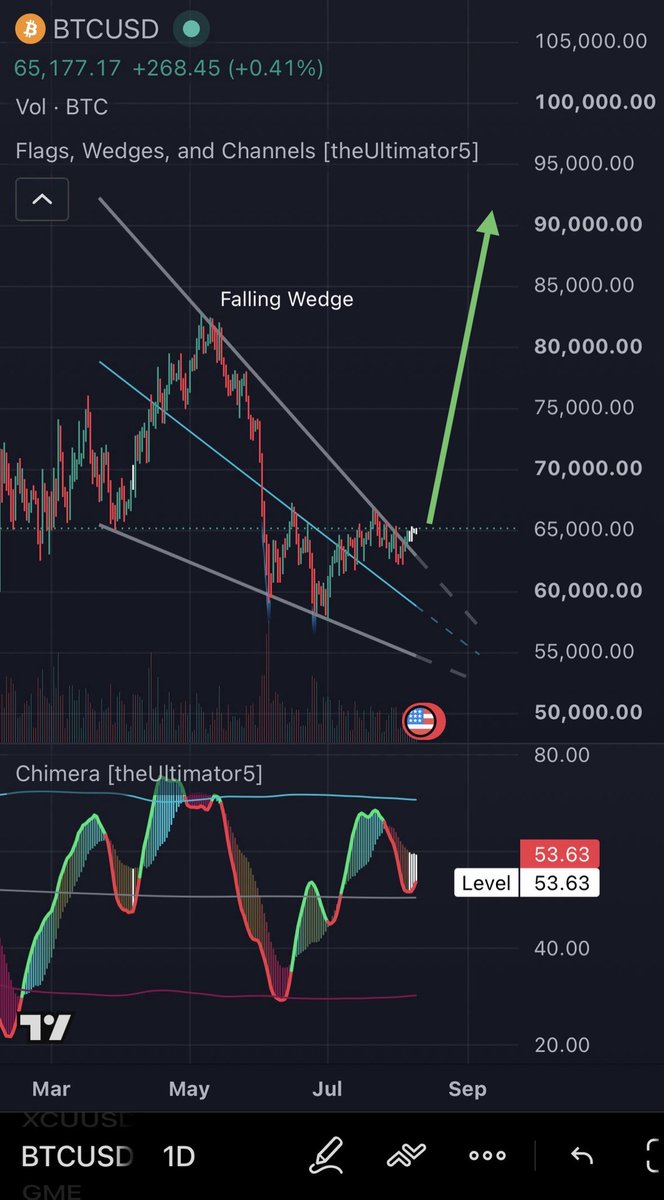
As much as I love to hate on Bitcoin bitcoin:native, I am currently bullish on it.
Here are my reasons:
1) Chimera is indicating major consolidation, which has historically resulted in sharp moves upwards. Looking back in time, daily consolidation candles have always resulted in upwards moves for Bitcoin.
2) Social sentiment and mentions are greatly reduced. Nobody (relatively speaking) is talking about Bitcoin anymore.
3) the US + Japan Yen intervention. Assets without the ability to print currency units (Bitcoin, Gold, Silver, etc…) tend to react positively when fiat currency is under attack. While the dollar isn’t under stress right now, the US is indirectly targeting the Euro. I expect a quick and strong response against the USD, which will push Bitcoin, Gold, and Silver sharply upwards in the short term.
4) My wedge indicator shows the price breaking out of a falling wedge, which is also a bullish sign.
Basically, I can’t find any reason to be bearish on Bitcoin in the near term and nobody is really talking about it anymore.
And she’s never wrong folks! $MU
The most ridiculous part of this is how she compares HBM (or memory in general) to “cobalt” and how Elon just engineered out Cobalt, therefore engineers will just engineer out memory. 🤣
Ironically Elon himself (and every other hyperscaler) says memory is the biggest bottleneck to building data centers faster.
Micron’s risk has already been removed due to its valuation. I see so many posts about memory prices peaking and people saying memory stocks will crash because of it. What I think so many people are missing is where these memory stocks are trading at. And that matters a lot. Most of them, like Micron, are trading at a 5x forward pe. Not 100x like PLTR. Not 200x like TSLA. 5X! That ridiculously low valuation takes out the risk of a memory slow down, IMO. Especially with these long term contracts. We know Micron is already sold out for 2027. So, we know they will make at least $150 EPS. That equates to $175 billion dollars of profit in one year. That’s real money. Whether it’s cyclical or not, it’s real money. Micron will make about $80 billion in profit in FY 2026. That’s $255 billion dollars by the end of FY 2027. let’s say they spend $70 billion in cap ex between both years. They will still be sitting on $185 billion in cash. Let’s pretend in 2028 earnings crash by 40% and level off there. This is absolutely not going to happen because memory demand will not be met by supply, and because of the LTAs, but just for fun let’s entertain the Bears and say earnings crash by 40%. That would bring FY EPS to around $90 a share or $103 billion a year in profit. The average stock in the SnP 500 trades at around 20x forward pe. If Micron traded at the average forward pe of the SnP 500, and its earnings crashed 40% in 2028, it would trade at $1800 a share. That’s about 100% higher than it trades at today. Plus don’t forget the cash. They would still be sitting on $185 billion in cash. That’s not fantasy. That’s a fact. That’s real money. It would take PLTR about 13 years to accumulate that much cash and MU will have that in about 13 months from now. That’s a done deal. Let that sink in. That’s me making up a scenario of Micron losing 40% of its earnings in 2028. They are already working on allocating orders for 2028. It is almost certain that they will not drop earnings by 40%. But even if they did, they would be undervalued here at $900 a share compared to the average stock in the stock market. Stocks like Nike, Union Pacific, Yum brands, Colgate, McDonald’s, JnJ, Proctor and Gamble, and Cummings all trade at around an average market multiple. Memory is literally one of the most important parts of Ai. It’s not a Big Mac or a pair of shoes. Micron’s stock would have to double from here just to trade at an average market multiple after its earnings crashed by 40%. WTF! 😳 Let me say that again, because it even surprises me a little bit. If Micron’s earnings drop by 40% in 2028, it would trade at $1800 a share if it had the same multiple as a company selling cheeseburgers. Even though Micron doesn’t sell cheeseburgers, they sell the most important ingredient in the Ai soup. Now, what if 2028 is just as good as 2027 for Micron? Forget about what if it grows in 2028. Just stays the same. That’s another $175 billion in profits. Then you can do the same exercise and imagine it’s earnings crash in 2029 by 40%. Now it has about $300 billion in cash even after spending its 2028 cap ex. My entire point is memory prices may not continue to rise forever. Margins will not rise forever. But neither of them have to rise forever to justify where Micron trades today. It is so severely undervalued that all of that risk is already baked in. Its cash has to have a value. That’s real money. Its earnings will not crash by 40%, but even if they do, Micron can still run 100% and only trade at the same valuation as McDonalds! And so many people on X are shitting their pants. Wild times.
This is the new $MU / Memory FUD: "Prices have peaked and will likely not go up any higher."
Let's just assume for a moment that's true. What does that mean for $MU?
Oh no! It would mean Micron would only generate ~$120/share of annual EPS and be limited to just 20% annual growth (roughly the rate at which they are growing capacity).
I guess we'll have to settle for just $150 of EPS for 2027 and $170 of EPS in 2028!
It's over guys! How is Micron going to survive with just ~$200 Billion of profits in 2028!?
📈 SPX closed 7757.64, +0.82% — right on the expected move top we published at 7755.
🎯 EVERY PLACE 7730 SHOWED UP IN THIS MORNING’S PLAN — BEFORE THE OPEN:
📌 TODAY AT A GLANCE: “7730 is the hinge. Above it, dealer hedging can help the move. Below 7690, downside needs volatility to wake up.”
📍 LEVELS & LINES: “7730 — the hinge. Dealer short calls sit here. Price moving into the strike forces hedging in the same direction.”
🌪️ VOLATILITY & POSITIONING: “That’s why 7730 is a hinge, not simply resistance.”
🗺️ ROAD MAP: “IF SPX clears 7730, THEN 7750 becomes the first upside test. IF SPX clears 7750, THEN 7755 EM top comes immediately into play.”
📌 ADDITIONAL CONSIDERATIONS: “7730 is behavioral. Dealer short calls are the important part, not the roundness of the number.”
📈 We undercut 7730 once early, reclaimed it inside a couple of bars, and that was the entire downside.
🐐 That’s what positioning tells you that price can’t. Structure first, story second.
SEE THE FULL DAILY PLAN THESE LEVELS CAME FROM — PUBLISHED EVERY MORNING BEFORE THE OPEN:
https://t.co/jp7NuIndWt
#SPX #0DTE #Options #GEX #Gamma #SP500 #NFP #OptionsTrading #MarketStructure
📈 $SPX POSITIONING UPDATE
This morning we highlighted 7,650 as the key dealer call wall and said the real question wasn't whether price would reach it—it was whether the wall would hold, or whether the builders would move it (we suspected they would)
They moved it.
The 7,650 call concentration has been closed and rolled up to 7,690, making 7,690–7,700 the new Line in the Sand (LIS).
This is why I focus on positioning, not just price. The market didn't overpower resistance—the resistance moved higher.
📊 Updated Map
🟨 7,665 — First stretch reference
🧱 7,690–7,700 — NEW Line in the Sand (LIS)
⚡ Above 7,700 — Dealer positioning must be recalculated
🐐 Victory Lap: This morning's Daily Plan said the key wasn't whether price reached 7,650—it was whether the traders who built that wall would move it. They did.
That's the kind of real-time positioning alpha Discord members receive as it develops.
📊 Source: Options Depth
@OptionsDepth
🔄 Retweet if you find it valuable.
Better decisions. Better trading. Better outcomes. ❤️
Gotta WATCH the FLOW to be in the KNOW 🐐
#SPX #0DTE #OptionsTrading #GammaExposure #OptionsFlow #DealerPositioning #MarketStructure #Fintwit
Trump's latest TACO is the final confirmation I needed that this war is over.
Here's why:
1. Trump can't TACO anymore. It won't work. Iran won't fall for it again, and neither will the rest of the world. He's used up all his bluffs.
2. Iran recently established escalation dominance. With its preemptive strikes on Jordan and Kuwait (the first of their kind), the attack on American ships off Egypt (likely by Iran), the cyberattack on Minnesota, and the Houthis' involvement, Tehran has shown it's willing to keep raising the stakes.
Trump can't simply return to the tit-for-tat cycle of the past few weeks. Iran has made it clear it will respond disproportionately.
3. A prolonged blockade isn't a viable option either. Iran has indicated it would treat one as an act of war and would likely respond militarily.
4. Yesterday's TACO also confirms Trump doesn't have a good military option and doesn't want another full-scale war. Depleted interceptor stockpiles, low Strategic Petroleum Reserve levels, high energy prices, pressure from Gulf allies, and the approaching midterms make another war an irrational, politically disastrous choice.
So what's left?
Negotiate a deal, and walk away accepting responsibility for what could become one of America's biggest foreign policy blunders.
Every other option is likely to make things worse for both Trump and the United States.
The irony and ridiculous nature of the market in the short-term is this:
$MSFT has gained nearly the value of a whole $MU in 3 days due to excitement around AI. Yet, Micron, who will likely make more profits than Microsoft in the next year, is valued at around $900 Billion.
If AI is exciting for Microsoft, it should be doubly exciting for Micron.
There is a bread distributor who sits between the big bakeries and the retail shops.
Every day the shops place orders for all kinds of bread claims — some want protection if bread prices spike, some want protection if they crash, some just want to offload risk.
The distributor always takes the other side. He never decides in advance “I’m going to stock more long-gamma positions today.” He simply absorbs the flow that walks through the door.
At the end of the order flow he looks at his book and discovers he is either:
• Long gamma His inventory forces him to buy bread from the bakeries when the wholesale price dips and sell it to the shops when the price rises. Result: he is constantly adding liquidity on the way down and removing it on the way up. The wholesale bread market stays more stable and two-sided.
• Short gamma His inventory forces the opposite behavior: he only buys after prices have already risen and only sells after they have already fallen. Result: he withdraws liquidity during moves and amplifies them. The market becomes thinner and more violent.
Daily Net Gamma is simply the distributor checking that book and seeing which of the two forced inventory-management styles he is locked into for the rest of the day.
It is not a forecast or a deliberate decision to “supply more liquidity.” It is the mechanical consequence of the positions the customers have already pushed onto him, and that consequence dictates how he will interact with the bread market.
Now is the time to start being excited about buying memory stocks.
I will be a buyer in $DRAM, $MU, and $SNDK soon. Are you ready to be a millionaire with me?
All my buy and sell signals in Discord @ https://t.co/OX1nG4cX8V.